Before you place another trade…
…make sure you use this 5-part formula that makes every trade a SAFE trade:
Why are we giving this away?
Because we think you’ll love it so much that you’ll come back to us down the road for more advanced training.
Make sense?
Click here to download the Safe Trade Options Formula…
Good Trading,
Bill Poulos
P.S. Take 5 seconds and get your free copy of the “Safe Trade Options Formula” right now before you close this email.
Workday’s Buyout Funding Looks More Real. The Stock Is Still Below Its High.
The question for Workday on Thursday was not whether a buyer exists. It was whether the money could actually be assembled. By the close, the answer looked more encouraging than it did three weeks ago.
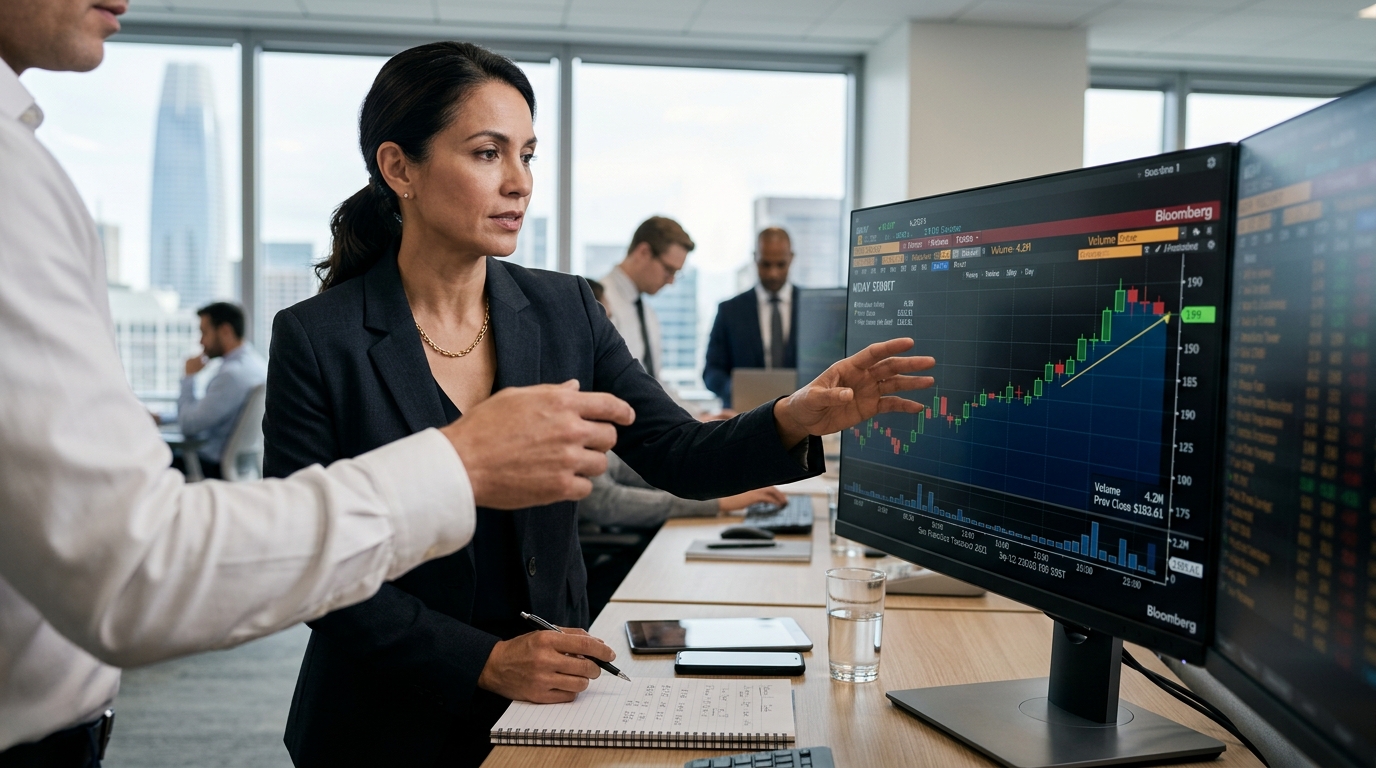
WDAY opened at $183.61 and traded to nearly $201 on volume of roughly 4.2 million shares, almost double the recent daily pace, before settling near $199. The catalyst was CNBC’s David Faber, who reported Thursday morning that his conversations with people close to the situation had turned more constructive. “I am hearing a bit more optimism around the possibility that this thing still might happen,” Faber said, adding: “financing packages are being provided out there, equity is continuing to be raised in a significant way.”
Faber’s remarks contrast with his comments last month, when he cautioned that financing for a Workday deal may be difficult. That earlier skepticism had weighed on the stock since the initial Reuters report in August. Thursday’s update changed the tone.
Analyst Targets
- RBC Capital: Outperform, $240 price target
- Barclays: Overweight, $288 price target
- Guggenheim: Buy, $275 price target
- Goldman Sachs: Neutral, $164 price target
- Stifel Nicolaus: Hold, $255 price target
The Deal Architecture
Silver Lake is in talks to take Workday private in a deal that would rank among the largest software buyouts ever. A transaction of that size would almost certainly require Silver Lake to bring in partners. Last year the firm teamed with Saudi Arabia’s Public Investment Fund and Affinity Partners on the roughly $55 billion take-private of Electronic Arts. The same syndication model appears to be forming here.
Buyout firms have largely stayed out of large software take-privates this year, as the rise of artificial intelligence has made the future growth and value of traditional software harder to judge. A completed Workday deal would end that drought decisively.
What the Fundamentals Say Without a Deal
Strip out the M&A premium and the picture is actually defensible. In its fiscal Q2 2027, reported August 27, Workday posted total revenues of $2.649 billion, up 12.8% year over year, with subscription revenues of $2.471 billion, up 13.9%. Non-GAAP operating income was $824 million, or 31.1% of revenues, compared to $680 million, or 29.0%, a year earlier.
AI is now driving more than 25% of new annual contract value, with more than 5,500 customers using at least one of Workday’s organic agents. Full-year fiscal 2027 subscription revenue guidance was raised to $9.940 billion to $9.950 billion, representing 13% growth, with non-GAAP operating margin guided to 31.0%. That is not a business in distress. It is a business that has been mispriced.
Workday’s shares had slipped about 15% in 2026 before Thursday and sat more than 40% below their February 26, 2024 peak, as investors questioned how durable established software franchises will prove as AI reshapes the market. Even after Thursday’s rally, WDAY remains about 20% below its $249.85 52-week high.
Forward Scenarios
Bull: Financing closes, a formal offer emerges at a premium to current levels, and WDAY rerates toward $220 to $230 as arb spreads compress. The playbook Silver Lake used on Electronic Arts, pulling in sovereign wealth and co-investors, repeats here.
Base: Talks continue through Q3 without a formal bid. The stock holds the $185 to $200 range, supported by solid fundamentals and ongoing deal speculation. Analysts revise targets higher on AI monetization progress.
Bear: Financing stalls again. A second Faber update turns cautious, the deal premium evaporates, and WDAY gives back Thursday’s gains, retesting the $175 area. Uncertainty around the Silver Lake buyout could act as a negative catalyst, especially with the stock trading at roughly 4x revenue while many large-cap SaaS peers are closer to 3x.
Technical Overlay
Thursday’s session produced a decisive gap through the $190 level on elevated volume. The $199 to $201 zone is now the first test: a close above that on follow-through volume opens the path to $210, where resistance from the August post-announcement consolidation sits. Below $190, the deal premium deflates quickly. The 52-week high at $249.85 remains a distant reference point unless a formal bid materializes.
Bottom Line
The financing news matters because it changes the probability distribution, not because it confirms a deal. Take-private chatter of this kind typically follows a familiar sequence: initial sourcing reports, a run-up in the target’s shares toward an implied premium, then either confirmation with financing details or a denial that unwinds most of the move. Thursday moved the sequence forward. What happens next depends on whether Silver Lake and its co-investors can actually close the capital stack on the largest software LBO in years. The fundamentals argue the business is worth more than where it traded before August. The stock price will reflect which story the market believes first.