Analyst Targets
- Wedbush (Dan Ives): Outperform, $600 target
- Cantor Fitzgerald: Overweight, $485 target
- StoneX: Buy, $475 target
- JPMorgan: Neutral, $415 target (trimmed from $445)
- Jefferies: Hold, $400 target
- BNP Paribas Exane: Underperform, $268 target
The Delivery Number Is Not the Story
Tesla delivered 486,532 vehicles in Q3 2026, down 2.1% from last year’s record 497,099 and about 25,000 above Wall Street’s consensus of 461,974. Shares closed at $370.59 on October 2, up 4.65%.
The beat is not in dispute. What matters now is how Tesla got there, and what it costs.
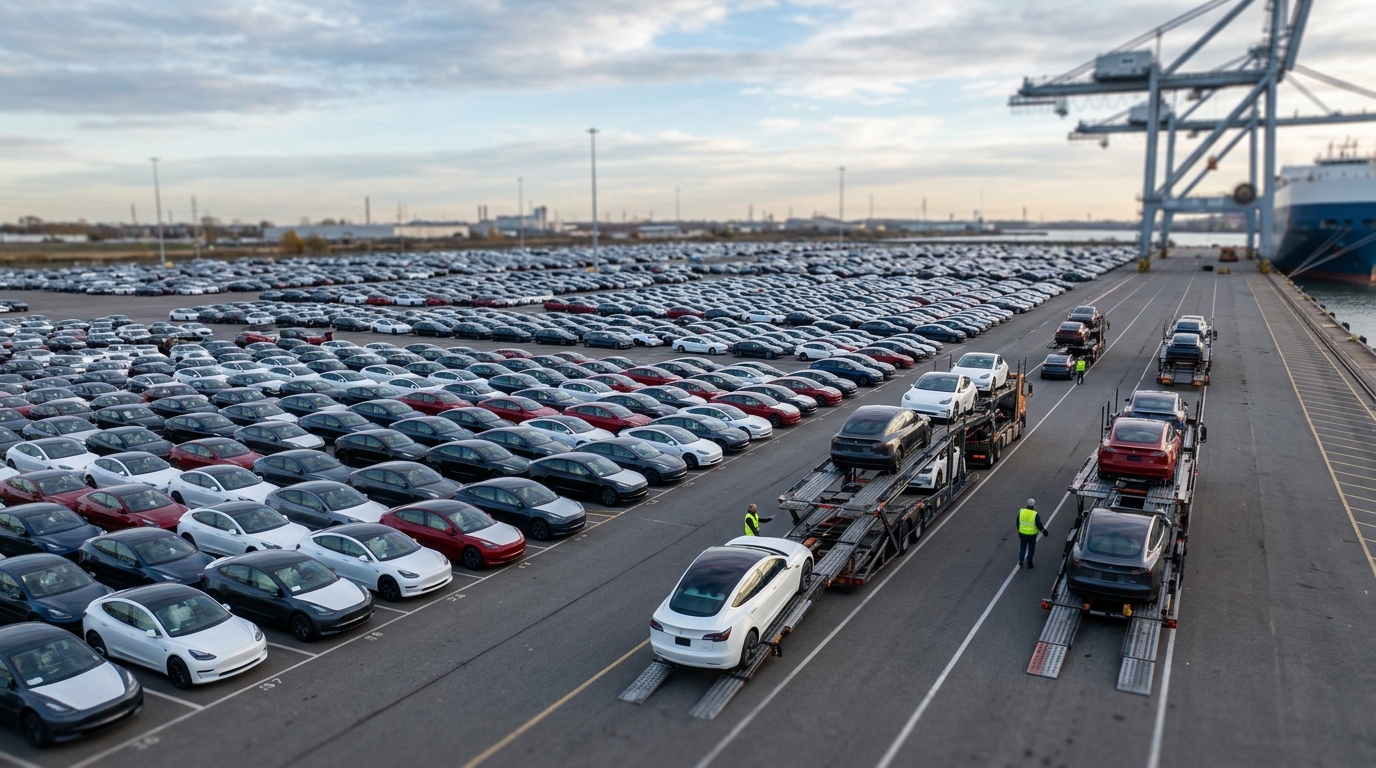
Tesla delivered 22,141 more vehicles than it built. That is the second quarter in a row that it has worked down inventory, and between Q2 and Q3, it has now cleared the roughly 50,000 excess vehicles it built in Q1. Selling out of a warehouse is not the same as selling into demand, and October 21 is when that distinction becomes visible in the margin line.
Company Profile
Tesla designs, manufactures, and sells battery electric vehicles, energy storage systems, and solar products across North America, Europe, and Asia. Its two mass-market platforms, the Model 3 and Model Y, accounted for a vast majority, or about 98%, of its deliveries this quarter. The energy storage segment, built around the Megapack commercial battery system, has become an increasingly important margin contributor alongside the automotive business.
The Numbers
- Deliveries: 486,532 vs. 461,974 consensus (+5.3% beat)
- Production: 464,391 vehicles
- Inventory drawdown: 22,141 units
- Model 3/Y deliveries: 478,237 (98% of volume)
- Other Models: 8,295 (Cybertruck, Semi, remaining Model S/X)
- Energy storage deployed: 13.7 GWh
Why the Stock Moved, and Why the Debate Isn’t Over
The beat is real, but it is a beat against a consensus that had already been cut hard. Tesla’s own compilation, published on September 29, put the mean at 461,974, which was 7.1% below the year-ago quarter.
Clearing inventory is good for cash, but it usually goes hand in hand with price incentives, and that is the margin question the October earnings report has to answer. In Q2, the automotive gross margin, excluding regulatory credits, decreased to 16.3% from 19.2% sequentially. Whether Q3’s drawdown of another 22,141 units required similar concessions is the number investors are now pricing around.
The storage segment has been a faster-growing and higher-margin contributor than vehicles in recent periods, so any slowdown there carries weight in the earnings model even when vehicle volumes beat. The only quarter when Tesla reported stronger energy deployment figures was Q4 2025, when 14.2 GWh was deployed, making the 13.7 GWh result a sequential near-flatline on that front.
Macro Context
At $370.59, TSLA is trading about 24.3% below its 52-week high of $489.88 from December 2025. The delivery recovery matters for a re-rating, but only if margins follow. Competition from BYD in China and Europe remains the structural headwind; William Blair analyst Jed Dorsheimer noted that Tesla’s Megapack earned entry into Nvidia’s DSX Ready program, qualifying it as a key infrastructure component for AI data centers, an underappreciated tailwind for the storage segment that the Q3 deployment figure partially obscures.
Forward Scenarios
Bull ($480): October 21 shows automotive gross margin at or above 18%, confirming the inventory draw required no material discounting. Storage execution improves in Q4. Robotaxi and FSD monetization timelines hold.
Base ($370-$395): Margins come in at 16-17%, roughly flat with Q2, signaling incentive-driven volume. Deliveries trend upward in Q4 as inventory resets to lean levels. Analyst Gary Black estimates Tesla’s days of sales outstanding in global inventories fell to 12 at the end of Q3, down from 15 in Q2, an exceptionally lean figure for an automaker of this scale. That baseline favors Q4 production growth.
Bear ($268): Margin comes in below 15%, confirming that clearing 50,000 units over two quarters required sustained price cuts. Storage disappoints again in Q4. Free cash flow worsens from CapEx now running above $25 billion in 2026.
Technical Overlay
TSLA closed at $370.59 on October 2, with an intraday range on October 2 of $374.60 to $359.41. Price momentum shows TSLA trading in the middle of its 52-week range and below its 200-day simple moving average. The $380 level is near-term resistance, where sellers have shown up twice in the past month. A sustained move through $385 before October 21 would suggest the market is pre-pricing a margin recovery. Below $355, the stock likely retests its July lows.
Bottom Line
The delivery number is the best Tesla has posted without the federal EV credit. It is Tesla’s best-ever quarter without the $7,500 US federal EV credit, and third-best overall. That matters. What the market cannot yet determine is whether demand or discounting drove it. Factors such as average selling prices, financing incentives, product mix, and underlying costs will be crucial for assessing sustainable profitability when Tesla reports earnings later this month. That answer arrives October 21. Until then, $370 reflects optimism on units and agnosticism on margins, which is exactly the right posture.