Equity analysts spent Wednesday asking whether CoreWeave’s stock had fallen too far. Credit desks were asking something else entirely: whether the AI buildout was ever financed on terms that could survive a revenue shortfall.
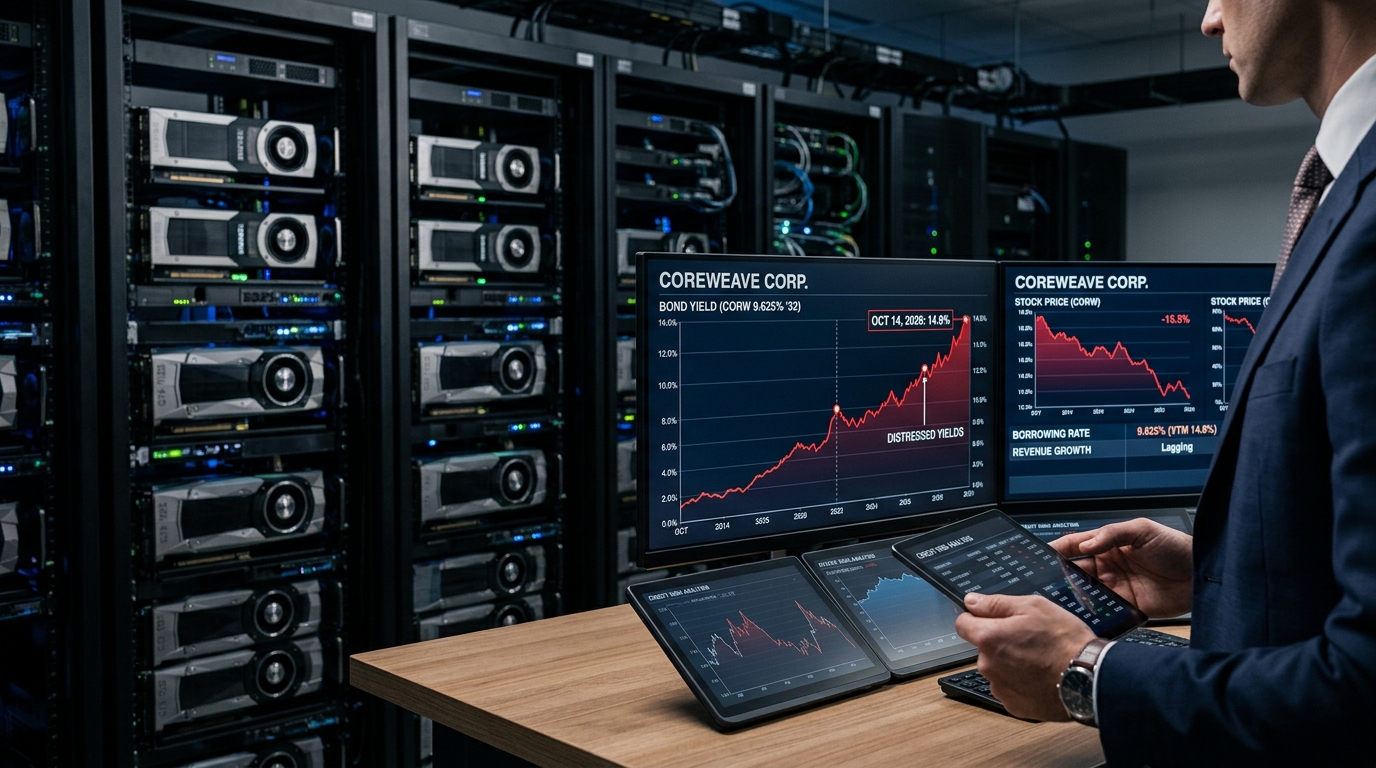
The distinction matters. CoreWeave’s stock fell 15.5% on October 14, 2026, while the yield to maturity on its 9.625% bond due in 2032 settled at 14.8% and its 9.75% bond due in 2031 sat at around 14.9%. The company’s $4.0 billion in unsecured bonds, issued earlier this year, are trading below 80 cents on the dollar, firmly in distressed asset territory. Those are not the numbers of a company priced for a rough quarter. They are the numbers of a company priced for existential doubt.
What Gartner Actually Said
The proximate trigger was a Gartner forecast published Wednesday. Gartner’s senior director analyst Will Sommer said that through 2030, AI data center owners would need to generate a cumulative $8.5 trillion in revenue to cover announced capital spending, financing costs, and a 12% return on invested capital, but total enterprise and consumer AI revenue attributable to data centers is forecast to reach no more than $3.6 trillion. By 2030, Gartner predicts that cost pressure and a lack of a differentiating business model will force over 80% of neocloud providers to cease independent operations.
That last phrase deserves a close reading. Ceasing independent operations may include acquisition, partnerships, or outright failure. Not every company that disappears will fail, Sommer noted. But for bondholders, the distinction between acquisition and default has a narrower margin than it does for stockholders. Recovery values in a forced sale of GPU collateral are not the same as recovery values in an orderly one.
The Spread That Tells the Story
The analytical problem with CoreWeave has always lived in the gap between what it borrows at and what it earns. D.A. Davidson analyst Gil Luria estimates CoreWeave borrows at around 9% and earns about 1% on its investments, and has warned on the Prof G Markets podcast that the equity could end up worth zero if the AI spending boom turns. Even the company’s own more optimistic target of 4% to 5% returns sits well below its cost of capital.
CoreWeave’s interest bill jumped to $640 million in the second quarter from $267 million a year earlier, and it lost $626 million even as revenue more than doubled to $2.58 billion. It also faces about $4.4 billion in debt payments for the rest of 2026 and $6.2 billion in 2027. CoreWeave sold its 2032 bonds in June at 9.625%, so in four months the cost of lending to it without collateral jumped about five points. That shift happened in the credit market first, before equity markets fully absorbed the implications.
CoreWeave bonds fell below 80 cents on the dollar, and credit-default swaps signaled sharply higher perceived default risk. The cost of insuring against CoreWeave’s debt also surged past 1,000 basis points to record highs.
The Contagion Problem
The selloff did not stay contained. Nebius fell about 10%, Oracle dropped another 8.8%, and several AI-adjacent infrastructure names fell by double digits. Oracle, which is not a neocloud but has borrowed heavily to finance its data center buildout, closed 8.8% lower. Yields on Oracle’s 6.25% bond due in November 2032 rose to about 7.24%. Oracle’s five-year CDS also widened sharply.
Gartner argues that hyperscalers can sustain AI investment using revenue from other activities, whereas neoclouds must earn returns from AI infrastructure and related platforms sooner. That asymmetry is what makes CoreWeave’s capital structure uniquely exposed. It cannot offset a GPU margin compression with a cloud software business. Every dollar of interest is paid from the same narrow revenue pool that Gartner now says is structurally insufficient for most of its peers.
The Bull Case Has a Deadline
CoreWeave CEO Michael Intrator dismissed the sell-off in an internal memo, telling staff that the market was acting “irrationally” and that the company’s contract backlog is large enough to cover its obligations. CoreWeave’s backlog stood at $104 billion with its most recent quarterly results. That is a real number, and it is the bull case’s strongest argument.
But backlogs are promises, not cash. When the gap between borrowing cost and return exists, borrowing more to grow destroys value rather than creating it. The higher market yield does not change interest payments on CoreWeave’s existing fixed-rate bonds, but it signals that raising new debt or refinancing existing obligations could become much more expensive.
Stocks to Watch
CoreWeave (CRWV): The center of the debate. The bond market is pricing a non-trivial probability of restructuring. Even investors who disagree should watch the October 28 date, when new contractual limits take effect on the company’s ability to inject equity into its OpenAI special purpose vehicle.
Oracle (ORCL): Not a neocloud, but carrying the debt load of one relative to its revenue base. Oracle generated roughly $19 billion in quarterly revenue, putting it on pace for approximately $75 billion annually, while taking on debt loads designed for businesses three to four times larger. Its CDS at record highs suggests credit markets see the comparison as apt.
Nebius (NBIS) and DigitalOcean (DOCN): Caught in the same reclassification. Neither carries CoreWeave’s debt load, but both now trade in a market that is asking the same structural question of every neocloud: not whether demand is real, but whether the financing terms assumed to capture it ever made sense.