October 20, 2026
A $115 million non-cash charge swamped a landmark quarter for the Swiss industrial giant, but the order backlog tells a different story.
Analyst Targets
World’s Largest Investors Are Moving Their Money (Not Into AI)
While the media distracts you with stories about the next big AI IPO… The world’s largest investors are moving their money into one asset – at the fastest pace in a generation. This asset has crushed the S&P 500’s return over the past 12 months… More than TRIPLED the S&P 500’s return in 2025… and has outperformed the S&P 500 over the past 25 years by more than 1,100 percentage points. According to one Wall Street veteran, with over 40 years of professional investing experience… the biggest gains could be still ahead. That’s why he’s urging you to make one money move now.
- Consensus EPS estimate: $0.79 (Q3 2026)
- Consensus revenue estimate: $9.74–$9.77 billion (Q3 2026)
- Operational EBITA consensus: $2.0 billion
The Disconnect
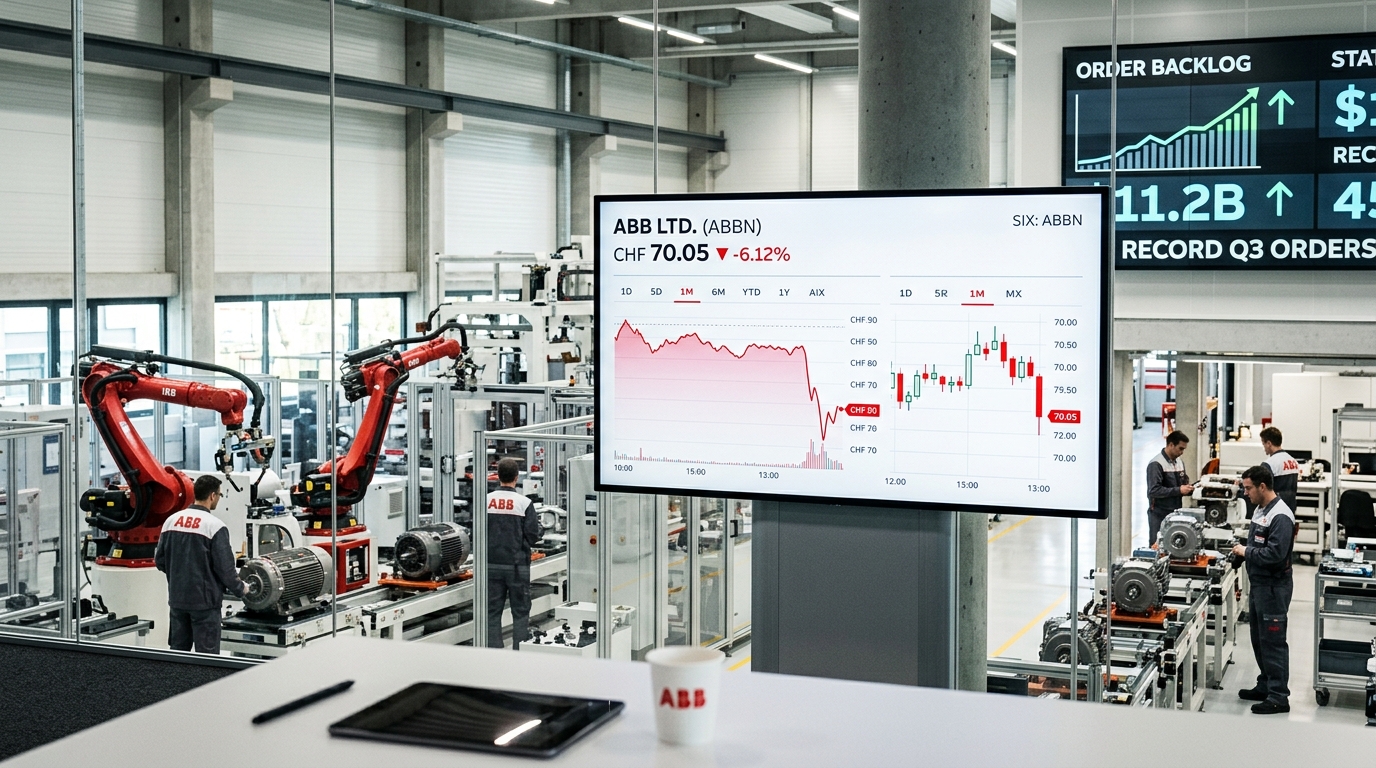
ABB shares dropped as much as 6% to trade near CHF 70 after the company’s Q3 2026 results landed before the European open. That price action sits in jarring contrast to the operating story underneath it. Orders surged 40% to a record $12.06 billion, driven by data-centre demand that roughly tripled year over year. This is not a company losing ground. It is a company whose hedging calendar cost it a quarter’s worth of credibility.
Company Profile
ABB is a Zurich-based electrification and industrial automation group serving energy, data infrastructure, and manufacturing markets globally. Its Electrification division, the segment at the centre of the AI infrastructure cycle, sells power distribution, protection, and cooling solutions. The demand sits in the power layer of the data centre: power distribution and cooling systems, with ABB’s own milestone this quarter being a direct current portfolio for AI data-centre customers.
The scale of that demand is being locked in at the utility level, not just the equipment level. Google’s 20-year nuclear power agreement with Constellation Energy shows hyperscalers are committing to multi-decade power contracts, the same structural demand underpinning ABB’s record order intake.
The Numbers
- Revenue: $9.70 billion, up 14% year over year, slightly below the $9.74 billion consensus.
- Basic EPS: $0.65, versus $0.66 a year earlier and well below the $0.79 consensus.
- Operational EBITA: $2.03 billion, up 24%, beating the $2.0 billion consensus; margin of 20.8% against 20.5% expected.
- Book-to-bill: 1.24, with the order backlog growing 35% to $32.26 billion.
- Operating cash flow: $1.86 billion, up 5%; free cash flow of $1.58 billion, up 2%.
- Electrification orders: up 70% to $7.67 billion, led by triple-digit data-centre growth. Americas orders rose 71%, with the United States up 82%.
Why the Stock Is Moving
A roughly $115 million non-cash charge from the revaluation of a deal-contingent currency hedge tied to the ongoing Rotork acquisition was the key drag on reported net income, pulling basic EPS to $0.65 against the $0.79 consensus. Operating profit beat. Cash flow held firm. The market saw the headline EPS miss and sold first.
A guidance upgrade perceived as incremental, combined with a weak European market backdrop, overwhelmed the undeniably strong order data. Full-year guidance was narrowed to comparable revenue growth in the “low teens” with reported Operational EBITA margin up at least 270 basis points year on year, tightening from the prior “low double-digit to low-teens” range. Markets read that as a ceiling, not a floor.
Not the Same Old List of Top Stocks
Lately every top stock list has started looking the same.
And while there’s nothing wrong with Nvidia, Tesla or SpaceX…
We believe there are many other top-quality opportunities out there for investors who dig into the details.
That’s why our MarketBeat analysts took a deep dive into the numbers and came up with an all-new list of the 5 Best Stocks to Buy Now.
Macro Context
ABB competes directly with Schneider Electric, Eaton, and Vertiv for power infrastructure spend from hyperscalers. All four are riding the same AI-driven capex cycle, and the debate across the sector is whether data-centre orders represent durable, multi-year demand or a front-loaded build that peaks in 2027. CEO Morten Wierod answered that directly on the call: order intake reached a record $12 billion, nudging up sequentially, a stronger outcome than the historical pattern of seasonal decline. ABB is meeting the orders with steady spending rather than a capex jump, with the chief executive stating capex trends at around $1 billion and is not expected to rise further in the mid-term. That is a clean margin story if demand holds.
The competitive read-through extends beyond quarterly results. Schneider Electric’s largest acquisition in its history triggered a similar single-session selloff, raising questions about how the market prices industrial scale-up moves.
The Mitsubishi Electric Deal
ABB is establishing a joint venture with Mitsubishi Electric for low-voltage products in the Asia-Pacific region, acquiring a 51% majority stake for approximately $495 million. The transaction, expected to close in the second half of 2027, values the combined businesses at approximately $890 million, with ABB targeting an operational EBITA margin of at least 20% within five years. The move addresses ABB’s weak position in Japan while improving access to growth markets across Asia-Pacific. ABB expects the joint venture to be accretive to EPS after the first year.
Forward Scenarios
Bull: The $115 million Rotork hedge is one-time and non-recurring. The 1.24 book-to-bill and a $32 billion backlog translate into 2027 revenue well ahead of consensus. Margin expands as volume scales, the Mitsubishi venture adds low-voltage share in Japan, and EPS revisions turn positive. ABBN reclaims CHF 85+.
Base: Operational momentum continues at a mid-teens revenue growth rate. Rotork completes without further hedge noise. The Mitsubishi joint venture closes in H2 2027 on schedule. Shares stabilise in the CHF 74–80 range as investors look past today’s EPS miss and focus on backlog conversion.
Bear: Hyperscaler capex slows into 2027 as AI infrastructure buildouts plateau, eroding order growth. Revenue misses against the “low teens” guidance band. Rotork integration costs and further hedging charges pressure reported earnings. ABBN tests the CHF 65–68 support zone.
Technical Overlay
Shares are now well below the 52-week high of CHF 89.14 and closer to the lower end of their recent trading range after today’s move. The CHF 70 level is the first area of interest, having marked prior consolidation. Below that, CHF 65–68 is the next structural zone. A recovery above CHF 78–80 would confirm the gap is being filled and that the EPS miss has been digested.
The durability of ABB’s backlog ultimately depends on whether hyperscaler capex commitments hold. AWS expanding margins while absorbing the largest infrastructure buildout in Amazon’s history suggests the spending cycle is not deteriorating.
What Investors Should Watch
- Backlog conversion rate: whether the $32 billion backlog translates into Q4 revenue in line with “broadly similar” guidance
- Rotork acquisition close date and any additional hedge revaluations
- Mitsubishi joint venture regulatory progress toward the H2 2027 close
- Competitor results from Schneider Electric and Eaton for corroboration on data-centre demand durability
- CEO commentary on whether U.S. data-centre order momentum (up 82% in Q3) holds through Q4
Is This Elon Musk’s Next IPO?
After taking SpaceX public in the biggest IPO ever, Elon Musk is already working with a NEW startup that’s growing faster than Tesla…
Faster than SpaceX… And faster than any of Elon Musk’s previous ventures.
Bloomberg has just confirmed that this startup is moving towards “a blockbuster IPO.”
Click here to get the name completely free of charge
And Jeff Brown will also show you how to claim a pre-IPO stake for as little as $50.
Bottom Line
The $0.14 EPS miss that drove today’s selloff was not an operating failure. Net finance expense included about $115 million from a non-cash revaluation of a deal-contingent currency hedge tied to the Rotork acquisition. Strip that out and the quarter was solid across every dimension that matters to the long run: orders, margins, cash, and backlog. What actually determines the next move is not whether ABB can win data-centre contracts. It clearly can. The question is whether the Rotork integration proceeds cleanly and whether the $32 billion backlog converts at the pace the guidance implies. Investors who sell the EPS line without reading the cash flow statement are making a different kind of mistake.