October 30, 2026
Bonus Content: Coinbase Earned $2.51 a Share. The Stock Fell Anyway.
Dear Reader,
After so many years in Washington, I thought I was immune to being shocked by what our government could do.
But the actions taking place in D.C. right now have gone FAR beyond anything I could have imagined.
And if you’re not careful, YOU could pay the price.
You’re already seeing it at the grocery story… and when you pump gas…
However, this is all just a foreshadowing of an even greater crisis.
Most Americans will be completely blindsided by what’s about to happen.
So please make sure you, your family, and anyone you care about are prepared.
I explain what I believe is coming… and the #1 first step every American should take to prepare right now – in this new short interview.
You can watch the full thing right here.
Sincerely,
Dr. Ron Paul
Contributor, Stansberry Research
Former Congressman & U.S. Presidential Candidate
Coinbase Earned $2.51 a Share. The Stock Fell Anyway.
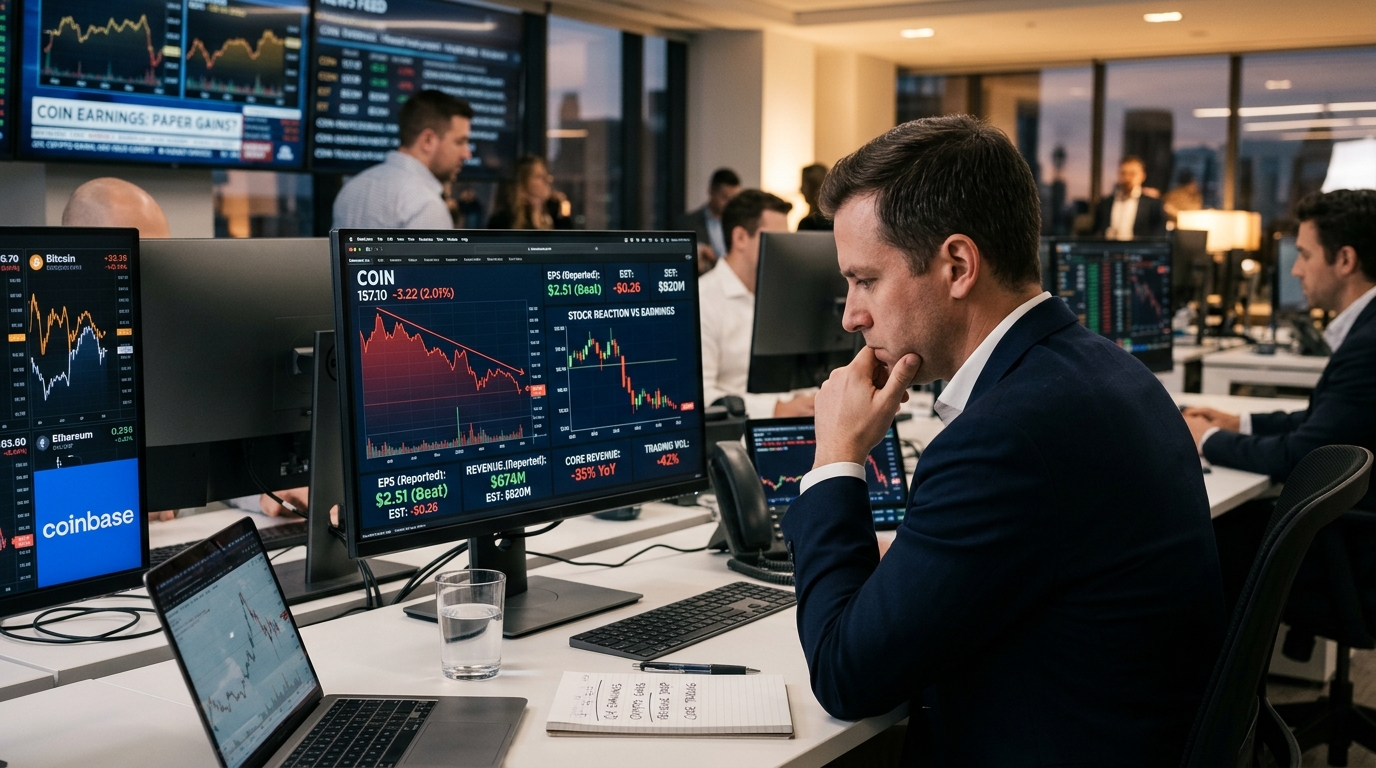
Coinbase posted earnings per share of $2.51 against a consensus forecast of a loss of $0.26 on Thursday. That is a beat of more than 1,000% on a percentage basis. The stock still slipped roughly 2% in after-hours trading to around $157, and the reason is sitting right in the income statement.
The headline profit was almost entirely a mark-to-market event. $715 million of the $718.7 million in net income came from unrealized gains on crypto assets held for investment, not from running an exchange. Strip that out and adjusted net income falls to $77.7 million. The EPS number is real under GAAP; it just does not describe what the operating business delivered.
The Numbers
- Net revenue: $1.16 billion, down 35% from $1.87 billion a year earlier
- EPS: $2.51 (GAAP diluted); consensus was a loss of $0.26
- Transaction revenue: $590 million, down 44% year over year
- Consumer transaction revenue: $450 million, roughly flat quarter over quarter, but consumer spot trading volume fell 59% year over year
- Subscription and services revenue: $570 million, 49% of net revenue
- Adjusted EBITDA: $332.9 million, the 15th consecutive positive quarter
- Prediction markets: crossed $200 million in annualized run-rate revenue, launched only in February 2026
- Coinbase One subscribers: record high, up 24% year over year
- Average USDC held in Coinbase products: record $22 billion, up 49% year over year
Why the Stock Moved Down, Not Up
For an exchange, revenue is the operating pulse. Coinbase’s fell about a third year over year, driven by multi-year lows in crypto volatility. When traders are not active, the transaction line collapses, and no amount of GAAP accounting can obscure that from a market that has watched three straight revenue misses. The stock was already down roughly 29% in 2026 through Thursday’s close.
The prediction-markets line is the one genuine growth story in the filing. Launched eight months ago and already past $200 million annualized, with 82% compound quarterly growth and more than 60% growth in daily traders, it is structurally different from spot trading: it generates fees regardless of bitcoin’s direction. CFO Alesia Haas said on the call that prediction-market growth offset the sequential decline in spot trading volume, holding total revenue flat quarter over quarter. That matters, but $200 million annualized against a $1.16 billion revenue base is still a cushion, not a replacement.
Prediction markets are reshaping valuations across the crypto-adjacent space. Robinhood’s event-contracts revenue surged more than tenfold year over year, giving it a diversification story Coinbase is still building toward.
The filing also disclosed that CEO Brian Armstrong, co-founder Fred Ehrsam, and President Emilie Choi have established Rule 10b5-1 plans to sell up to 13.6 million shares collectively, valued at approximately $2.2 billion at the October 29 closing price. Armstrong’s plan alone covers up to 8.17 million shares between November 16, 2026 and October 22, 2027, more than double the 3.75 million shares his plan covered a year ago. Sales under these plans are conditional on price thresholds and have not yet begun; Coinbase retains about $2.0 billion in buyback authorization that could absorb some of the supply. But the scale of the plans, disclosed the same night as earnings, will not go unnoticed.
Macro Context: Bitcoin at $78,000 and Falling
Strategy’s Q3 numbers are a more extreme version of the same problem. The company reported a record $20.91 billion gain on its 848,517 bitcoin holdings and $44.75 in diluted EPS for the quarter ended September 30, with bitcoin having risen 43% during that period. Those figures were marked as of October 25. Since then, bitcoin dropped to a low near $76,000 overnight after Binance disclosed a breach affecting an estimated $6.3 billion in assets, triggering about $1.5 billion in leveraged liquidations across crypto markets. The bitcoin that drove Strategy’s record quarter is worth meaningfully less this morning.
For Coinbase, lower bitcoin prices reduce user activity and compress the transaction revenue line further. The Binance hack also introduces a sector-confidence variable that weighs most directly on consumer trading volumes, the precise metric already down 59% year over year.
Forward Scenarios
Bull: Crypto volatility recovers, spot trading volume rebounds, and prediction markets scale to a $400-500 million annualized rate by mid-2027, rerating the stock on diversified revenue. Insider sell plans expire without heavy execution if the stock stays below thresholds.
Base: Volatility stays muted into year-end. Transaction revenue remains around $590 million per quarter. Subscription and services hold near 49% of revenue. The stock trades in a range tied to bitcoin sentiment, with the Binance hack a near-term overhang.
Bear: The Binance breach deepens regulatory scrutiny across the sector, consumer activity contracts further, and the insider selling plans execute at scale as the stock drifts lower. Revenue misses a fourth consecutive quarter.
Bottom Line
The $2.51 EPS number will age about as well as bitcoin’s October 25 price. What actually determines Coinbase’s next move is whether spot trading volumes recover and whether prediction markets can grow fast enough to replace what the core business is losing. Right now, neither is happening quickly enough to justify a rally on a quarter where the operating business delivered $78 million in adjusted net income on $1.16 billion of revenue. The real question for COIN is not what it earned last quarter. It is what it earns when the paper gains are not there to fill the gap.