Micron Technology delivered the kind of earnings report that gets framed on a wall. Then the stock fell.
Analyst Targets (selected, pre-earnings)
- UBS: Buy, $1,625 target
- Goldman Sachs: Neutral rating, with a price target below the Street median
- Median analyst target: approximately $1,530, implying roughly 44% upside from Wednesday’s close
The Numbers
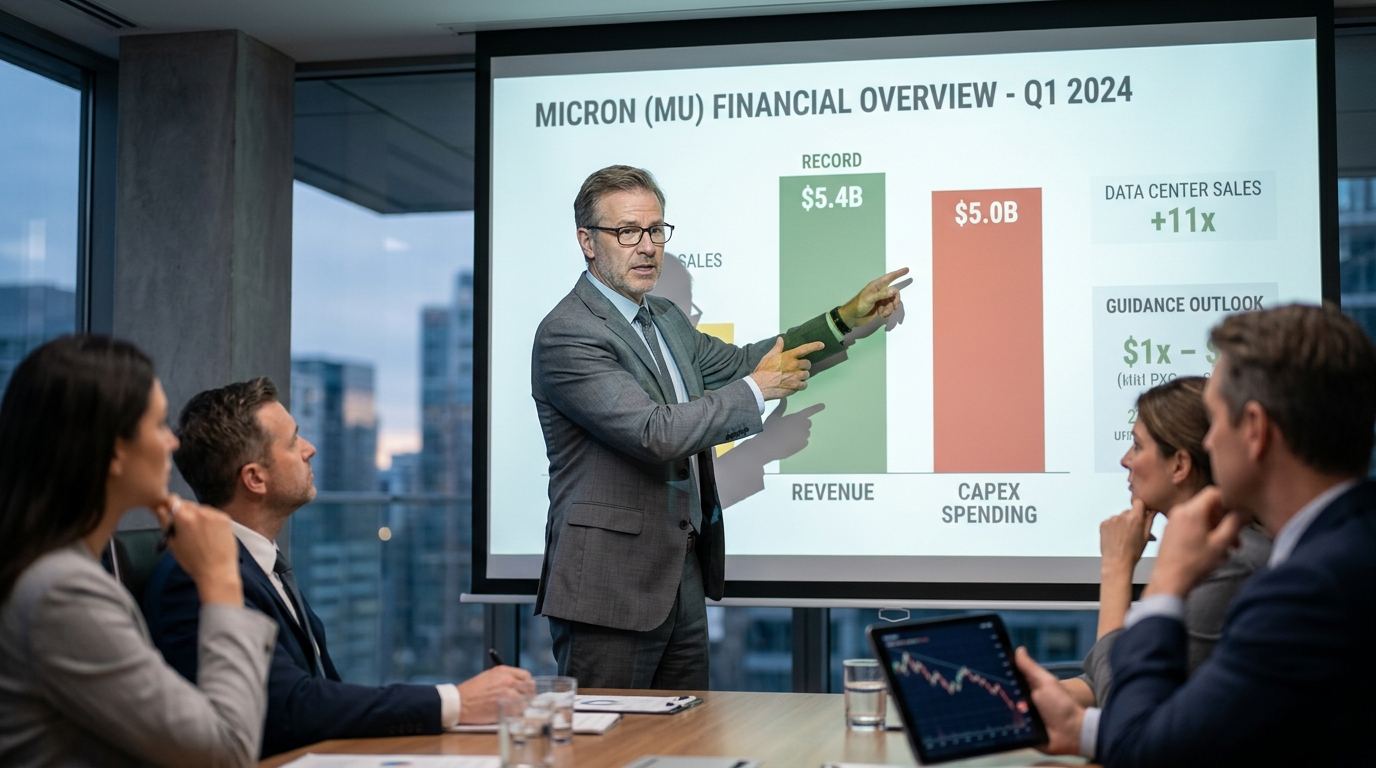
Micron posted adjusted earnings of $33.42 a share and revenue of $54.23 billion.
Quarterly revenue rose 31% sequentially and 379% from a year earlier, with operating income reaching $44.6 billion and an operating margin of 82.3%.
Non-GAAP gross margin came in at 87.0%, up 210 basis points sequentially. For the full fiscal year, revenue reached a record $133.19 billion, up 256% from a year earlier, while diluted earnings per share rose 811% to $75.52.
In data center SSDs, the company said revenue reached $10 billion in fiscal Q4, representing more than 6 times the year-ago quarter and about two-thirds of total company NAND revenue.
Why the Stock Fell Anyway
The guidance was not the problem. Micron guided Q1 revenue to $61.5 billion and diluted earnings per share to $38.15, with gross margin expected to ease sequentially to 86.25%.
The problem was what comes after the revenue line.
Micron reported net capital expenditures of $10.77 billion for the fourth quarter and $27.37 billion for the entire fiscal year. Then management signaled the acceleration is not over. On the earnings call, management said it expects capex of around $11.5 billion in Q1 of fiscal 2027 and about $25 billion for the first half of the fiscal year. The company also said capex is expected to rise further in the second half of fiscal 2027, with construction capex growing meaningfully faster than equipment capex. That points to a fiscal 2027 capex run-rate that could exceed $50 billion.
Management said a majority of the increase is for construction capex, most of which is to help accelerate clean room space availability in late calendar 2028 and beyond. That is a multi-year lag between dollar out and wafer in. Investors immediately discounted for it.
Macro and Competitive Context
The AI infrastructure buildout has tightened memory markets, with Micron describing supply-demand conditions as tight through fiscal 2027 and 2028. The company also said HBM revenue grew faster than total company revenue in the quarter, with agreements in place for the vast majority of calendar 2027 HBM bit supply at higher year-over-year prices.
Micron sits in the middle of a three-player oligopoly alongside Samsung and SK Hynix. The company expects tighter memory and storage supply-demand conditions due to growing AI applications across various platforms through fiscal 2027 and 2028. That supply discipline is the core bull argument. The bear argument is that Samsung and SK Hynix are not standing still.
Bull / Base / Bear
Bull: HBM agreements lock in pricing through 2027. Tight supply persists into 2028. The forward P/E near 7x treats a structurally higher-margin Micron as a commodity cyclical, creating a significant rerating opportunity as earnings compound.
Base: Revenue continues to grow at a decelerating rate through fiscal 2027. Capex weighs on free cash flow but does not crater it. Full-year adjusted free cash flow came in at $62.31 billion in FY26, and that cushion absorbs some of the FY27 spending without forcing a balance sheet event.
Bear: Past episodes where Micron, Samsung, and SK Hynix all expanded simultaneously have tended to sow the next downturn roughly two to three years out, as new wafer capacity converts today’s tightness into oversupply. A $50-billion-plus capex year before new clean rooms are operational is the classic setup for margin compression when that capacity hits.
Technical Overlay
MU is trading near the top of its 52-week range and above its 200-day simple moving average. Shares closed the regular session at $1,067.20 before slipping in after-hours trading. The 52-week range spans $165.50 to $1,255.00, meaning the stock has already priced in an enormous amount of good news. Support around the $1,040 to $1,060 range is the first level to watch if selling extends into Thursday’s session.
Bottom Line
Micron’s numbers were not the debate last night. The debate was whether a company spending $50 billion-plus per year on construction capex, with the first new clean rooms coming online in late 2028, deserves to trade at a premium multiple today. Management is betting on demand visibility through the end of the decade. The market, for now, is discounting for the years in between. What resolves that tension is not next quarter’s revenue. It is whether HBM pricing holds when Samsung and SK Hynix capacity arrives alongside Micron’s own.