October 5, 2026
Bonus Content: BT’s TalkTalk Deal Costs £400m. The Regulator Could Cost More.
Patriots’ Most Trusted Gold Company
Since 2000, Gold Is Up 1,395%. The S&P Is Up 425%.
For U.S. savers age 55+ with $50,000 or more in an IRA, 401(k) or savings. Free of charge, no obligation to buy anything.
Same twenty-six years. Same two dot-com and 2008 collapses. Two very different lines on the chart.1,2 Most Americans have never seen them put side by side – and almost nobody was told they are allowed to hold the better-performing one inside a retirement account.
Two lines on the same chart
In December 1999 gold traded near $290 an ounce and the S&P 500 closed the year at 1,469. Since then gold has multiplied roughly fifteen times over. The S&P has multiplied about five.1,2
Be fair about the comparison: that S&P figure is the price index and does not include reinvested dividends, which would lift it meaningfully.2 Even allowing for that, the gap over a quarter century is not a rounding error.
The reason has less to do with gold than with the dollar. Over those same twenty-six years the money supply expanded, two crises were met with emergency printing, and the national debt crossed $40 trillion. Gold did not get more valuable so much as dollars got less so – and gold is the one asset that cannot be issued by anybody.
Right now gold sits below its January 2026 peak while the world’s central banks keep adding more than a thousand tons a year, and published bank targets still run from roughly $4,900 to $6,300.3,4 Those are opinions, not promises. But a quiet stretch is a better time to read up than a panic. Get the free 2026 Gold IRA Guide.
The free 2026 Gold IRA Guide walks through exactly how a rollover from an IRA, 401(k) or TSP works, which metals the IRS allows, how insured depository storage works, and the mistakes that cost retirees the most. It is free and it takes about thirty seconds to request.
Claim Your Free 2026 Gold IRA Guide →
Rock legend Ted Nugent and former White House Press Secretary Sean Spicer are official endorsers and clients of Bishop Gold Group. 10 years in business ⢠5-star rated on Trustpilot and Google ⢠Mint Authorized Dealer
Prefer to speak to someone? U.S.–based specialists, no pressure, no jargon.
Mon-Fri ⢠7am-5pm PT
Sources
1 LBMA gold price, 31 December 1999 ($290.25/oz) to September 2026. Past performance is not a guarantee of future results.
2 S&P 500 price index, 1,469.25 close on 31 December 1999 to 7,707 in September 2026 – a price-only comparison that excludes reinvested dividends, which would raise the S&P figure materially.
3 Published year-end gold price forecasts as reported 2026: Goldman Sachs, J.P. Morgan, UBS and Bank of America, spanning roughly $4,900–$6,300/oz. Analyst forecasts are opinions, not guarantees.
4 World Gold Council, Gold Demand Trends, annual central bank net purchases 2022-2024.
Past performance is not a guarantee of future results. Precious metals are volatile and can decline in value. This comparison is historical and is not a prediction or a recommendation to buy or sell any asset.
BT’s TalkTalk Deal Costs £400m. The Regulator Could Cost More.
Analyst Targets
- Morgan Stanley: Had described BT’s FY27 cash flow targets as reiterated with “solid KPIs” ahead of today’s announcement
- Consensus (pre-deal): FY27 normalised free cash flow target of c.£2.0bn, EBITDA range of £8.2-8.3bn
What Happened This Morning
BT Group acquired TalkTalk Telecommunications Limited and PlatformX Communications Limited out of the administration of TalkTalk Group on a debt-free basis, announcing the deal at 07:11 London time on October 5.
The acquisition was needed, BT said, to protect continuity of service for around 2.5 million customers, including vulnerable households and organisations supporting health, emergency services, defence, education and government.
BT reaffirmed its FY27 and multi-year financial outlook metrics, excluding the effects of this transaction. That carve-out is doing a lot of work.
The Business BT Just Bought
During the last 12 months, TalkTalk generated revenues of c.£1.2bn and was loss-making.
TalkTalk said its residential customer numbers had declined from about 4.3 million in FY19 to around 1.5 million today.
Its wholesale division PXC has around one million customers, including thousands of vulnerable customers as well as hospitals, doctors’ surgeries and other areas of critical national infrastructure.
After a prolonged but ultimately unsuccessful sale process for TalkTalk’s consumer and wholesale operations, BT said it recognised the risk to the country should the company collapse.
Reports have said TalkTalk was left in dire straits after BT rejected a proposal from private equity firm Epiris relating to PXC, and that Epiris had asked BT to forego repayment of at least £300m owed to Openreach.
The Numbers
The estimate of the total cash impact of the acquisition in FY27 is c.£400m, comprising consideration, transaction and administration costs, working capital impacts, a trading loss for the balance of the fiscal year of c.£60m, and non-receipt of c.£100m otherwise due to Openreach.
Against BT’s standalone FY27 normalised free cash flow target of c.£2.0bn, that target was set alongside revenue guidance of £19.0-19.5bn and EBITDA of £8.2-8.3bn. The £400m cash drag does not appear within those metrics because BT has ringfenced it. BT plans to report the acquired operations as a separate business segment. Investors should read the guidance accordingly: the core business numbers remain intact on paper; a £400m cash call sits alongside them.
Why the Regulatory Outcome Is the Real Variable
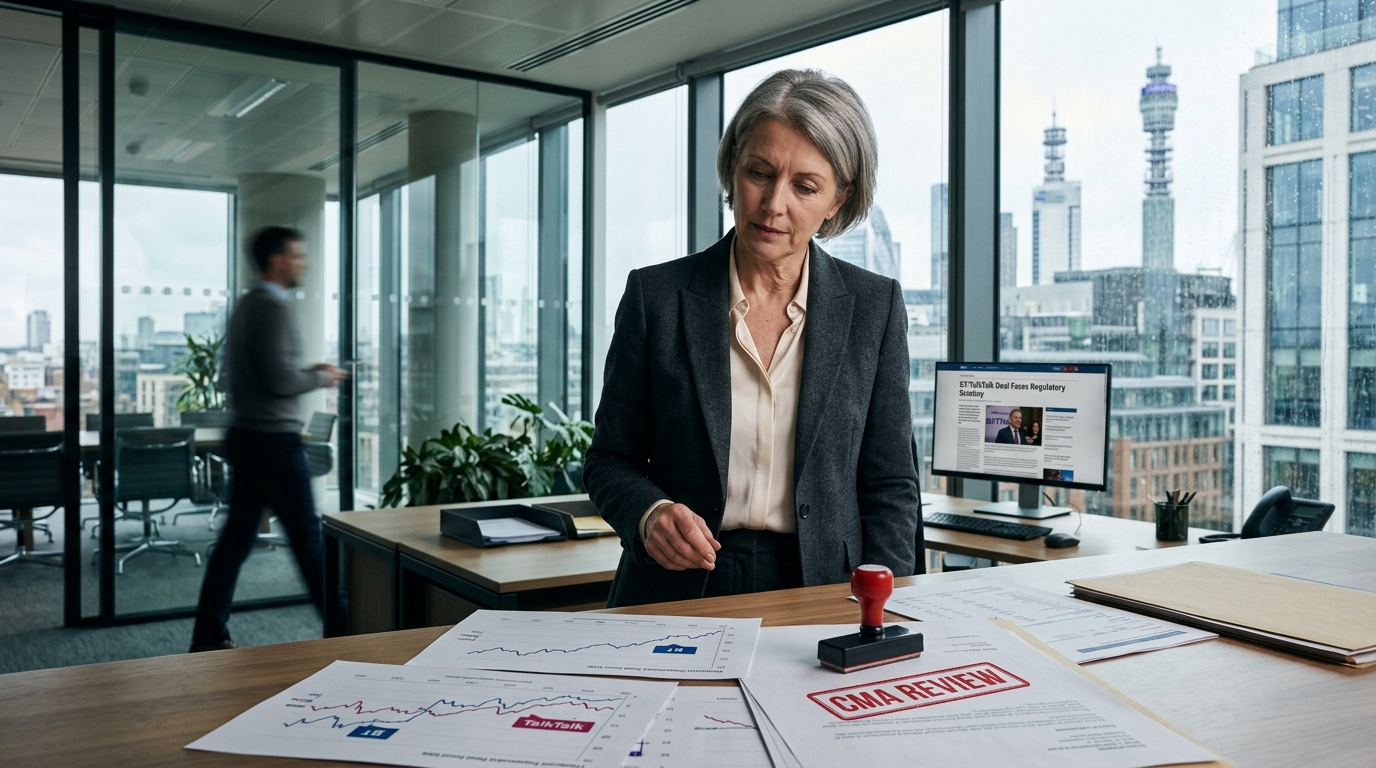
The government has intervened, with Lisa Nandy, the Secretary of State for Digital, Culture, Media and Sport, issuing a Public Interest Intervention Notice and telling the Competition and Markets Authority to report back to her by 19 October 2026.
The notice, issued under section 42 of the Enterprise Act 2002, will allow the secretary of state to consider the wider public interest once the CMA has reported on competition concerns.
The transaction remains subject to regulatory review, and BT and the acquired businesses will continue to operate separately and compete with each other until that process has concluded. The timing matters. A deal of this kind would give BT an estimated 36% share of the broadband market and would face regulatory scrutiny over competition concerns.
The Ofcom backdrop is already charged. Just last week, Ofcom directed Openreach to withdraw its “Incremental New to Openreach” offer, which would have given internet service providers a monthly discount of up to £9.50 per customer for up to 30 months. Ofcom said it was the first time it had stepped in to block a commercial offer from Openreach. A regulator willing to act that decisively on pricing will scrutinise the Openreach owner absorbing its largest retail customer with care.
Bull / Base / Bear
Bull: The CMA clears the deal on public interest grounds given the administration context. BT absorbs TalkTalk’s 2.5 million customers into its Plusnet and EE brands, capturing synergies that exceed the £60m trading loss drag. The £400m cash cost proves a one-time item against a rising free cash flow trajectory toward £3bn by FY30.
Base: BT expects the acquisition to become value accretive over time through integration and synergies, but the CMA imposes structural conditions, potentially requiring customer or asset disposals. The integration takes longer than signalled. FY27 free cash flow comes in near the £2bn target on the standalone basis, but investor focus shifts to when the acquired segment stops bleeding.
Bear: The CMA demands remedies that remove the strategic rationale. BT is left holding a loss-making £1.2bn revenue business with no clean path to profitability, all while servicing a £400m FY27 cash cost alongside net debt already at c.£19.8bn.
Technical Overlay
BT.L had been trading near 179p ahead of this announcement. The stock’s recovery from multi-year lows reflected investor confidence in the fibre-build cash flow inflection story. An unresolved regulatory position lasting into late October introduces headline risk that could suppress any re-rating until the CMA reports.
What Investors Should Watch
- CMA report to the Secretary of State by 19 October 2026: any structural remedy language will be the key read-through
- Ofcom’s posture on Openreach market power, given last week’s discount intervention
- First disclosure of the TalkTalk segment results, where the trading loss trajectory will define the accretion timeline
- Whether BT’s BBB+/Baa1 credit rating commitment holds given the additional cash outflow
Bottom Line
BT framed this as a public service rescue, and the administration context gives the argument genuine weight. The group maintained its commitment to a BBB+/Baa1 credit rating and said its existing FY27 and multi-year financial outlook remains unchanged, excluding the effects of the acquisition. But the exclusion qualifier is where the debate lives. The £400m is real cash. The trading loss is real. And the regulator now has until October 19 to decide whether BT, which already controls the UK’s dominant fixed-line infrastructure, should also own the country’s fourth-largest retail broadband provider. That answer shapes everything that follows.