October 5, 2026
Bonus Content: Samsung’s Q3 Numbers Land Thursday. What 276,000 Won Still Needs Proving.
Washington just sent a clear message to the drone industry.
America intends to build more of these systems at home.
A new Executive Order aims to prioritize American made drones, strengthen domestic supply chains, speed up approvals and expand military adoption.
It also encourages the government to help American drone companies compete overseas.
That is how policy can become opportunity.
When Washington starts removing barriers and directing demand toward a strategic industry, government contracts, private capital and Wall Street attention follow.
One overlooked Nasdaq company is already positioned.
Spending more than 25 years building the kind of drone technology Washington now wants America to produce.
As this new policy pulls more demand toward domestic manufacturers, this quiet company may find itself directly in the path of this buildout.
Follow Washington’s drone push to this overlooked Nasdaq name…
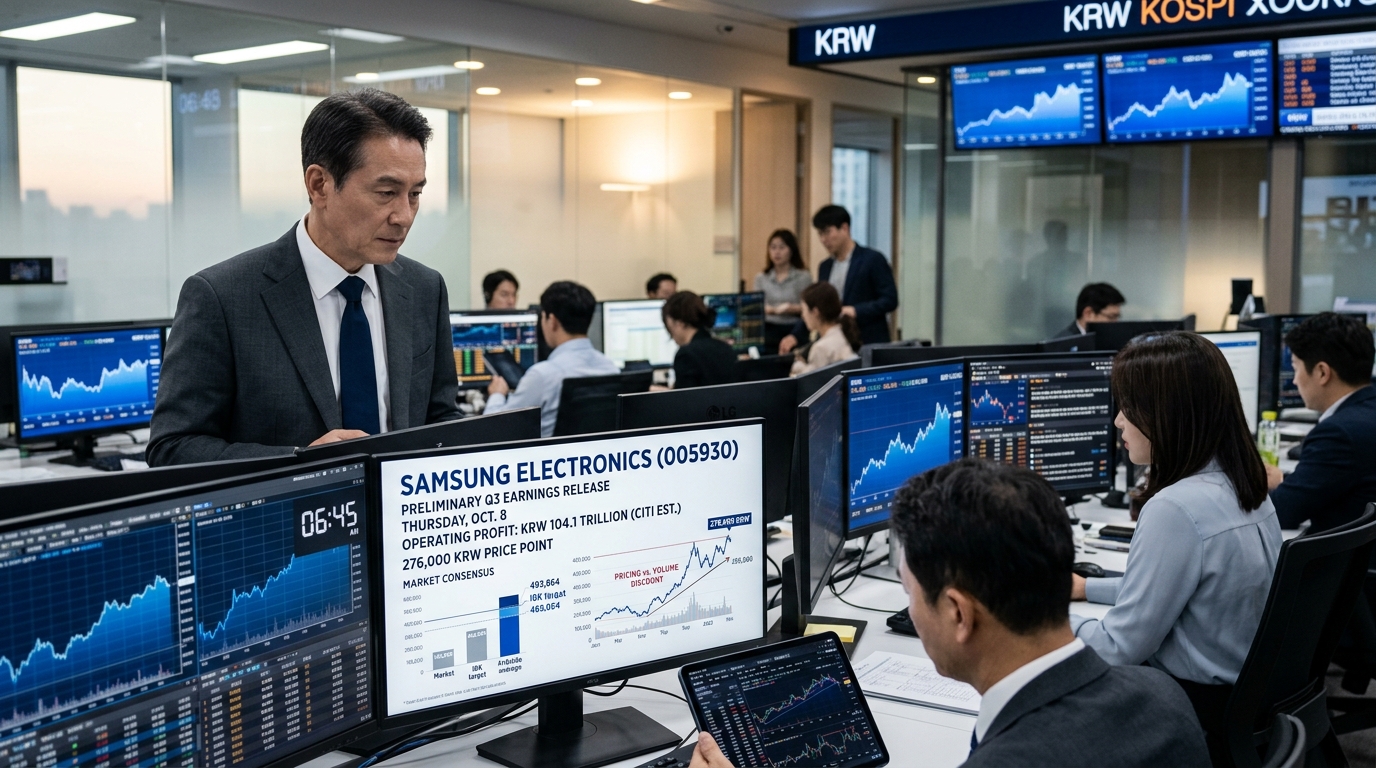
Samsung’s Q3 Numbers Land Thursday. What 276,000 Won Still Needs Proving.
Analyst Targets
- IBK Investment & Securities: Buy, KRW 460,000 target (as of October 3, 2026)
- FnGuide average (domestic brokers, late September): KRW 493,864 12-month consensus target
- Citi: Q3 operating profit estimate KRW 104.1 trillion (revised down from KRW 115.5 trillion in September)
The Number Everyone Is Waiting For
Samsung Electronics will release preliminary third-quarter results on October 8, with analysts expecting record revenue above 200 trillion won. Broker estimates cluster around KRW 104 trillion to KRW 111 trillion of operating profit, which would be the first time above KRW 100 trillion for the company. Korean markets were closed Monday for a National Foundation Day substitute holiday, delaying any immediate reaction until Tuesday’s open.
The bar is not modest. Q2 operating profit reached an all-time high of KRW 89.5 trillion. A result at the midpoint of the broker range would represent roughly an 18% sequential gain on a base that was itself a record. Should those estimates materialize, cumulative operating profit through the third quarter could surpass 250 trillion won.
Company Profile
Samsung Electronics (005930.KS / SSNLF) is the world’s largest memory chip maker by volume. The semiconductor Device Solutions division carries the earnings story. Consumer electronics and displays matter at the margin, but memory price cycles set the quarterly result.
The Numbers: What Brokers Are Modeling
- Q3 operating profit range: KRW 104–111 trillion (broker consensus)
- FnGuide one-month consensus: KRW 106 trillion (rounded)
- Q3 revenue estimate: KRW 200 trillion (rounded, per domestic consensus reports)
- IBK individual forecast: KRW 101.7 trillion operating profit, KRW 195.2 trillion revenue
- Q2 actual operating profit: KRW 89.5 trillion; revenue KRW 171.5 trillion
- IBK projected operating margin: about 52%
The stronger won and performance-bonus provisions are identified as factors that could limit the quarterly margin. Those two items explain much of the distance between the top of the broker range and what the memory price trajectory alone would otherwise imply.
Where the Profit Comes From
The driver is DRAM pricing, and the sequence has been relentless. Samsung was negotiating aggressively with customers to raise its third-quarter DRAM average selling price by as much as 20% from the previous quarter. TrendForce, however, forecast that DRAM contract price gains would narrow to 13–18% quarter-over-quarter in Q3, while NAND flash prices were expected to rise 10–15%.
That gap, between Samsung’s ask and what customers actually absorbed, is the key variable inside Thursday’s number. Volume growth partially compensates, but it is the ASP line that separates a KRW 106 trillion result from a KRW 111 trillion one.
Currency: The Quiet Offset
The USD/KRW exchange rate was around the mid-1,300s in late September, and the won has strengthened over the past 12 months. Samsung reports in won but prices much of its memory in dollars. A structurally firmer won converts each dollar of semiconductor revenue into fewer won, compressing reported profit relative to what chip prices alone would suggest. It does not change the underlying demand story, but it does change the headline number.
Macro and Industry Context
If Samsung beats market expectations, following Micron Technology’s results released on October 1, optimism about the semiconductor cycle could fuel gains in Korean stocks. Samsung and SK Hynix together account for roughly half of KOSPI market capitalisation, so the Q3 preliminary release is as much a KOSPI event as a single-stock one.
Bull / Base / Bear Scenarios
Bull
Operating profit reaches KRW 109–111 trillion, implying DRAM ASP increases landed at the higher end of TrendForce’s range and bonus provisions came in lighter than feared. Stock tests the KRW 300,000–310,000 zone and reopens the debate on the KRW 374,500 peak from earlier this year.
Base
Operating profit near KRW 104–106 trillion. Result confirms the supercycle is intact but margins are plateauing. Stock holds the KRW 270,000–280,000 range. Attention immediately shifts to Q4 guidance and HBM4 qualification progress with Nvidia.
Bear
Operating profit below KRW 100 trillion. Bonus provisions and currency headwinds overwhelm ASP gains; the 100 trillion threshold becomes a miss rather than a milestone. Stock revisits KRW 255,000–260,000 support. Cycle-peak fears, which already triggered a 10.7% single-session decline earlier in 2026, return to the conversation.
Technical Overlay
Samsung (005930) was trading at KRW 276,000 as of October 2, with a 52-week range of roughly KRW 89,000 to KRW 374,500. The stock has retraced roughly 26% from its peak. Short-term momentum indicators are mixed to negative, consistent with a market that has already heavily de-risked ahead of Thursday. A beat that clears KRW 107 trillion likely pushes the stock above the KRW 285,000 level that capped several recent intraday rallies.
What Investors Should Watch
- The ASP split: How much of the operating profit gain came from price versus volume. Price-led gains are more durable; volume-led gains can compress margins faster.
- HBM commentary: The preliminary release contains only two lines (revenue and operating profit). Full division detail comes with the later October release. Any informal guidance on HBM4 qualification will be the read-through for SK Hynix and Micron.
- Bonus provisions: If management signals that Q3 absorbed the bulk of annual compensation accruals, Q4 margins look cleaner.
- Won direction: Further won strength into Q4 is a headwind worth sizing.
Bottom Line
The KRW 100 trillion threshold is a milestone, but the market already knows Samsung may clear it. What Thursday’s preliminary release actually settles is narrower: whether ASP gains in the 13–18% range were enough to offset bonus accruals and won strength, or whether the consensus was too optimistic by 5–7 trillion won. IBK’s Buy rating and KRW 460,000 target rest on Q3 revenue of KRW 195.2 trillion and operating profit of KRW 101.7 trillion, representing increases of 13.8% and 13.6% from Q2. That target implies the stock at KRW 276,000 prices in a fraction of the cycle’s remaining upside. The number that changes that calculus is not the headline itself but the implied margin, and whether management signals that the won and bonus headwinds are largely absorbed or still building into year-end.