Analyst Targets
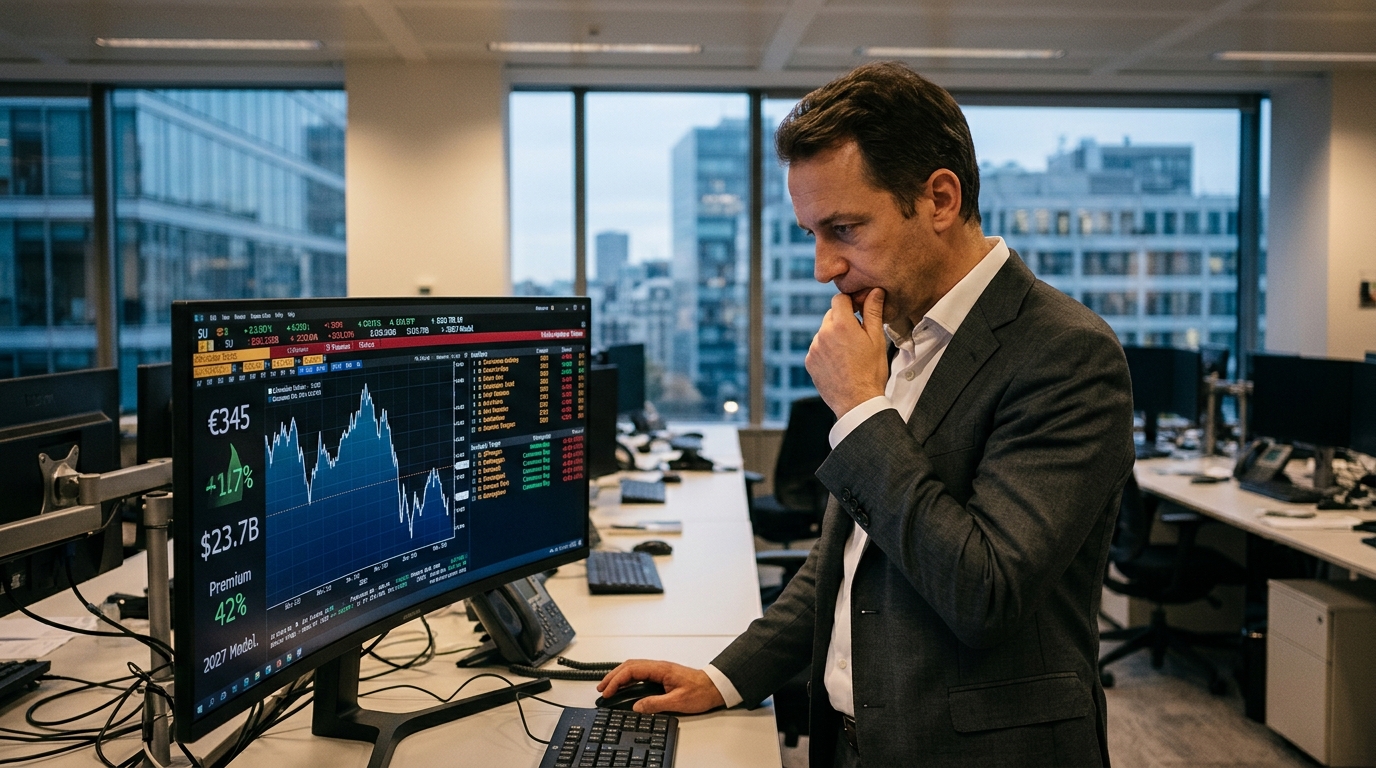
- JPMorgan: Overweight, €345 price target; reiterated this morning; acknowledged the deal represents roughly 12% of Schneider’s market capitalization, and called it accretive to sales and EBITDA over time.
- Consensus (24 analysts): Buy, mean price target €335, implying the stock was trading at a meaningful discount to fair value even before today’s 8%-plus sell-off.
What Happened This Morning
Schneider Electric stock is down about 8.4% today, trading near €278 from a previous close of €303, after the French industrial conglomerate confirmed it will acquire Boston-based engineering software developer PTC in an all-cash deal. PTC shareholders will receive $205 per share in cash, representing a 42.3% premium over the stock’s last closing price. The implied enterprise value is $23.7 billion, representing a multiple of 21x EV/Adj. EBITA 2027E.
This is Schneider’s largest acquisition in its history. The market did not celebrate.
Company Profile
Schneider Electric is a France-based global energy technology company that provides electrical, automation, and digital solutions for buildings, data centers, industries, infrastructure, and power grids, with offerings spanning electrical equipment, industrial automation systems, software, and digital services.
PTC is a global software company providing computer-aided design, product lifecycle management, application lifecycle management, and service lifecycle management software to manufacturers and engineering organizations. Its key products include Creo, Onshape, Windchill, ThingWorx, Vuforia, and Servigistics, serving customers across automotive, aerospace, industrial equipment, and medical devices. The company serves more than 30,000 customers and generated €2.4 billion of revenue in calendar 2025, with an adjusted EBITA margin of approximately 40%.
The Numbers That Matter
- Offer price: $205 per share, all cash
- Equity value: ~$22.6bn (€20.1bn)
- Enterprise value: $23.7bn (€21.1bn)
- Acquisition multiple: 21x EV/Adj. EBITA 2027E
- PTC 2025 revenue: €2.4bn at ~40% adjusted EBITA margin
- Expected PTC growth: ~10% annually through 2029
- Synergies: €250 million in annual cost synergies by year three; approximately €800 million in revenue synergies
Why Schneider’s Stock Is Falling
The market’s negative reaction centers on two concerns: the steep acquisition premium and the financing burden. The $205-per-share offer implies a valuation of roughly 21 times PTC’s 2027 adjusted EBITA, a multiple many investors view as stretched.
The company expects to fund the total cash consideration through a combination of €5 to €6 billion raised by issuing new shares and €16 to €17 billion raised through new debt. Buybacks are expected to pause in 2027 and 2028. The combination of share issuance and a substantially higher debt load creates immediate pressure on per-share earnings and moves Schneider’s balance sheet into territory that will take several years to normalize.
Schneider’s own guidance offers a partial offset. The company expects the transaction to be immediately low single-digit accretive to adjusted EPS (before PPA) in the first year of full consolidation and mid-to-high-single-digit accretive to adjusted EPS (before PPA) including full run-rate synergies. Bulls will hold those numbers. Bears will note what “before PPA” implies: purchase price accounting amortization will reduce reported earnings materially in the near term.
Macro and Industry Context
Schneider is stepping up its effort to tap into the artificial-intelligence boom with its biggest acquisition to date. The logic is coherent: energy management hardware alone does not command software multiples, and the race to build an end-to-end industrial AI stack has made pure-software assets expensive.
This acquisition builds on Schneider’s $3.1 billion all-cash agreement to acquire AI software provider Cognite, announced on June 30, 2026. Three weeks ago, Schneider announced plans to buy Shelly Group in an all-cash deal valued at approximately €1.2 billion. Three deals in four months raises legitimate questions about integration bandwidth alongside the leverage question already priced into the stock today.
Forward Scenarios
Bull
Synergies arrive ahead of schedule. PTC’s 10% annual revenue growth holds through 2029. Software and services reach 24% of group revenue, re-rating the combined entity toward peers like AVEVA’s acquisition multiple. Shares recover toward the €335 consensus within 12 months as the debt trajectory becomes clearer.
Base
Integration absorbs management attention through 2027. EPS dilution is real but bounded. The deal closes in Q3 2027 as guided. Shares trade in the €270 to €300 range until the first full-consolidation results confirm the accretion case.
Bear
Regulatory clearance in the U.S. or Europe proves slower than expected. New-share issuance via the accelerated bookbuild prices wider than anticipated, adding additional dilution. Cost synergies slip beyond year three. Leverage constrains future capital returns through 2029, and the stock drifts below €260.
Technical Overlay
Schneider’s shares traded near €278 by early morning against Friday’s €303 close, a drop of about 8%. The gap lower opens well below the 50-day and 200-day moving averages that had supported the stock through its strong year-to-date run. The €270 zone, a level not tested since mid-year, now becomes the first meaningful support. A close below that level on elevated volume would signal the market pricing in the bear scenario rather than a one-day overreaction.
What to Watch
- Accelerated bookbuild terms: The size and pricing of the €5 to €6bn equity raise will set the true dilution level. Watch for Schneider to launch this within days.
- Q3 revenue release, October 16: Schneider will bring forward its third-quarter revenue release to October 16 as a result of the transaction, giving investors an early read on underlying business momentum.
- Analyst target revisions: JPMorgan held at €345 this morning. Watch whether Deutsche Bank, Barclays, and UBS trim targets to reflect the new share count and leverage profile.
- Regulatory calendar: A cross-border deal of this size will require U.S. and EU antitrust review. Any signs of extended scrutiny push the Q3 2027 close target and extend the earnings-dilution window.
Bottom Line
The strategic case for combining Schneider’s energy and automation franchise with PTC’s CAD, PLM, and industrial IoT platform is not hard to make. The sharp sell-off reflects a classic acquirer’s discount dynamic: while the strategic logic is broadly acknowledged, the size of the premium paid, the scale of new equity issuance, and the leverage required to complete the transaction have overshadowed the long-term synergy case in the near term.
The question for investors is not whether Schneider overpaid on a multiple basis. At 21x 2027 adjusted EBITA, it did. The real question is whether the synergy math and PTC’s 10% annual growth trajectory are durable enough to justify carrying €16 to €17 billion in new debt for the better part of three years. The October 16 revenue release and the bookbuild terms, both arriving within two weeks, will be the first hard data points that answer it.