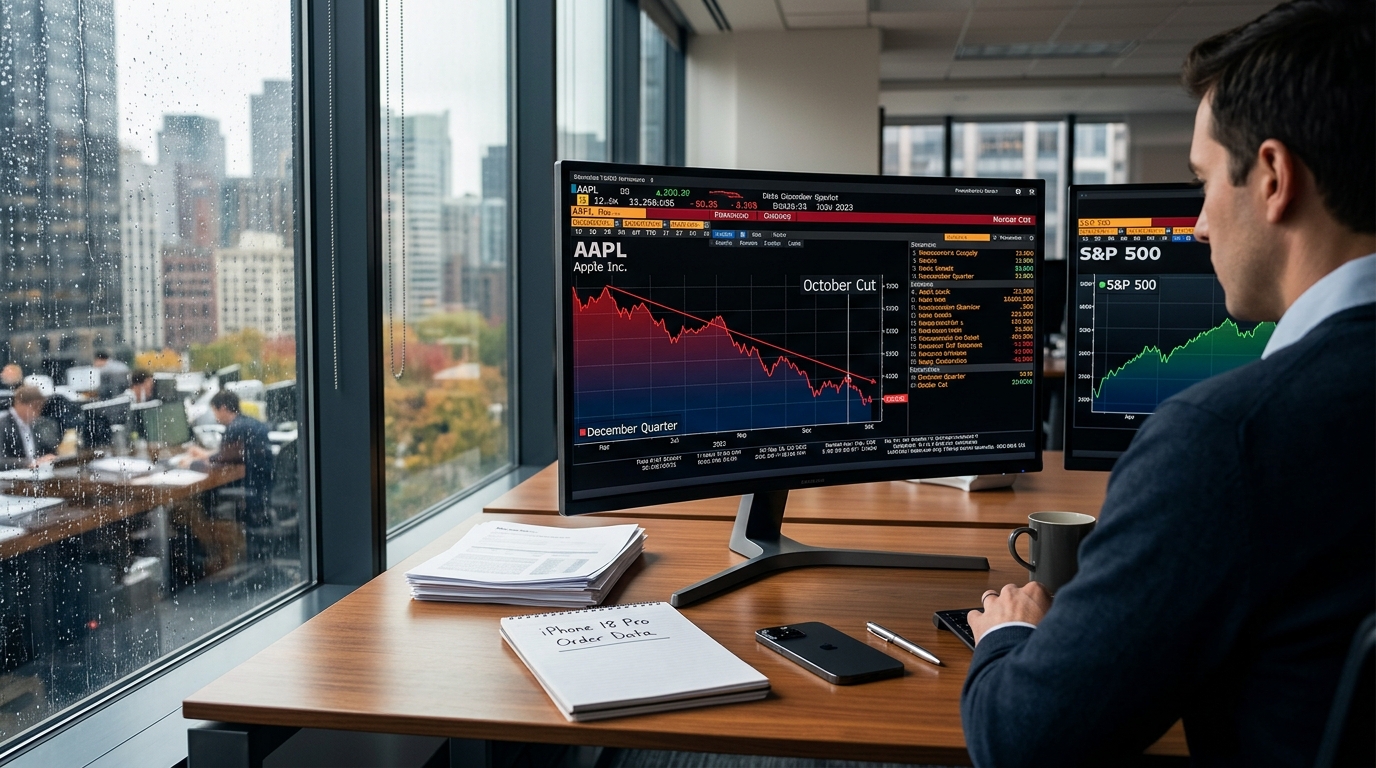
AAPL closed Friday down roughly 2.6% while the S&P 500 rose 0.6%. That divergence has a single explanation: Apple reportedly told some suppliers to cut production of components for its newly launched iPhone 18 Pro and Pro Max, with October orders reduced by 15–20% from what was originally expected. The Nikkei Asia report, citing executive-level supply chain sources, arrived before New York opened and never let the stock recover.
The iPhone 18 Pro and iPhone 18 Pro Max start at $1,199 and $1,299 respectively, which is $100 more than the models they replace. Nikkei Asia attributed the softer demand to the price increase and higher memory costs, as DRAM and NAND pricing has surged alongside artificial intelligence-related infrastructure demand.
The Cost Problem Behind the Cut
Apple’s iPhone 18 Pro costs nearly 40% more to build than its predecessor because of soaring memory prices, with TrendForce putting the bill of materials for the 256GB model roughly 38% above the equivalent iPhone 17 Pro. Memory now makes up about 34% of the iPhone 18 Pro’s component cost, up from about 10% a year ago. Memory has overtaken the application processor and display as the single largest cost component, a reversal from prior generations.
Contract prices for DRAM surged 90–95% quarter over quarter in the first quarter of 2026, according to TrendForce, while NAND flash contract prices rose 55–60% during the same period. The suppliers driving those prices, including Micron, Samsung, and SK hynix, are not relieving pressure anytime soon. SK Group leadership has warned the global memory chip shortage could persist into 2030.
What This Does to the December Quarter
Wall Street’s consensus for the December quarter currently sits at $154.39 billion in revenue, against a year-ago base of $143.76 billion. That implies roughly 7% growth into a holiday period where iPhone Pro models are the primary volume driver. A 15–20% October component reduction, if it persists into November fulfillment windows, puts real pressure on that number.
Apple guided for gross margin of 47.5–48.5% at its last earnings call. Products gross margin in the June quarter was 38.7%, down 200 basis points from the prior period. Apple’s playbook, per TrendForce, mirrors its recent MacBook launches: sacrifice part of gross margin to soften the retail price bump and defend shipment volume. The Nikkei data suggests that strategy is not working at $1,199.
Forward Scenarios
Bull: The order cuts affect some but not all suppliers in October due to differing production lead times, and it is not immediately clear whether Apple will make further adjustments from November onward. If November orders stabilize, the quarter’s total Pro shipments stay close to plan, and December demand, always the stronger month, absorbs the miss. Analysts note China’s iPhone 18 Pro series sales rose 12% year over year in its launch-week window, which provides a counter to the softness.
Base: October cuts translate to a 5–8% reduction in December-quarter iPhone Pro units versus prior consensus. Revenue comes in around $148–150 billion, short of the $154 billion estimate. Products margin holds at 37–38% as Apple absorbs memory costs rather than defend volume further. AAPL trades back toward its 50-day moving average near $320.
Bear: An executive-level source told Nikkei Asia that orders fell 15–20% for both premium models in October, adding that it remained unclear how demand would evolve in the coming months. If November orders reflect the same trajectory, the revenue shortfall widens. Products gross margin drops below 37%, forcing analysts to cut fiscal 2027 estimates. The stock, already up about 22% year to date, has limited cushion for sustained estimate cuts.
What to Watch in Supplier Numbers
The confirming signal will come from quarterly results at Micron, Foxconn, and TSMC over the next six weeks. Foxconn’s October revenue release is the first hard data point: a month-over-month decline in its consumer electronics segment beyond seasonal norms would validate the Nikkei order figures. UBS analysts flagged that delivery waiting times were shrinking across more than 30 markets, a separate demand signal pointing in the same direction as the supply chain report.
Bottom Line
The Nikkei report is not just an inventory story. It is early evidence that Apple’s price transmission of the memory cost shock may be hitting consumer resistance. The December quarter question is no longer whether iPhone 18 Pro demand is strong. It is whether a $100 price increase has permanently shifted enough buyers to the base model, a competing Android device, or no upgrade at all, and whether Apple chose to defend volume or margin. The answer will determine whether $154 billion is still the right number by the time Apple reports in late January.