October 21, 2026
A stunning preliminary update sent SMCI up more than 10%
Analyst Targets
- Rosenblatt (Sajal Dogra): Buy, $51 target, maintained Oct. 16
- Citigroup (Asiya Merchant): Neutral, $45 target, raised from $39 on Oct. 8
- Mizuho (Vijay Rakesh): Neutral, $43 target, raised from $35 on Oct. 6
- Goldman Sachs (Katherine Murphy): Sell, $34 target, raised from $30 on Aug. 12
Consensus among 18 analysts: Hold. Average target roughly $43, implying meaningful upside from Tuesday’s $32.47 close, before last night’s update changed the math entirely.
The Stocks That Pop 500% in Days
I’ve spent 25+ years hunting these tiny stocks. They always fire the same 3 signals first. Click here to grab the setup before the next Supernova pops 100%, 500%, or more.
The Update That Moved Markets
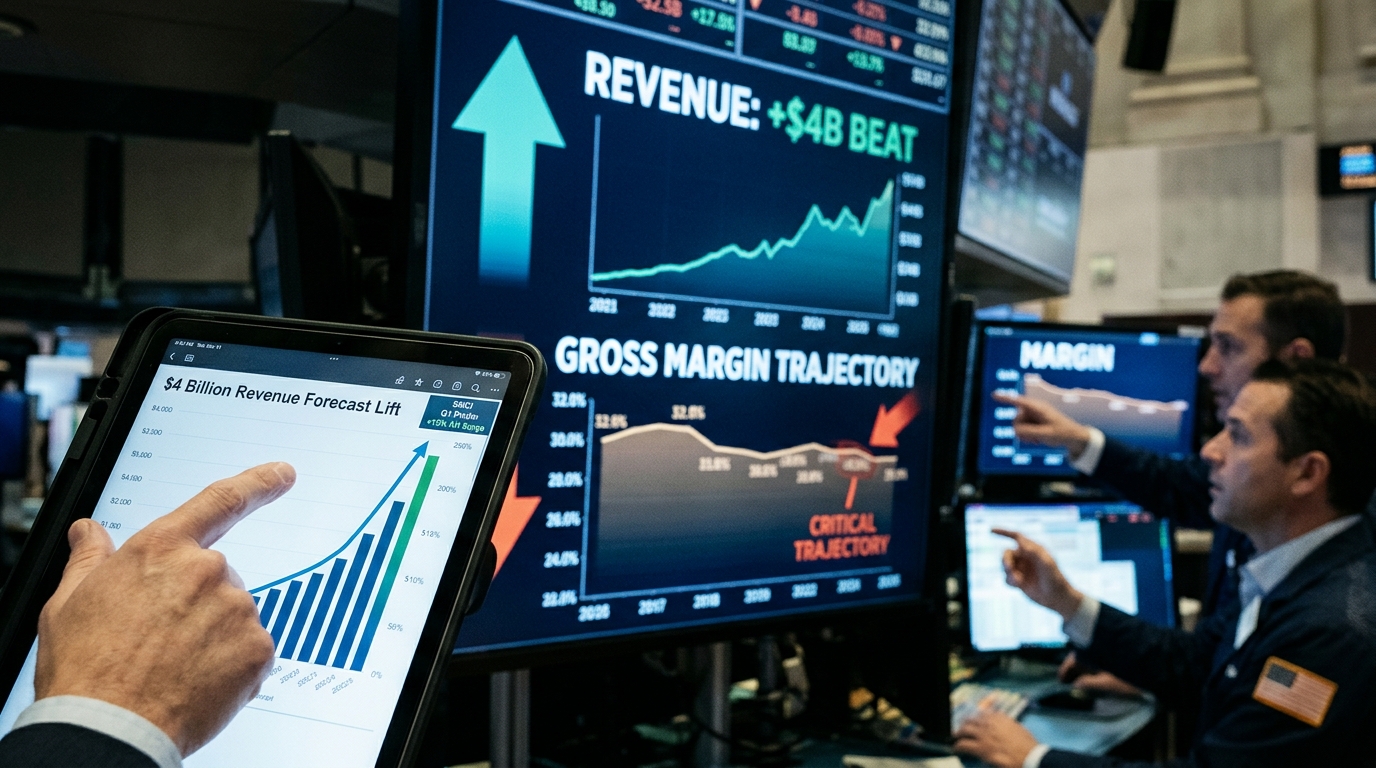
After the close on October 20, Super Micro Computer issued a preliminary business update for its fiscal first quarter of 2027, ended September 30, 2026, revising revenue guidance to a range of $18.5 billion to $19.5 billion, up from prior guidance of $14.5 billion to $15.5 billion, citing increased demand for AI platforms. That is a $4 billion lift at the midpoint in a single pre-announcement.
The company also raised its gross margin outlook to 12.0% to 12.5%, versus prior guidance of 10.4% to 10.8%, attributing the change primarily to customer and product mix. Shares jumped more than 10% in after-hours trading on the news.
Company Profile
Super Micro Computer operates in the technology sector within the hardware industry. The company designs and manufactures high-performance server and storage systems optimized for AI workloads, with a focus on direct liquid cooling and modular open-standard rack architecture. Management has said AI GPU-related platforms contribute more than 80% of revenue, making SMCI effectively a high-velocity delivery mechanism for Nvidia silicon into hyperscale data centers.
In its fiscal 2026 year-end update, the company said it received more than $60 billion in new orders during the fourth quarter and guided to fiscal 2027 revenue between $65 billion and $72 billion, driven by sustained enterprise and cloud demand for AI infrastructure.
The Numbers
- Q1 FY2027 revenue guidance (revised): $18.5B to $19.5B
- Prior guidance: $14.5B to $15.5B
- Gross margin guidance (revised): 12.0% to 12.5%, versus prior guidance of 10.4% to 10.8%
- Official earnings call: November 3, 2026, post-market
Why the Stock Is Moving
Two things matter here, and they point in opposite directions. The revenue beat is undeniable: the new midpoint is roughly 27% above the prior midpoint, highlighting accelerating demand for AI-optimized infrastructure.
The gross margin improvement is the more interesting signal. Preliminary margins of 12.0% to 12.5% top the guidance range of 10.4% to 10.8%, with customer and product mix cited as the primary driver for both revenue and margin upside. The margin expansion suggests a higher-than-anticipated mix of higher-value configurations, which helps shield the company from base-server commoditization.
Cash From Oil in Days. Not Years.
No stocks. No waiting years for a payoff. A former hedge fund manager has a strategy that can turn an oil move into cash in a matter of days, and the chances come up again and again. He calls it “Oil Skimming.” And he’s giving away the entire three-step system for free.
But 12% to 12.5% is still low. Recent quarters have shown volatile margins, including periods in the mid-to-high teens followed by sharp compression, which the company has often tied to customer and product mix as it prices competitively to win large AI platform deployments.
Macro Context
Big Tech companies have signaled AI spending will not slow, and that is the rising tide lifting all AI infrastructure names. Dell has pointed to a record $51.3 billion AI backlog exiting its fiscal Q1 2027, underscoring the demand environment SMCI is describing.
Large AI customers generate enormous volumes but also possess significant pricing power, which is why the margin line remains the central tension for this stock regardless of how large the top-line number grows.
Forward Scenarios
Bull
Margin continues to expand toward 14% to 15% as liquid-cooled rack mix increases. Analyst targets reprice significantly above current consensus. The November 3 earnings call confirms revenue and provides strong Q2 guidance. SMCI reclaims the $40 to $45 zone, where several targets already sit.
Base
Revenue guidance holds but gross margin drifts back toward 11% to 12% by Q2 as hyperscaler pricing pressure reasserts. Shares consolidate between $35 and $42 as the market waits for sustained margin evidence across multiple quarters.
Bear
Management revises down on the November 3 call, citing product mix normalization. Margins slip below 11%. The after-hours gap partially fills, and SMCI retests the $29.50 support zone that acted as a floor through October. Customer concentration risk and margin volatility remain key factors keeping the stock’s multiple compressed.
Elon just declared war on your phone
Elon Musk just dropped another bombshell…
He’s going after your cell phone provider.
For months, Elon kept these plans under wraps.
But late last week, he finally showed his hand.
I’ve tracked this story for months, and it’s playing out exactly as I predicted.
Next, I believe Elon could launch a new device that kills the iPhone… and hands early investors his biggest payday yet. Potentially 50 times their money.
Technical Overlay
SMCI closed Tuesday at $32.47, extending into the mid-$36 range in after-hours trading. Before last night’s update, the stock was trading well below its 20-day and 50-day simple moving averages, with the 200-day simple moving average sitting near $32.5, meaning the stock was technically in repair mode entering the announcement. The after-hours move to the mid-$36s pushes SMCI through its 200-day simple moving average for the first time in weeks. Resistance sits in the $39 to $40 range; a sustained close above $40 with volume would open the path toward analyst target territory.
What Investors Should Watch
- November 3 earnings call: Gross margin confirmation is the single most important data point. A range above 12.5% would re-rate the stock. A slip below 11.5% would raise structural questions regardless of revenue size.
- Analyst target revisions: Citigroup, Mizuho, and Goldman Sachs are all likely to revisit models after a $4 billion guidance raise. Watch whether neutrals become constructive.
- Q2 FY2027 guidance: Super Micro’s history is one of lumpy quarters and volatile guides. The durability of this demand surge matters as much as the Q1 beat.
- Dell and HPE read-through: Both companies report in the coming weeks. Consistent AI backlog messaging across the group strengthens the bull case for the entire sector.
Bottom Line
The revenue upgrade is real, large, and credible. A $4 billion raise in a single preliminary update, with the midpoint landing about 27% above prior guidance, is not noise. The AI infrastructure spending cycle is running hotter than even optimistic models assumed three months ago.
But Super Micro’s stock has spent much of 2026 trading at a discount to peers precisely because revenue scale has not reliably translated into margin expansion. AI servers can behave like Nvidia GPU passthrough in the supply chain, and SMCI competes aggressively on price, so revenue can grow sharply without proportional profit expansion. The revised gross margin guidance of 12.0% to 12.5% is better than feared and better than the prior guide, but it is not yet the sustained improvement that would justify a structural re-rating.
The margin problem is not unique to Super Micro. Hyperscaler AI commitments totaling $2.4 trillion are already splitting between companies converting that spending into margin expansion and those absorbing it as cost.
The question the November 3 call must answer: is this a quarter where favorable mix briefly lifted margins, or the beginning of a durable recovery toward the mid-teens? That answer, more than any revenue figure, determines whether the after-hours pop holds.