Analyst Targets
- Evercore ISI: Outperform, target lowered to $315 (from $355) ahead of earnings
- Needham: Buy, $390 target
- Consensus (35 analysts): Median 12-month target $385; 29 Buys, 6 Holds, 0 Sells
A Quarter That Should Have Worked
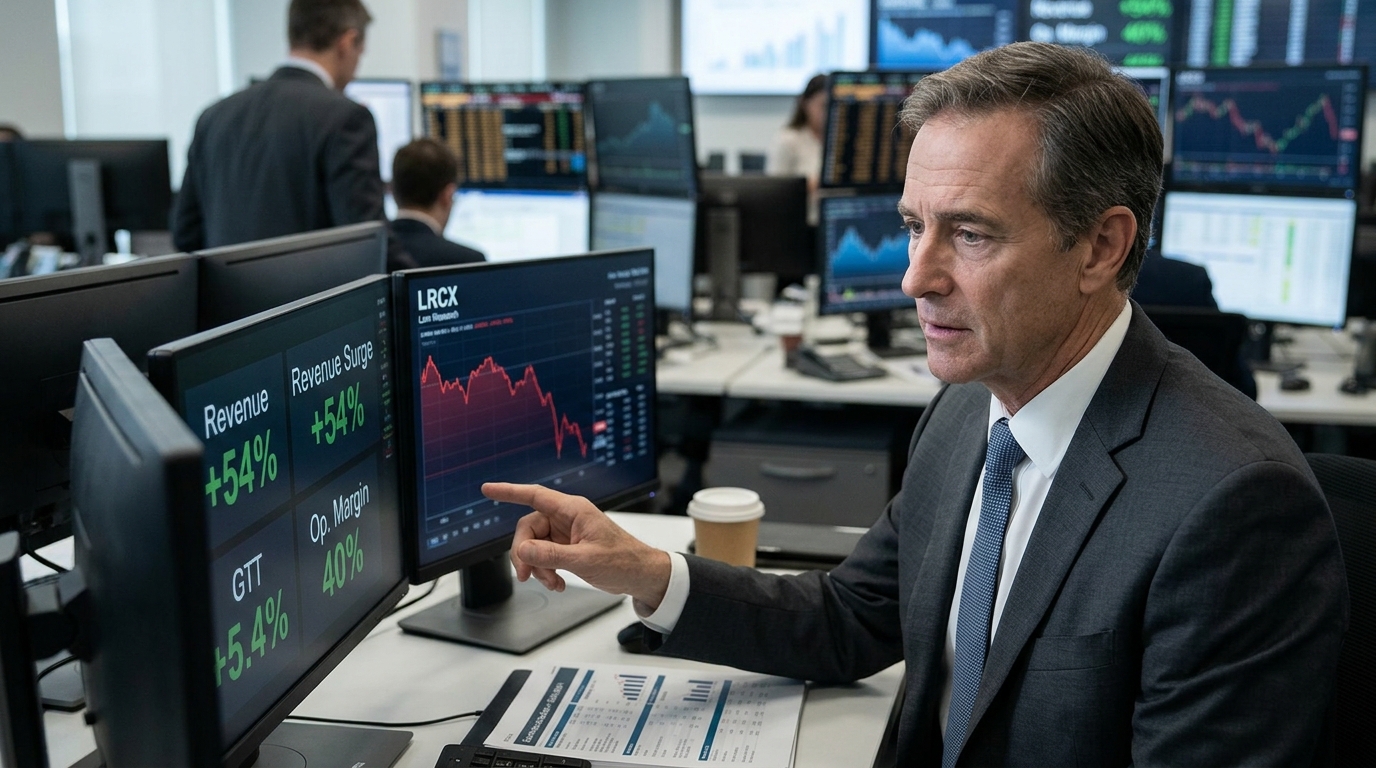
Lam Research reported its September 2026 quarter with revenue of $8.22 billion, GAAP operating margin of 40.0%, and GAAP diluted EPS of $2.19. Revenue grew 54% year over year, and operating margin topped 40% for the first time in the company’s history. The numbers, by any conventional measure, were excellent.
The drop erased roughly $24 billion of market value. The core issue was a guide that still came in only slightly above consensus, with the midpoint implying about 5% sequential growth from September after three quarters of acceleration.
The Numbers
- Revenue: $8.22 billion, beating the $8.14 billion estimate by $77.58 million
- Non-GAAP gross margin: 52.4%; non-GAAP operating margin: 40.2%; non-GAAP diluted EPS: $2.20
- Year-over-year EPS growth: +77.4%, from $1.24 to $2.19; free cash flow reached $3.24 billion
- Systems revenue: $5.73 billion, up sharply from $3.55 billion a year earlier
- Customer Support Business Group revenue: $2.49 billion, a fourth consecutive record quarter and 40% growth versus the prior year
- December guidance: Revenue of $8.60 billion +/- $400 million; operating margin 40.5% +/- 1%; GAAP diluted EPS $2.33 +/- $0.15
Why the Stock Fell
Three factors converged after the close, and none of them had to do with the quarter itself.
China peaked and is set to retreat. China accounted for 35% of September revenue. Management expects the share to fall substantially in December, with CFO Doug Bettinger saying he expects December to be meaningfully down, driven by domestic customers in China. A region that inflated the September beat becomes a headwind in the very next quarter.
The guide offered almost no room. Lam forecast $8.60 billion in revenue, just 0.35% above Wall Street’s $8.57 billion consensus. The wide guidance range for second-quarter revenue ($8.2 billion to $9.0 billion) and EPS ($2.18 to $2.48) introduced potential downside risks that concerned investors expecting a tighter, more confident outlook. The low end of that EPS range sits at the old consensus number.
Supply constraints capped what the guide could have been. CFO Doug Bettinger said on the earnings call that the guide would have been a bit higher without near-term supply constraints, and that delayed shipments move into the March quarter. That is revenue deferred, not lost, but the market priced it as a concern.
Macro and Industry Context
Management forecasts 2026 wafer fabrication equipment spending in the low-$150 billion range and has pointed to 2027 as a strong year for the industry. Lam expects to outperform WFE for a third consecutive year as deposition, etch, and advanced-packaging intensity increases. The long cycle is intact. The near-term question is whether a China-driven sequential deceleration signals something structural or is simply a regional inventory flush.
Memory accounted for 46% of systems revenue. On a dollar basis, memory revenue reached a record level and was up 120% from the same period a year ago. AI infrastructure investment is the engine; the risk is that a single geography, China at 35% of sales, can dislocate a quarter even when global demand is strong.
Memory’s record contribution to Lam’s systems revenue reflects a structural shift in who is buying equipment and why. The DRAM and HBM shortage driving that spending has reshaped which memory names are priced correctly for what remains ahead.
Bull / Base / Bear Scenarios
Bull: Supply constraints resolve in December, March-quarter revenue accelerates as deferred shipments ship, China stabilizes at a lower but steady share, and WFE above $200 billion in 2027 drives estimate revisions higher. LRCX trades back toward the $340-$385 analyst target range.
Base: December quarter lands near the $8.6 billion midpoint, China drags on growth sequentially, and the stock consolidates between $230 and $270 while the market awaits March guidance for evidence that the acceleration resumes.
Bear: China restrictions deepen, supply issues persist beyond March, and WFE 2027 estimates get cut. The 100-day chart shows major support at $229.77, a level that would represent roughly a 12% additional decline from the after-hours low.
Lam is not the only semiconductor name where record results failed to protect the stock from a sharp selloff. SK Hynix and Samsung both fell hard on record profits as China’s CXMT threat spooked memory investors across the region.
Technical Overlay
Lam Research shares closed at $260.81 on October 21, then fell 7.38% to $241.57 in after-hours trading. The stock entered earnings already damaged: one of the most consistent winners of the AI capital-spending cycle had closed lower every day since October 5 and shed 21.7% over the stretch. The after-hours gap down extends that damage well below the prior close, leaving the 52-week low at $133 as distant context and near-term focus on the $229-$242 gap zone. A recovery above $261 would be the first signal that sellers have exhausted.
Bottom Line
Lam just delivered its best quarter in history by nearly every margin metric, and the market sold it hard. The reason is specific: China revenue surged to 35% of sales in September and is now guided meaningfully lower in December, supply constraints clipped what the guide could have been, and the beat itself was thin enough that the headline obscured the details.
With the stock about 40% below its late-June 2026 high, the after-hours drop reflects a market that wants acceleration, not just strength. The 2027 WFE outlook above $200 billion keeps the long-term case intact. The question investors face now is whether December proves the deceleration was temporary, or whether the China pullback and supply friction signal that the sequential growth run is genuinely over. That answer arrives in January.