Dear Friend,
On January 30th, Elon sent the federal government a filing.
Almost nobody noticed.
It got buried under the biggest IPO in history.
But SpaceX had to come clean about it.
It called it “the largest actionable total addressable market in human history.”
$28.5 trillion.
That’s 8 times what every company Elon’s ever built is worth put together.
One tiny AI firm sits right in the middle of it.
Elon’s been paying it since 2012.
When NVIDIA tried to buy it, he fought the deal.
Now his bill to this firm could get 100 times bigger.
Thousands of SpaceX insiders can’t move on it until October 24th.
You can move today.
Get the name of Elon’s 100X AI stock here >>
“The Buck Stops Here,”
Kelly Maguire
Behind the Markets
P.S. Once October 24th hits, you’re racing 4,400 brand-new SpaceX millionaires for the same shares. Get in ahead of them here >>
American Express Earnings: Can Spending Hold Up in a Selloff?
Analyst Targets
- BMO Capital Markets: Outperform, $380 price target (initiated coverage)
- Morgan Stanley: Equal Weight, price target cut to $380
- JPMorgan: Overweight, price target reduced to $360
- TD Cowen: Hold, target lowered to $335
- UBS: Neutral, target reduced to $345
The Setup This Morning
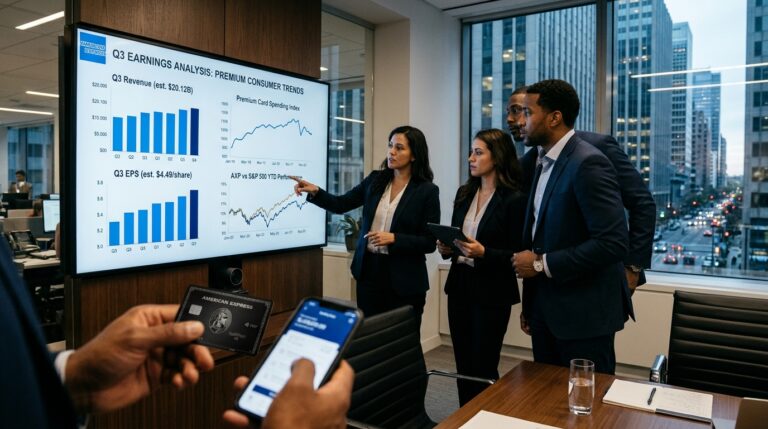
American Express drops its Q3 numbers before the open today, October 23, into the worst market session in months. The S&P 500 fell 1.2% and the Nasdaq shed 2.6% on Thursday as AI-investment anxiety swept through technology stocks. AXP closed Thursday at $325.17, down roughly 8% year-to-date, lagging the S&P 500’s roughly 13% gain over the same stretch.
The timing matters. Regional bank and consumer finance results have already cleared the decks this week. Now the market wants to know whether the affluent consumer, American Express’s defining customer, is holding or cracking.
Company Profile
American Express operates an integrated payments platform: it issues cards, runs a proprietary network, and acquires merchants, all under one roof. That closed-loop structure lets it capture discount revenue, net interest income, and card fees simultaneously, a model that competitors Visa and Mastercard, which do not issue cards directly, cannot replicate. The company’s 86.6 million proprietary cards-in-force generated $1.67 trillion in billed business in full-year 2025.
The Numbers: What Consensus Expects
- EPS: about $4.48, against $4.14 a year ago (about 8% growth)
- Revenue: about $20.1bn, implying approximately 9% year-over-year growth
- Billed business, U.S. Consumer Services: Expected up about 9% year-over-year
- Billed business, Commercial Services: Expected up low-single digits year-over-year
- Net interest income: Consensus implies roughly low-double-digit year-over-year growth
- Full-year EPS guidance: $17.30–$17.90 (management’s standing range)
American Express has beaten EPS estimates in six of its past eight quarters, with an average surprise of roughly 3%. Q1 2026 came in at $4.28. Q2 delivered $4.53. The bar is set, but it keeps rising.
Why the Expense Line Is the Swing Factor
In Q2, consolidated expenses rose 12% year-over-year to about $14.5bn, driven by higher variable customer engagement costs and higher operating expenses. That pace of cost growth, running faster than revenue in recent quarters, is the thing analysts are watching most carefully today. Card-member engagement costs are expected to have risen again in Q3 as travel and lifestyle benefit redemptions accelerated. If billed business volume comes in soft, the operating leverage argument breaks down fast.
Historically, AXP’s stock reacts more to billed business volumes and credit metrics than to the headline EPS number. A top-line beat paired with deteriorating credit quality has repeatedly faded in the hours after results. The reverse, credit holding firm even as spending growth decelerates, has generally held. Net write-off rates and reserve build in the conference call at 8:30 a.m. ET will be scrutinized alongside the spending number.
The closed-loop model AXP defends is now being challenged from an unexpected direction. Capital One’s acquisition of Discover gave it the same network economics AmEx built over decades — and a direct claim on the premium-card market.
The AML Fine: Background Noise or Cost Signal?
On October 8, the OCC assessed a $350 million civil money penalty against American Express National Bank for BSA and AML deficiencies, alongside a cease-and-desist order, with the Federal Reserve issuing a concurrent cease-and-desist order covering American Express Company and American Express Travel Related Services Company. Management has said it reserved for parts of the penalty in prior periods, and that its 2026 guidance remains unchanged. The near-term financial hit is contained. The longer-term question is what a mandated compliance overhaul costs in both dollars and management attention.
Forward Scenarios
Bull
Billed business grows at or above Q2’s 9% FX-adjusted rate. Expense growth decelerates relative to revenue. Management lifts the full-year EPS ceiling above $17.90. The stock recovers toward $340–$345, where several analyst targets cluster.
Base
Revenue hits consensus near $20.1bn, EPS lands around the Street view, and guidance is reaffirmed rather than raised. The stock grinds modestly higher, consistent with options-implied expectations of a roughly 3–5% move.
Bear
Spending growth slows to the mid-single digits and expenses continue to outpace revenue. Any reserve build or delinquency uptick in U.S. Consumer or Small Business amplifies the concern. The stock retests its 2026 lows below $310.
Technical Overlay
AXP has not reclaimed its 100-day moving average, and its RSI sitting in the mid-60s means the stock is already near overbought territory on a relative basis heading into the release. The daily range Thursday, $322.47 to $326.26, gives a narrow band to clear. Options markets have been pricing a mid-single-digit move in either direction.
Bottom Line
The earnings number itself is almost secondary. What investors need from this report is confirmation that the premium consumer is still spending at a pace that justifies the expense investment, and that credit quality has not quietly deteriorated while AXP was reinvesting its Q2 outperformance into card benefits and new partnerships. In a market that sold off hard the day before results, that confirmation carries more weight than usual. Billed business and the reserve line determine the verdict today, not the EPS release.