Analyst Targets
- Bank of America Securities, Buy, raises target to $800 (from $720)
- Goldman Sachs, Hold, maintains $615
- Barclays, Buy, maintains $620
- J.P. Morgan, Buy, cuts target to $600 (from $715)
- Morgan Stanley, Buy, trims target to $643 (from $676)
- Wells Fargo, Overweight, cuts to $450 (from $730)
- UBS, Neutral, trims to $470 (from $525)
The Setup That Sold Off
Western Digital reported fiscal Q1 2027 results after the close on October 22, 2026 that should, by any conventional read, have pushed the stock higher. Revenue hit $4.381 billion, up 55% year over year and ahead of the $4.14 billion consensus. Non-GAAP EPS came in at $4.64, topping the $4.08 estimate. Non-GAAP gross margin expanded to 58.1%, up 1,420 basis points from a year ago. The company generated $1.38 billion in free cash flow and raised its quarterly dividend 17% to $0.175 per share.
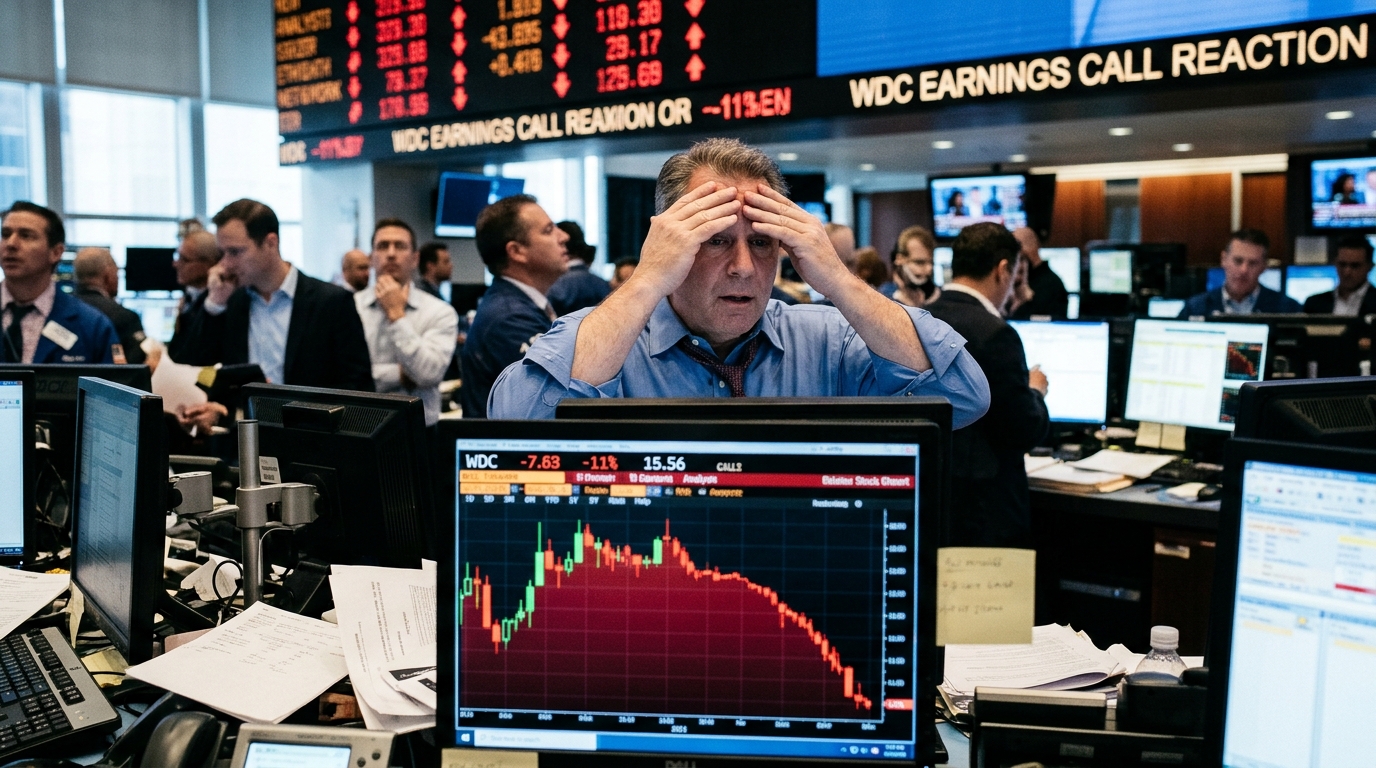
The stock fell 6.43% in the regular session to $354.19. In after-hours trading, it fell to roughly $337.01, down 4.85% versus the regular-session close. Across the regular session plus the after-hours move, WDC shed a bit more than 11%.
Company Profile
Western Digital is a San Jose-based hard disk drive and flash storage manufacturer serving hyperscale cloud customers, enterprise clients, and consumer end markets. Its competitive moat sits in high-capacity nearline HDDs, where it competes directly with Seagate. Cloud revenue has become the dominant engine: it accounted for 88% of total Q1 FY27 sales, or roughly $3.9 billion, up 54% year over year. Client revenue, at 7% of the total, grew 119% year over year.
The Numbers
- Revenue: $4.381 billion vs. $4.14 billion expected (+55% YoY)
- Non-GAAP EPS: $4.64 vs. $4.08 expected (+161% YoY)
- GAAP gross margin: 57.8%; non-GAAP gross margin: 58.1% (vs. 43.9% a year ago)
- Operating margin: 49.1% (non-GAAP)
- Free cash flow: $1.38 billion
- Exabyte shipments: 248 exabytes, up 22% YoY
- Average selling price per terabyte: up 28% YoY
- Q2 FY27 guidance: Revenue $5.0 to $5.2 billion; non-GAAP EPS $5.60 to $6.00; gross margin 60% to 61%
Why the Stock Is Moving
The selloff did not begin with the headline numbers. Shares initially jumped post-close, then reversed during the earnings call. Management disclosed that capital expenditures are expected to average 4% to 6% of revenue over the next five years, running modestly above that range over the next two years. Input costs are rising, notably for DRAM and NAND components. The company said it is pursuing value engineering to offset some of the pressure and expects cost per terabyte to fall roughly 10% year over year, but the forward cost trajectory spooked investors who had been pricing WDC as a pure margin-expansion story.
That is the real read. The question was never whether Q1 was good. It was whether the economics that produced 58% non-GAAP gross margins can hold as capex rises and raw material costs climb. The market decided, at least for one night, that the answer is uncertain enough to sell.
Macro Context
WDC did not fall in isolation. The same session saw SanDisk drop about 8% and Micron fall about 6%, with the Roundhill Memory ETF down about 7% while the Nasdaq fell roughly 3%, confirming the selling was concentrated in memory names. That sector pressure was already in place before WDC reported. The earnings call added a company-specific cost concern on top of a sector already under pressure, which helps explain the severity of the move.
Management pushed back on the supply fear angle, noting it does not plan further unit expansion and will focus on areal density gains. Demand from neo-cloud customers and AI frontier labs is broadening the addressable base beyond traditional hyperscalers.
Forward Scenarios
Bull
Gross margins reach 60%+ in Q2 as guided, pricing holds on long-term agreements, capex stays at the low end of the 4% to 6% range over time, and the CXMT threat proves contained to DRAM rather than NAND. WDC re-rates toward the $650 to $800 consensus.
Base
Margins expand modestly, capex runs toward 6% of revenue, and pricing gains decelerate as management acknowledged they must. The stock consolidates in the $340 to $420 range while the market waits for Q2 actuals to validate the guidance.
Bear
Rising input costs compress margins before the capex ramp pays off. Chinese capacity additions reach NAND, softening pricing. The stock revisits its pre-earnings levels near $320. Wells Fargo’s $450 target, already the most cautious among the bulls listed, proves optimistic.
Technical Overlay
WDC closed the regular session at $354.19, then after-hours trading down to roughly $337.01 created a significant gap below the prior trading range. The stock is now trading well beneath its 50-day moving average, and the gap at roughly $355 to $378 becomes near-term resistance. The first support zone sits around the $320 to $330 area from the pre-earnings consolidation base. Any earnings-driven gap of this size historically takes two to four weeks to resolve directionally. Price action will follow whether Q2 margin guidance proves conservative or aspirational.
What Investors Should Watch
- Gross margin trajectory: Q2 guidance of 60% to 61% is the next hard test; a miss would confirm the cost concern
- Capex disclosures in the 10-Q for the precise near-term spending path
- CXMT capacity announcements and whether they extend into NAND or remain DRAM-focused
- Analyst revisions: J.P. Morgan already cut its target to $600; watch for further resets post-call
- SanDisk and Seagate quarterly results for pricing corroboration across the HDD complex
Bottom Line
Western Digital’s Q1 was genuinely strong. The selloff is not a verdict on Q1; it is a question about the back half of fiscal 2027, when higher capex and rising input costs are expected to land. The gap between roughly $337 after hours and the Street consensus is enormous, and it reflects a market that wants proof the margin story survives the cost cycle, not just a single exceptional quarter. The next earnings call, not this one, will determine whether the stock recovers or the discount widens further.