Analyst Targets
- TD Cowen: Hold, $90 target (raised from $40 on October 21)
- RBC Capital: Sector Perform, $130 target
- Goldman Sachs: Neutral, $137 (raised October 15)
- Morgan Stanley: Equal-Weight, $95 (raised October 7)
- Citi: Sell, $80 (downgrade September 30)
- BofA: Neutral, $200
What Happened
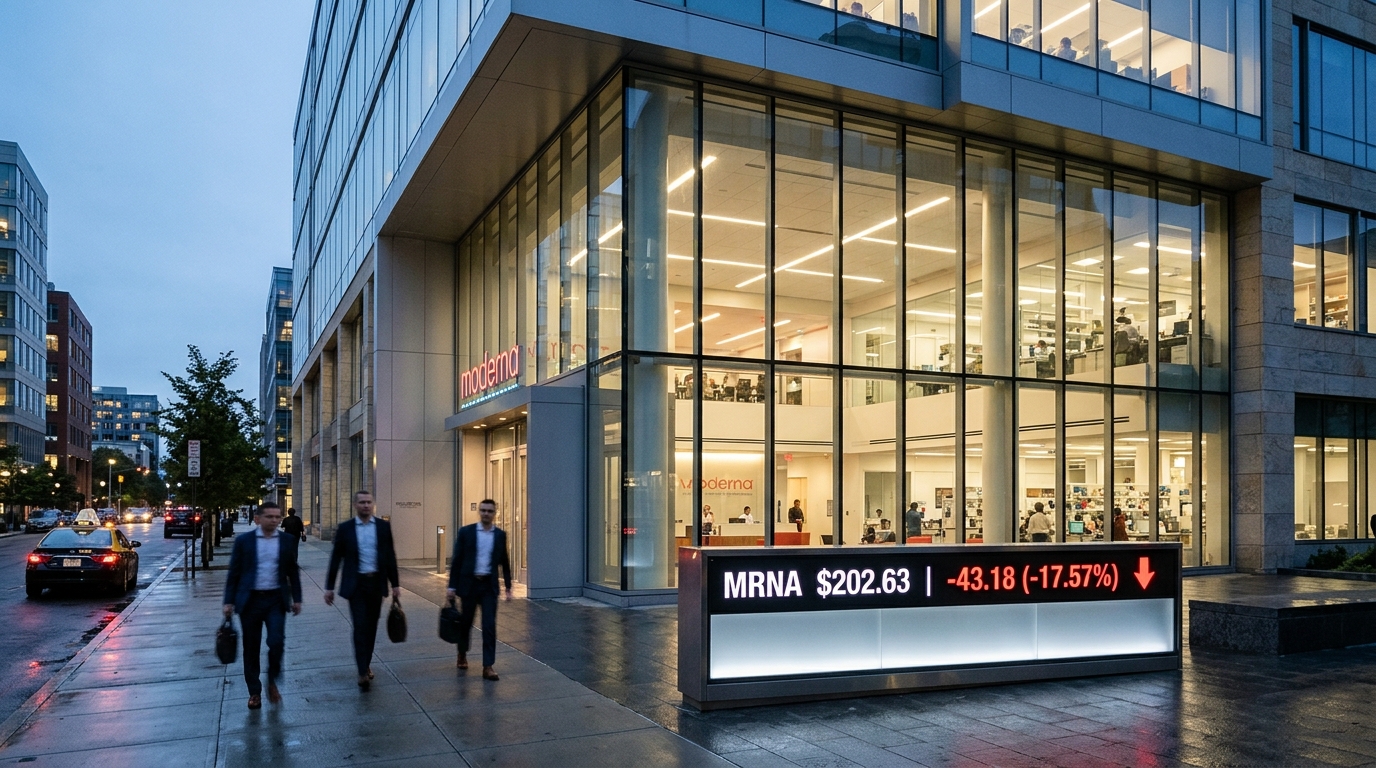
MRNA closed at $202.63 on Thursday, October 22, down $43.18, or 17.57%, from Wednesday’s $245.81, after detailed INTerpath-001 data on intismeran autogene appeared online ahead of its scheduled ESMO release and the companies then posted the full dataset early following the breach. The stock fell by about 26% during the session, reaching an intraday low of $180.80 before recovering into the close.
The data that caused it was not bad.
The Numbers
The vaccine, intismeran autogene, reduced the risk of melanoma recurrence or death by 42% when given alongside Merck’s Keytruda, compared with Keytruda alone. The combination also reduced the risk of cancer spreading to distant parts of the body or death by 38%, in a Phase 3 trial enrolling 1,137 patients whose tumors had been surgically removed.
- Hazard ratio (RFS): 0.58 (95% CI, 0.45-0.75; P < .001)
- Median follow-up: 24.6 months
- Trial: Phase 3 INTerpath-001, 1,137 patients, stage IIB-IV resected melanoma
- Two-year recurrence-free survival: 82.2% (vaccine arm) vs. 70.0% (Keytruda alone)
- Overall survival: Not yet mature
The data are scheduled for presentation at a Presidential Symposium at ESMO Congress 2026 in Madrid on Saturday, October 24, 2026, and the companies said the results have been accepted for publication in the New England Journal of Medicine.
Why the Stock Is Moving
The data showed a 42% cut in the risk of recurrence or death versus Keytruda alone: a clear win, but no improvement on earlier Phase 2b results. A previous mid-stage readout found that after more than 60 months, intismeran autogene plus Keytruda cut the risk of death or recurrence by 49% versus the PD-1 blocker alone. The larger Phase 3, using different patients and a shorter follow-up, came in at 42%. That gap, from 49% to 42%, was enough to shake a stock that had nearly quadrupled in two months on expectations of something more.
Moderna had already stated a 35% lowering would constitute a clinically significant outcome. On that standard, the data passed. The market priced it as a disappointment anyway, because the problem was Moderna’s fat valuation, which even a groundbreaking cancer treatment could not fully support.
Macro and Industry Context
Six melanoma specialists told CNBC the results represent a clinically meaningful advance that could potentially become a standard of care for melanoma patients who undergo surgery first and have not received immunotherapy before their operation. The regulatory path is active: based on the results, the companies said they are engaging with regulatory authorities.
If approved, intismeran could deliver $6 billion or more in annual sales in melanoma alone, per analyst forecasts, split evenly with Merck under the terms of the partnership. The companies currently have nine total Phase 2 and Phase 3 trials underway across multiple tumor types including melanoma, non-small cell lung cancer, bladder cancer and renal cell carcinoma.
Partnership economics cut both ways. A Phase 3 failure can erase hundreds of millions in milestone and royalty value that a co-development deal had made to look certain.
Bull / Base / Bear
Bull: The ESMO presentation today in Madrid confirms practice-changing status. Physicians adopt intismeran as adjuvant standard of care for resected melanoma ahead of regulatory approval. Overall survival data, when it matures, holds or improves. The platform expands into lung. Stock recovers toward its pre-leak high near $246 and beyond as the revenue model gets refined upward. TD Cowen’s revised peak-profit estimate for intismeran reaches approximately $3.4 billion by 2035.
Base: FDA filing proceeds, approval arrives in 2027, and commercial ramp is slow due to manufacturing constraints. Producing a unique 34-neoantigen construct per patient introduces cost, capacity and access constraints that do not exist for an off-the-shelf biologic. MRNA trades in the $180-$220 range pending the next data inflection, with overall survival remaining the unanswered question.
Bear: Overall survival data, when it arrives, disappoints. Competing approaches or next-generation PD-1 combinations erode the combination’s clinical edge. The stock, still well above consensus targets, rerates closer to the $90-$130 range that most sell-side models currently support.
Technical Overlay
MRNA’s 52-week high stands at $254.48, reached October 21. The 52-week low is $22.28. Thursday’s intraday low of $180.80 was recovered by the close, with the stock settling at $202.63. That $180 level is the first meaningful support from the reaction low. The gap down from $245 represents a major volume node that would serve as overhead resistance on any recovery attempt. The pre-leak close of $245.81 is the line that defines whether the move has been absorbed or merely paused.
What Investors Should Watch
- Saturday’s full ESMO Presidential Symposium presentation and physician reaction in Madrid
- FDA filing timing: companies said they are engaging regulators
- Overall survival data maturity from INTerpath-001
- Q3 earnings timing and any updated commercial manufacturing guidance
- Early data from non-melanoma intismeran trials, particularly NSCLC
Bottom Line
The science delivered. The stock’s problem is arithmetic, not biology. RBC Capital calls the melanoma data a massive scientific breakthrough and sees a balanced risk and reward profile after the initial share price reaction. TD Cowen, more sober, kept its Hold at $90 even after raising the target. Both are right about different things. The INTerpath-001 result is the first Phase 3 win for a personalized mRNA cancer vaccine; that is not in dispute. What is in dispute is how much of the commercial case for 2030 and beyond was priced into $246. The answer, it turns out, was most of it. The next move in MRNA depends less on the abstract ESMO releases and more on whether the overall survival curve, still immature, holds when it is finally shown.