The CIA Accidentally Discovered the Rare Earth MOTHERLODE
…And One $5 Stock Sits at the Center of it ALL
Dear Reader,
Inside the CIA’s private museum at Langley sits a strange black rock, sealed in a block of clear plastic.
It looks like a lump of coal… but it’s NOT.
It’s a tiny piece of the biggest discovery of critical resources ever made… a $16 trillion treasure trove that 60 Minutes calls “staggering.”
And one small company you can buy today for about $5 holds the rights to harvest the richest stretch.
Click here for the jaw-dropping TRUE story.
As you’ll see…
The CIA stumbled onto it during one of the boldest secret missions of the Cold War.
To hide what they were really doing, they teamed up with billionaire Howard Hughes and invented a fake mining company.
The whole world bought the story.
But when the mission was over, the CIA came back with something nobody expected… rocks as heavy as gold bricks, packed with rare earths, cobalt, nickel and lithium.
These are the same materials that are driving the 21st-century economy.
America can’t build a fighter jet, an electric car or an AI data center without them.
A $16 Trillion Chess Move that practically nobody sees coming…
At the center of it all is the only company with the technology and track record to harvest this rare earth motherlode.
A publicly traded stock you can buy right now for $5.
The last time Trump backed a mining company like this, its stock shot up 407% in a single week. This time, I believe this stock could hit $50 by the time Trump’s second term is over.
Click here for the details before Trump makes his move.
Regards,
Matt McCall, Head Innovations Strategist
Monument Traders Alliance
P.S. A former CIA insider just sent me Trump’s executive order by OVERNIGHT FedEx, with one section highlighted in yellow. Click here to see why it could be the key to 1,000% gains before Trump leaves the White House.
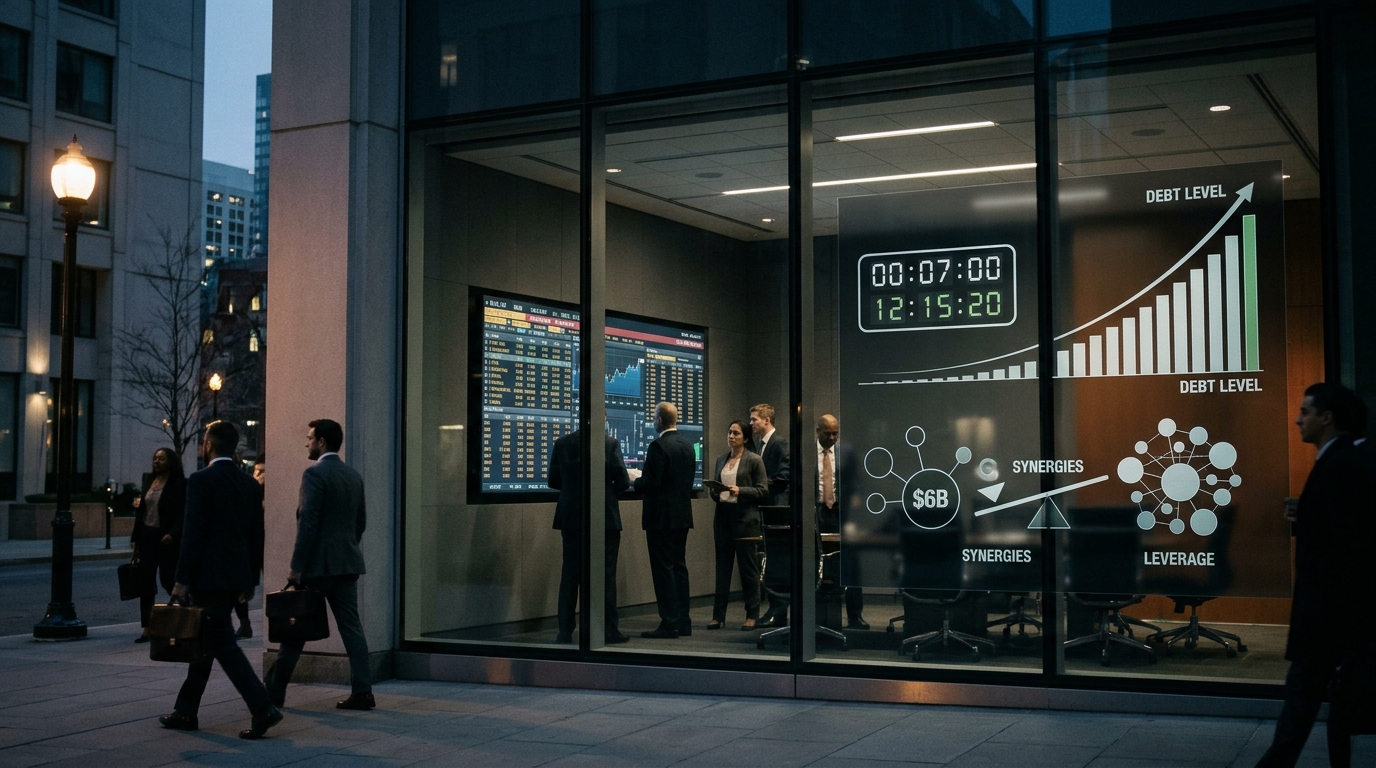
Skydance Reports Tonight. The Debt Clock Is Running.
Analyst Targets
- Citi (Jason Bazinet): Buy, $10 target, resumed coverage, sees investor skepticism as overdone on 2027–2029 EBITDA estimates
- JPMorgan (David Karnovsky): Neutral, $9 target, reinstated coverage after lifting a prior restriction
- Huber Research (Craig Huber): Overweight, $10 target, upgraded ahead of tonight’s report
- Barclays (Kannan Venkateshwar): Underweight, $7 target
- Bernstein (Laurent Yoon): Sell, $6 target
- Consensus (24 analysts, S&P Global): Hold, average target $9.15
What Tonight Actually Is
Skydance Corporation reports Q3 2026 earnings at 5:00 PM EST on November 9. The quarter itself ended September 30, six days before the acquisition closed on October 6, 2026. With the merger now closed, investor attention shifts from deal approval to debt reduction, integration, and cash flow.
This call is not really about the Q3 numbers. It is the first time management addresses Wall Street as the combined company, and every question on the call will point in one direction: how fast can they deleverage, and what synergy figure will they put on record tonight?
Company Profile
Formed from the 2025 merger of Skydance Media and Paramount Global, the company generates revenue through three primary segments: TV media networks including CBS, MTV, and Nickelodeon; filmed entertainment via Paramount Pictures; and direct-to-consumer streaming services including Paramount+, Pluto TV, and BET+. The October 6, 2026 close of the Warner Bros. Discovery acquisition added HBO, Max, CNN, DC Studios, Warner Bros. Motion Picture Group, and a portfolio of cable networks. Together, the combined entity has publicly outlined a larger content slate, including a commitment to at least $6 billion of run-rate synergies within three years.
The Numbers
Analysts estimate Q3 revenue of $7.02 billion, up roughly 4.7% year over year, with EPS expected at $0.06, a turn to profit from a year-ago loss. That Q3 revenue reflects only the legacy Paramount Skydance business. The WBD assets consolidate beginning with Q4.
Revenue estimates heading into the report have seen more positive momentum, with seven upward revisions versus two downward. EPS revisions have been more mixed, consistent with the difficulty of modeling a balance sheet that changed structurally five weeks ago.
Last quarter’s pre-merger results offer useful framing. Direct-to-consumer streaming revenue was up 9% to $2.47 billion, while film studio revenue increased 16% to $1.31 billion, though TV media revenue declined 9% to $3.13 billion.
Why the Call Matters More Than the Quarter
The new Skydance has to prove that combining two challenged traditional-media businesses can generate enough cash to service more than $80 billion of debt while still spending enough to compete with Netflix. That turns the $6 billion synergy target from merger upside into a balance-sheet requirement.
The competitive pressure on the other side of that equation is real. Netflix’s ad tier is already generating roughly $3 billion in annual revenue while the combined Skydance entity is still assembling its streaming stack.
Management’s public position has been consistent. The company has told investors it is targeting at least $6 billion of run-rate synergies within three years, with 30% achieved in year one and 70% achieved in year two, and it has also communicated targets of 3.75x net leverage in 2028 and 3.0x in 2029. Tonight is when those pledges meet a live investor call for the first time.
Macro Context
Linear TV continues to struggle. Streaming remains the offset, but the combined entity now competes directly with Netflix at scale.
Forward Scenarios
Bull
Management guides 2027 EBITDA above a $13.7 billion Debtwire base case by front-loading synergy realization. An upside beat on that figure, combined with streaming subscriber growth in the combined HBO Max and Paramount+ base, rerates SKYD toward the $10–$11 target range.
Base
Management delivers a credible integration roadmap, confirms first synergy milestones on track, and provides 2027 revenue guidance near $30 billion for the combined company. Stock trades in the $8.50–$9.50 range. Leverage concerns stay present but are priced.
Bear
Skydance is projected by some credit-side models to operate through much of 2027 with negative free cash flow, barring a box office windfall or streaming subscriber surge. If management’s 2027 EBITDA guidance disappoints or synergy timelines slip, the stock tests the $6–$7 range where three sell-side analysts already sit.
Technical Overlay
SKYD closed at $8.01 on November 6, 2026, well off its 52-week high of $17.16. The stock has been compressing toward the low end of analyst targets since the deal closed.
Bottom Line
The Q3 revenue figure is almost beside the point tonight. The company has committed to at least $6 billion in run-rate synergies within three years. What moves SKYD after 5:00 PM is whether management can narrow the range on when those synergies arrive and whether 2027 free cash flow will be positive enough to begin actual debt reduction. Every quarter that passes without demonstrated synergy delivery widens the credibility gap. The first post-merger call sets the floor or the ceiling for the next twelve months.