Analyst Targets
- H.C. Wainwright: Buy, $120 target (maintained November 5)
- Chardan Capital: Buy, $115 target (maintained October 15)
- Goldman Sachs: Hold, $74 target
- Consensus: Average target $107.71; roughly 120% upside from today’s close near $48.60
What Happened This Weekend
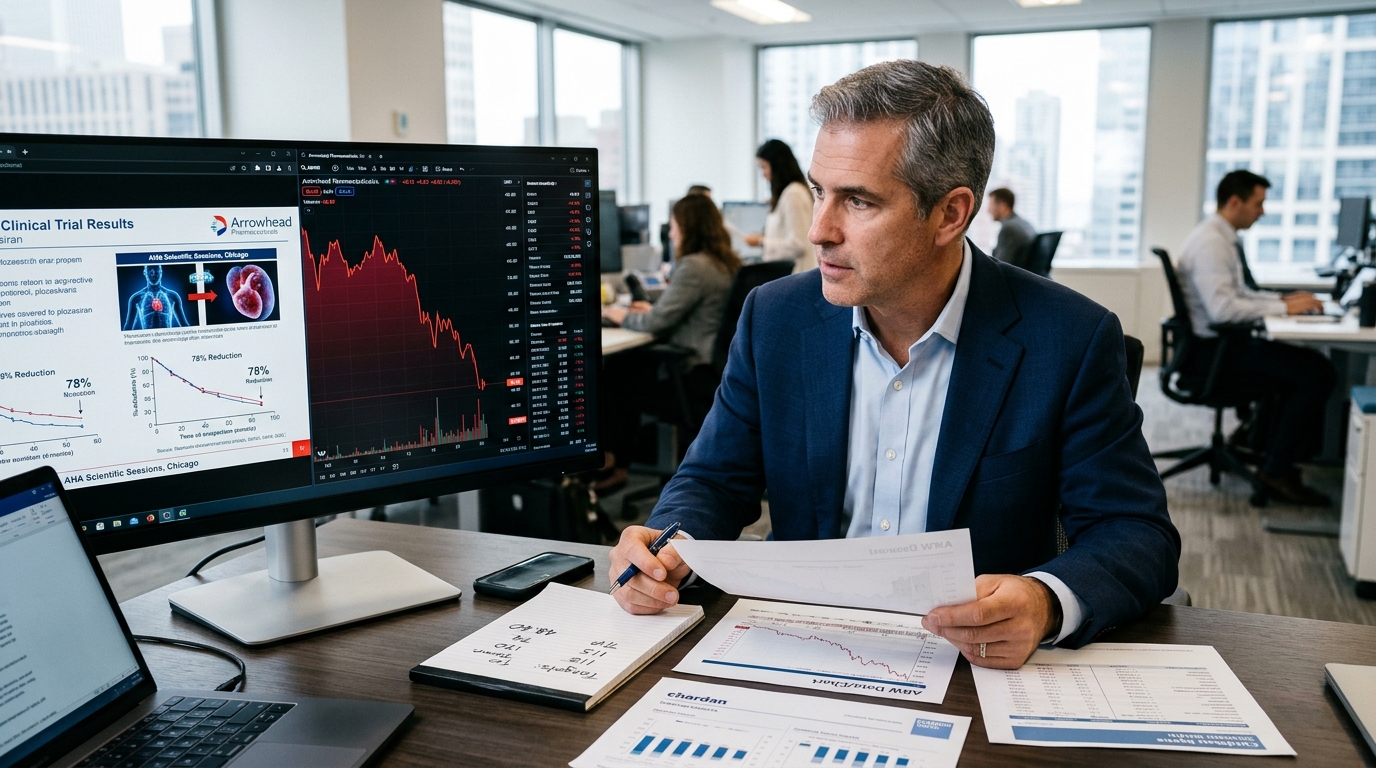
Arrowhead showed up at the American Heart Association’s Scientific Sessions in Chicago on November 7 with two data sets that should have been share-price events. Plozasiran reduced acute pancreatitis event rates by 78% versus placebo in pooled Phase 3 data, and the PALISADE open-label extension confirmed sustained triglyceride reductions through up to 36 months in FCS patients.
Then came ARO-DIMER-PA. Early Phase 1/2a results showed mean LDL-C reductions of up to 65% and median triglyceride reductions of up to 78% after a single dose: the first clinical proof of concept for targeting two complementary lipid pathways with a single RNAi molecule. ARWR opened Monday at $52.49, against a prior close of $58.16, and kept falling to close near $48.81.
Why the Data Did Not Hold
The sell-off is about expectations, not science. Though the LDL reduction looks solid, it is in the same neighborhood as existing PCSK9 medicines. Investors who bought ahead of AHA on the expectation of transformative differentiation found single-dose data that looked more like confirmation than revelation. Multiple-dose results, which would reveal durability and competitive separation, are still outstanding.
The broader AHA context matters. Pelacarsen and ziltivekimab, two heavily watched cardiovascular drugs from Novartis and Novo Nordisk, failed at the same Chicago conference. That compressed the entire cardiovascular biotech space, and Arrowhead caught part of that overhang regardless of its own results.
What Thursday’s Report Must Deliver
Arrowhead releases Q4 fiscal 2026 results after the close on November 12. Consensus estimates vary by data provider, but cluster around a loss of roughly $1.5 to $1.6 per share.
The critical number is REDEMPLO net sales. Arrowhead has cited more than 400 prescriptions written and a weekly run rate in the 20 to 30 range, but has not broken out net revenue separately. Disclosure here converts launch anecdotes into evidence. Management must also reaffirm the plozasiran sNDA timeline: the company has said the FDA granted plozasiran entry into the STAR pilot program in October 2026 in connection with an upcoming supplemental filing in severe hypertriglyceridemia, with Arrowhead targeting a year-end 2026 submission and a six-month Priority Review.
Bull / Base / Bear
Bull: REDEMPLO net sales surprise to the upside, management reaffirms the sNDA, and the gap closes. The cardiometabolic platform re-rates toward analyst consensus near $107. Base: Revenue lands near consensus, net sales are modest but disclosed, sNDA on track. Stock finds footing in the $50s. Bear: Revenue misses, payer friction surfaces, sNDA commitment softens. The stock tests its 52-week low near $37.
Technical Overlay
ARWR’s 50-day moving average sits at $67.52. RSI has dropped to roughly 37 and volume is running more than three times the 30-day average. The $50 zone is now resistance, not support.
Bottom Line
Arrowhead’s data is good. The drop is a function of AHA sector contagion and investor frustration that single-dose ARO-DIMER-PA data does not yet separate the drug from approved PCSK9 inhibitors. Those questions are solvable: multi-dose durability data will answer differentiation, and the sNDA will reset the plozasiran story by December. Thursday is simpler. Show that REDEMPLO is a commercial asset, not a launch anecdote. If Arrowhead does that and holds the sNDA timeline, this gap becomes an entry. If it cannot, every other pipeline catalyst faces the same credibility question.