September 15, 2026
Bonus Content: Axon’s $15.1 Billion Backlog Is a Software Business in Disguise
Editor’s Note: Elon’s next launch will be bigger than SpaceX, Tesla and xAI combined, says the man voted America’s #1 stock picker in 2020. Get the full story from my colleague while there’s still time.
Dear Reader,
I recently paid $5,000 to be in a room with Elon Musk in Los Angeles.
And what he said in that room, confirmed everything my 15+ years in the tech industry had been telling me.
Most people see the rockets, the cars, the headlines and think they understand Elon.
But what they don’t realize every single thing Elon does is years… sometimes even decades… in the making.
And it’s all connected in ways we’re only just starting to see.
But I believe what Elon is launching right now – a project 27 years in the making – could be his biggest move yet.
And make you more money than anything he’s ever touched.
If you buy just one stock in 2026, I urge you to make it the one I’m giving away for free here.
Best,
Luke Lango
Senior Investment Analyst, InvestorPlace
P.S. My readers have had the chance to see gains as high as, AMD +8,500%… Nvidia +5,000%… Tesla +3,500%… GameStop +2,700%… IonQ +1,400%… Shopify +1,400%… Netflix +1,200%… Palantir +1,200%… AppLovin +800%… Apple +890%… Meta +850%… and Rocket Lab +1,250%.
Axon’s $15.1 Billion Backlog Is a Software Business in Disguise
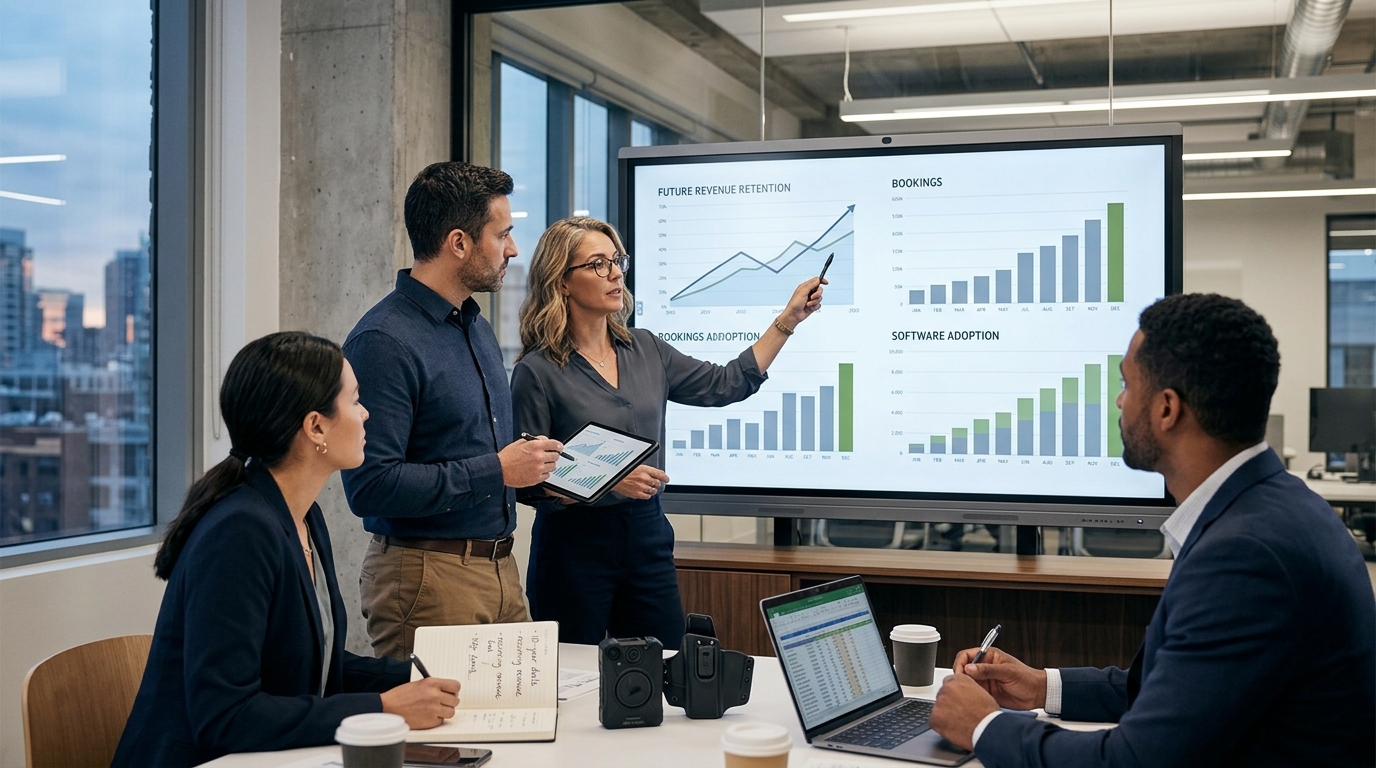
The story most investors tell about Axon Enterprise centers on body cameras and stun guns. The financials argue something different. Net revenue retention reached 126% in Q2 2026, while future contracted bookings rose 41% year over year to $15.1 billion. Those two numbers, taken together, describe a software flywheel, not a hardware cycle.
Axon reported record revenue of $904 million in Q2, up 35% year over year, with Software and Services rising 36% to $398 million. AI Era Plan revenues increased nearly 700% year over year. That kind of growth rate is anomalous for a product sold primarily to cash-constrained municipal governments, which is what makes the procurement data so revealing.
The Contract Structure Is the Real Moat
The market is shifting toward longer agreements. Traditional body camera contracts ran three to five years, but Axon is now signing 10-year platform deals, including with Maricopa County and Burleson, Texas. Rather than piecemeal procurement, agencies are getting everything from conducted energy devices to evidence management under a single vendor agreement. Each additional module sold into an existing account, whether Fusus real-time crime center data or Draft One AI report writing, compounds directly in net revenue retention without requiring a new sales cycle.
By the end of 2025, Draft One had contributed to over 100,000 incident reports, and the ability to automate up to 40% of officer time traditionally spent on paperwork is being cited by some city councils as a fiscal necessity, especially with 65% of agencies reporting service reductions or specialized-unit cuts because of staffing shortages in a recent nationwide survey. That framing matters: it converts a technology purchase into a staffing solution, which opens a different budget line entirely.
International Is the Underappreciated Leg
International bookings were roughly 3x prior year in Q2, with three of Axon’s top five AI Era Plan deals coming from international customers. Executives have cited Draft One’s expansion into more markets and Axon Assistant’s real-time translation capabilities as drivers of overseas AI demand. International revenue represented 20% of total in Q1 2026, and the pipeline heading into the second half was described as full.
Bull / Base / Bear
- Bull: Only about 30% of customers are on premium subscription plans today, leaving substantial upsell runway. If AI Era Plan attach rates converge toward the full installed base, ARR could scale well ahead of current consensus.
- Base: Full-year 2026 revenue growth of 32% to 34% with Adjusted EBITDA margin of approximately 25.5% holds, and net revenue retention sustains above 120%.
- Bear: The adjusted EBITDA margin target is pressured by tariff-related memory component costs with no tariff-refund benefit, and any deceleration in net revenue retention toward 110% signals that software expansion within the installed base is plateauing.
Bottom Line
The municipal contract wave is not the catalyst; it is the confirmation. Agencies across Maricopa, San Bernardino, and dozens of smaller jurisdictions are committing to Axon for a decade, bundling hardware, AI, and cloud storage under one agreement. Axon has said about 95% of revenue is now tied to customers on subscription plans, which means the revenue stream looks far more like enterprise SaaS than anyone buying the stock for its Taser franchise has fully priced. The 10-year deals being signed today are tomorrow’s ARR growth. That is what the $15.1 billion backlog actually represents.