September 17, 2026
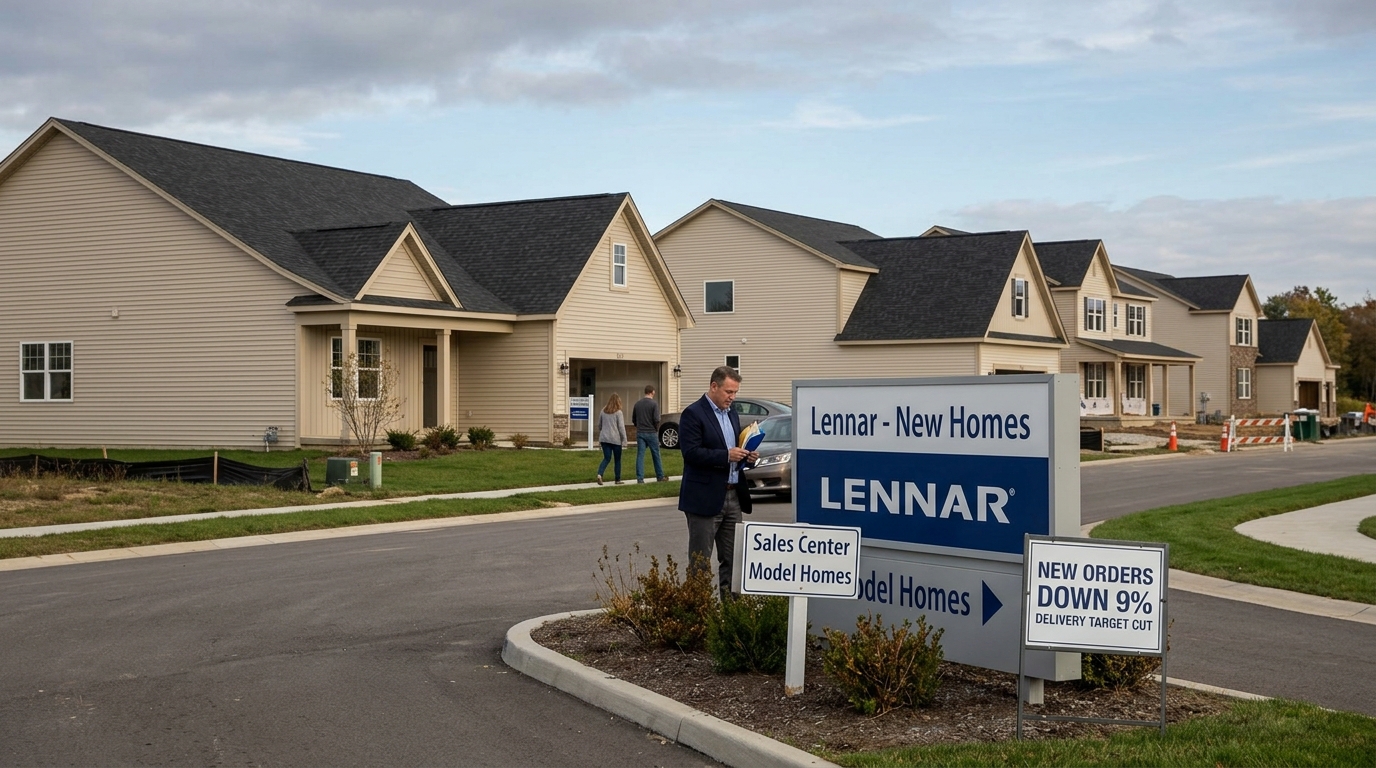
With new orders down 9% and the delivery target cut again, the Q3 report shifts the debate from what Lennar earned to what it can sell.
Analyst Targets
- Bank of America Securities: Underperform, price target $70 (cut prior to earnings, citing book value concerns and downward EPS revisions through FY28)
- Consensus (19 analysts): Hold, average 12-month price target $84.92
The Quarter in Full
Lennar reported fiscal Q3 2026 results after the close Wednesday, hours after the Federal Reserve hiked rates and signaled more could follow. The timing made a difficult quarter harder to absorb.
Hidden in Tesla’s Filing: A $12 Billion “Super Startup”
Pull up Tesla’s most recent SEC filing. Page 5.
And you’ll see a single line showing $12 billion in revenue from a brand-new “super startup” Elon Musk has been quietly incubating inside Tesla.
This new “super startup” has nothing to do with cars or robots or space or AI…
But it sits at the center of what Blackstone calls “a $23 trillion investment opportunity.”
And on October 21, Elon is expected to pull back the curtain and reveal exactly what he’s building.
But Adam O’Dell already knows… and he reveals it all in this urgent video.
Adjusted EPS came in at $1.23, missing the analyst consensus of $1.29, while revenue totaled $8.05 billion against the $8.31 billion estimate and fell 9% year over year from $8.81 billion. Net earnings dropped to $284 million, or $1.19 per diluted share, from $591 million, or $2.29, a year earlier.
The earnings miss is almost a footnote. What matters is the forward signal.
The Numbers
- New orders: fell 9%, to 20,879 homes, as higher mortgage rates and weaker consumer confidence continued to delay purchases
- Deliveries: down 3% to 20,840 homes; average delivered price dropped 3% to $372,000
- Gross margin: compressed to 15.8% from 17.5% a year earlier
- Incentives: approximately 12% of home price used to sustain sales volume
- SG&A: rose to 9.2% of home sales revenue despite lower revenue
- Operating margin: 5.5%, down from 7.9% in the same quarter last year
- Backlog: 16,857 homes with a dollar value of $6.3 billion, down 4.5% year on year
- Full-year delivery target: cut to 80,000\u201381,000 homes, down from the prior 82,000\u201383,000
Why the Stock Moved on Guidance, Not the Miss
LEN declined roughly 2.1% on the results, closing Wednesday at $78.36 and trading as low as $77.83. The reaction is less about the adjusted EPS shortfall and more about what management is telling investors about the months ahead.
Q4 guidance calls for 22,000\u201323,000 deliveries but only 19,500\u201320,500 new orders, with an average sales price of $370,000\u2013$380,000 and a home-sales gross margin of 15.5%\u201316.0%. The order range matters most: it is the demand signal that precedes every future delivery figure.
The #1 Commodity Trade of 2026
Gold bugs are going to hate this. The #1 commodity trade of 2026 isn’t gold, silver, oil, or any rare earth metal. It’s something far more valuable – something The New York Times says “powers the world’s tech.”
And America controls over 80% of the world’s supply. When Trump restricts exports, Morgan Stanley estimates it could trigger a $10 trillion boom. And you have the rare opportunity to get in on the ground floor.
The Q4 gross margin guidance does not indicate a significant near-term recovery, and new orders declined faster than deliveries despite a higher community count. That combination means Lennar is filling its backlog faster than it is refilling it.
Macro Context
The 30-year mortgage rate stood at roughly 6.8% near quarter end and has moved higher since, with Freddie Mac putting the 30-year fixed-rate mortgage at 6.76% as of September 10. Inflation remains above the Fed’s target, and affordability continues to weigh on demand.
U.S. homebuilder confidence fell to a 12-month low in September as mortgage rates, weak buyer traffic, and rising costs pushed more builders toward price cuts and sales incentives. July housing starts, reported last month, already confirmed the pressure: starts fell 12.4% month-on-month to 1.239 million annualized units, below the consensus forecast of 1.30 million. August data from the Census Bureau lands at 8:30 a.m. ET this morning and will either compound or modestly offset the sector’s read-through from Lennar’s results.
Bull / Base / Bear
Bull: The Fed pauses after Wednesday’s hike, the 30-year rate retreats toward 6.4%, incentive costs ease, and Q4 gross margin lands at the top of the 15.5%\u201316.0% guided range. Orders re-accelerate into fiscal 2027, where consensus currently expects EPS near $6.66.
Base: Rates stay elevated through year-end, incentives remain near 12%, and Lennar delivers to the low end of Q4 guidance. Annual deliveries come in at 80,000, margin stabilizes but does not recover, and the stock trades sideways in the $75\u2013$85 band as investors wait for rate relief.
5 Nasdaq Stocks Under $5 That Aren’t What You Think
Most stocks under $5 come with a reputation. These don’t.
Each company on this list is tied to major trends like AI, cybersecurity, and next-gen infrastructure.
They may not have the spotlight yet, but they are building real businesses in real markets. That combination is not always easy to find at this price level.
Bear: A second Fed hike arrives before year-end, orders deteriorate further into fiscal 2027, and delivery guidance requires a third cut. Margin falls below the guided floor. LEN tests its 52-week low, and earnings revisions cascade across DHI, PHM, and the ITB homebuilder ETF.
Technical Overlay
LEN traded between a low of $77.83 and a high of $81.45 on September 16, and has ranged between $75.50 at its lowest and $139.44 at its peak over the past year. The pre-earnings close of $80.07 has now become resistance. A hold above $75.50 is the line that separates a base-building situation from a fresh breakdown.
What Investors Should Watch
- August housing starts and permits at 8:30 a.m. ET, a second consecutive weak reading would pressure the entire homebuilder group
- Order-to-delivery ratio in Q4: if new orders track below 20,000, a third delivery cut in fiscal 2027 becomes the base case
- Incentive rate trajectory: any move back toward 14% (the Q4 2025 level) signals the demand problem is deepening, not stabilizing
- Analyst EPS revisions for FY27, the fiscal 2027 recovery thesis is the only fundamental support for the stock at current levels
Bottom Line
The $1.23 adjusted EPS versus $1.29 expected is a miss, but it is not the story. The housing industry continues to face a structural shortage of homes in many markets, but the near-term economics of producing and financing those homes have become more difficult. Lennar is navigating that tension by leaning on incentives and volume discipline, and construction cost per square foot declined 6% year over year while cycle time improved to 116 days from 126 days, but those efficiency gains cannot outrun a 9% order decline.
The stock moves on guidance because guidance tells you where demand is headed. Right now, it is headed lower. The real question for LEN is not whether this quarter was bad. It was. The question is whether 80,000 homes delivered in 2026 becomes the floor or a waypoint on the way down.