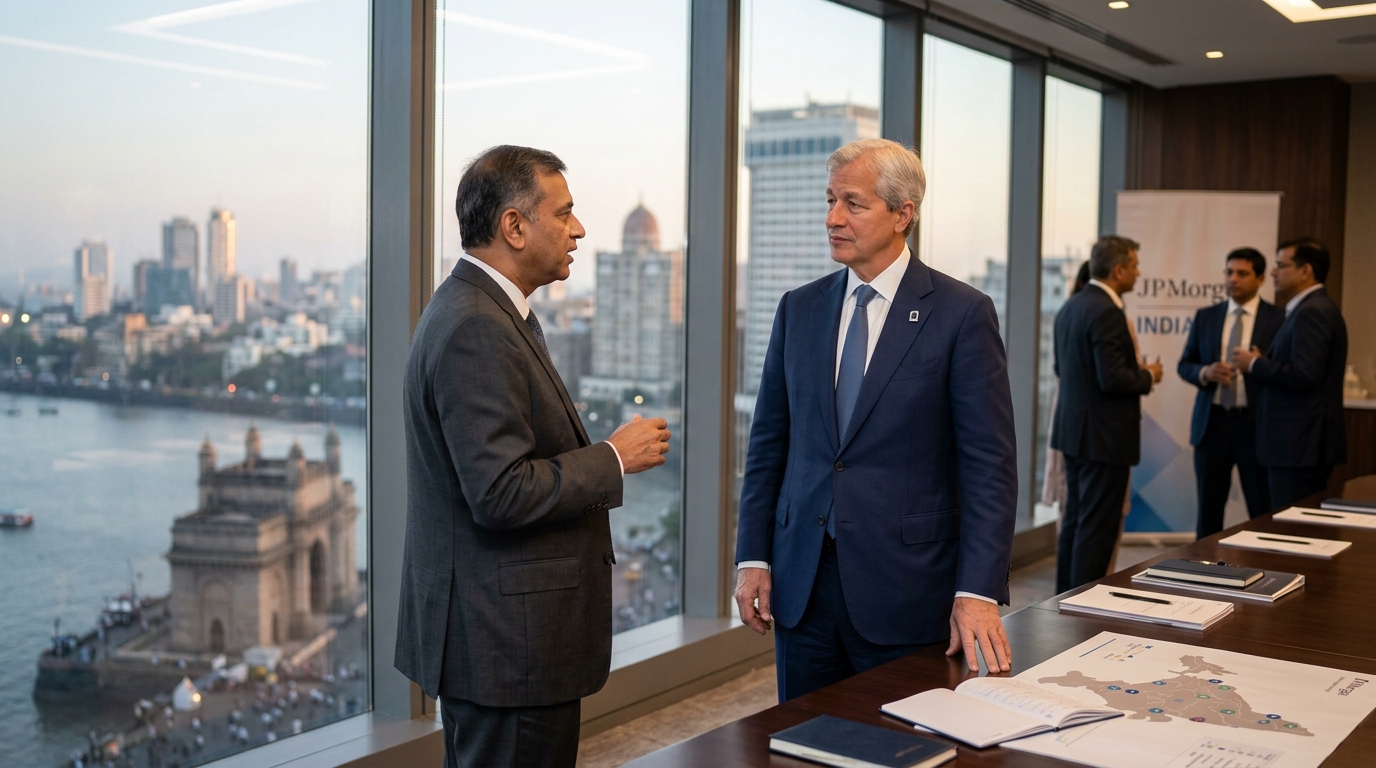
Jamie Dimon does not travel to emerging markets for symbolic gestures. When the JPMorgan Chase CEO headed to India this week as the Wall Street giant ramps up its push into a country where it expects a further boom in deals, the trip carried operational intent. Dimon attended JPMorgan’s 11th annual India conference in Mumbai, meeting executives from India’s top conglomerates. At the same time, India’s Finance Minister Nirmala Sitharaman was also present at the 11th edition of the J.P. Morgan India Investor Conference in Mumbai. That is not a routine roadshow. It is a statement of institutional priority.
The Business
JPMorgan’s Q1 2026 profit rose 13% to $16.5 billion as investment banking fees jumped 28% and markets revenue rose 20%. Merger advisory fees specifically rose 82% from the year-ago quarter, while equity underwriting fees climbed 46%. Global M&A announcements totaled about $2.8 trillion in the first half of 2026, according to LSEG data cited by Reuters, and JPMorgan said its pipeline remained robust. The bank is not merely riding that wave; it is directing it. Reuters reported that JPMorgan remained the global investment-banking revenue leader.
India sits at the center of the next chapter. JPMorgan was the biggest arranger of IPOs in India this year, with one of its senior bankers calling India one of the few emerging markets offering strong growth. India’s proceeds from initial public offerings in 2026 may hit a record for a third consecutive year, with a strong pipeline and buoyant investor demand supporting momentum.
Why Wall Street Is Paying Attention
The geopolitical context strengthens the case. Qatar’s sovereign wealth fund is targeting a $20 billion partnership with JPMorgan Asset Management spanning public and private markets in equities and credit. The strategic partnership includes a $15 billion public equities mandate and a $5 billion private markets investment initiative focused on supporting established middle-market companies across the U.S. That deal lands alongside the India push, reinforcing the picture of a bank actively expanding its asset management footprint on multiple fronts simultaneously.
The strongest positive for JPMorgan is that the Q3 outlook suggests its capital-markets momentum is continuing rather than merely reflecting a one-quarter spike. A mid-to-high-teens increase in both investment banking fees and markets revenue would extend the rapid growth already achieved in Q2.
What’s Driving the Opportunity
JPM trades around $352, carrying a market capitalization of roughly $948 billion, at a price-to-earnings ratio of about 15. For the dominant global investment bank, still generating fee growth at 28% year over year, that multiple is far from demanding. According to widely tracked analyst surveys, JPM carries a Buy consensus rating as of September 22, 2026. The Q3 earnings call, scheduled for October 13, arrives with expectations already elevated. A beat on investment banking fees, combined with positive India-related pipeline commentary, could be the catalyst that closes the gap to the 52-week high of about $366.50.
What Could Go Wrong
Dimon himself handed critics their best argument. Global investors remain broadly positive about India’s prospects, though inconsistent application of tax rules remains a concern, he said in an interview Tuesday. He added: “I get a lot of complaints from companies about paying more tax on a deal than they expected.” Foreign investors have pulled about $17.6 billion from Indian stocks so far this year through late September, according to Reuters. That outflow is not trivial. If India’s regulatory environment does not improve, the fee income Dimon is pursuing in Mumbai could take years longer to materialize than the market currently assumes.
Closer to home, JPMorgan raised its 2026 adjusted expense forecast to $107.5 billion in July, and flagged that the figure is market dependent. Revenue wins that get eaten by expenses are not the same as earnings wins. And succession uncertainty, with Dimon’s eventual departure still unresolved, introduces a leadership premium that is hard to quantify but real.
The Bottom Line
JPMorgan’s India play is genuine and growing, but it is not the primary reason to own JPM today. The real case is simpler: the bank is the fee-generating engine of the global capital markets cycle right now, at a valuation that does not yet fully reflect three consecutive quarters of outperformance. India is the medium-term optionality layered on top. A 15x earnings multiple on the world’s leading investment bank, with global M&A running at a historically high pace and a record IPO pipeline in the world’s fastest-growing major economy, is the actual argument. Dimon’s Mumbai trip is confirmation, not the thesis.