General Dynamics is not a company with a demand problem. It is a company with a capacity problem, and for active traders, that distinction changes everything about how the position should be sized and timed.
- Q2 2026 revenue: $14.1B, up 8.1% year-over-year; diluted EPS of $4.24, up 13.4%, beating consensus by $0.28
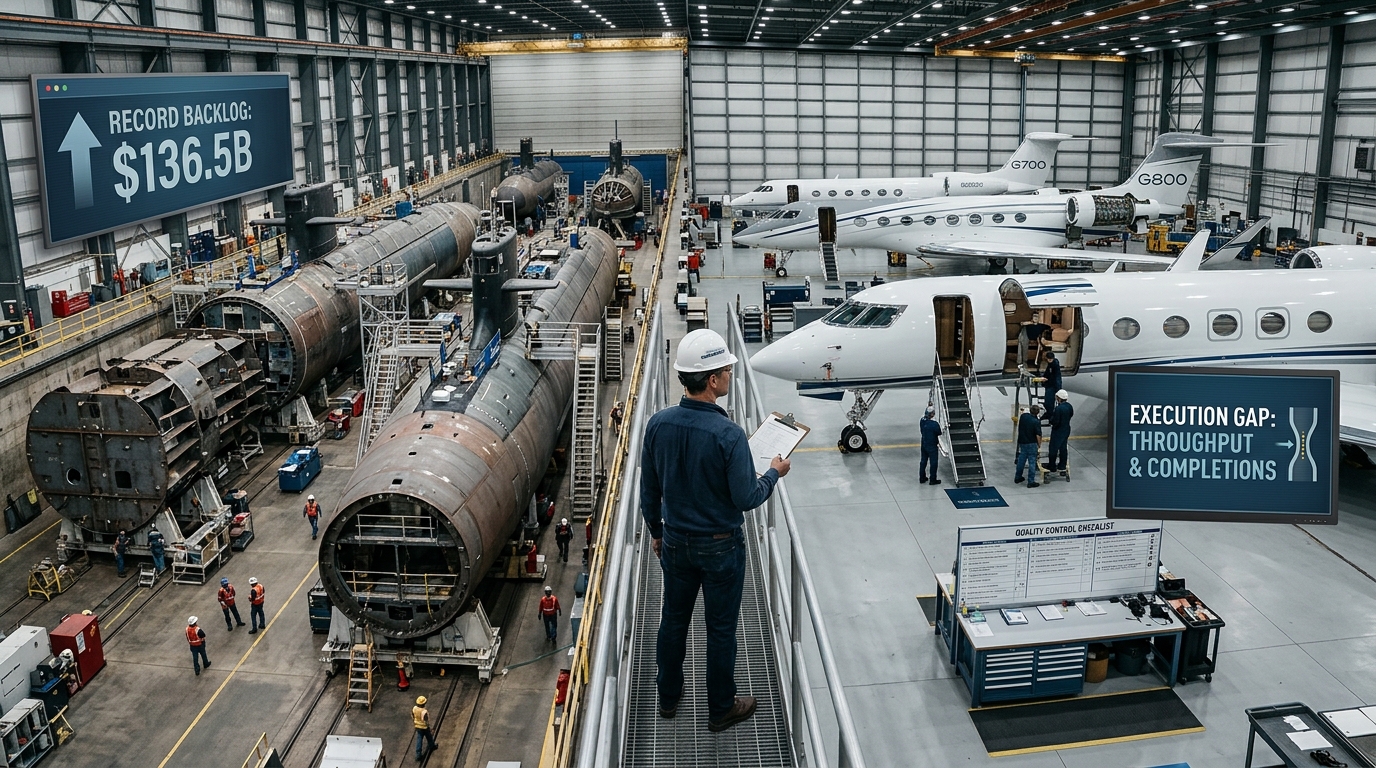
- Record backlog of $136.5B at quarter-end, up 32% year-over-year, with a company-wide book-to-bill of 1.4-to-1
- Electric Boat awarded $71.6B in July for 14 submarines: $29.5B for five Columbia-class and $42.1B for nine Virginia-class hulls
- Aerospace segment posted $3.5B in revenue, up 15.1%, and $510M in operating earnings at a 14.5% margin
- Marine Systems revenue $4.7B, up 10.4%; operating earnings $342M, up 17.5%
- September 2026 contract activity added a $230M Hammerhead anti-submarine mine award and a $194M SLCM-N fire control modification
- Full-year 2026 guidance raised to roughly $55.7B in revenue and EPS of $16.80 to $16.90; BofA carries a $450 price target
Market Context
Defense budgets across NATO members have shifted from political aspiration to contractual reality, and the U.S. submarine industrial base is absorbing the bulk of that capital. The $76.6B Navy award announced July 29 was described by congressional observers as one of the largest shipbuilding contract actions in modern American history. For GD, it arrived the same day Q2 earnings printed, compressing two catalysts into a single session. The stock closed at $380.96 that day.
The macro backdrop matters here: interest rates remain elevated, and long-duration defense programs typically price well in that environment because multi-year government contracts provide revenue visibility that most sectors cannot match. With full-year revenue guided to $55.7B and EPS of $16.80 to $16.90, GD trades at roughly 22 times forward earnings against a backlog that represents nearly 2.5 years of current revenue.
Segment Breakdown
Marine Systems is the segment to watch. Revenue of $4.7B in Q2 was up 10.4% year-over-year, and full-year Marine guidance sits at approximately $18B, compared with roughly $15.6B guided for 2025. That is a step-change in scale, driven almost entirely by Columbia and Virginia-class construction ramp. Operating margin at 7.4% is the constraint: submarine programs carry lower near-term margins than Aerospace, which dilutes the consolidated margin picture even as revenue accelerates.
Aerospace delivered the cleaner quarter. Gulfstream put up $3.5B in revenue, a 15.1% increase, on 41 aircraft deliveries. Operating margin reached 14.5%, with operating earnings up 26.6% to $510M. Aerospace backlog closed Q2 at $24B, up 20% year-over-year, with orders of $5.28B yielding a 1.5-to-1 book-to-bill. The G800’s entry into service in mid-2025 is the primary driver; order books for both the G700 and G800 now stretch into mid-2028.
Combat Systems posted a 2.1-to-1 book-to-bill in Q2, the strongest across any segment, fueled by allied armored vehicle demand in Europe. Margins dipped 30 basis points year-over-year on program mix, a dynamic traders should watch as the Army’s recapitalization cycle reduces domestic vehicle volume.
Financial Breakdown
GD’s Q1 2026 book-to-bill was 2.0-to-1 on $26B in orders, with backlog at $131B. By Q2, that figure climbed to $136.5B, up 32% year-over-year. Total estimated contract value, including unexercised options and unfunded IDIQ work, stood at approximately $188B as of Q1. The September 2026 contract additions, including the $230M Hammerhead HHEE award and $194M SLCM-N fire control modification, continue layering near-term funded work into Mission Systems specifically, a unit that often trades below the radar relative to Electric Boat and Gulfstream.
Operating cash flow reached $4B in the first half of 2026, converting at 162% of net earnings in Q2. The company paid $429M in dividends in Q2 alone, with the quarterly dividend now at $1.59 per share. Capital allocation is disciplined: $234M in Q2 capex against $1.9B in operating cash flow leaves significant room for continued debt reduction and shareholder returns.
The analyst community is broadly constructive. BofA raised its target to $450 post-Q2. The consensus across 24 analysts sits near $401, with the high-end at $450 and the low at $308. EPS estimates for full-year 2026 center around $16.80 to $16.90, with 2027 expected to accelerate as Marine throughput improves.
Technical Framework
GD sold off from $393 to $380 on Q2 earnings day, a pattern consistent with buy-the-rumor, sell-the-news dynamics after a large dual catalyst. The $380 level proved a short-lived floor; watch the $375 area as near-term support if broader defense rotation pauses. The 52-week high sits near $400. A sustained close above that level on volume would signal institutional re-accumulation ahead of Q3 earnings, expected late October.
Volume patterns around the July 29 submarine contract announcement were elevated. Traders who missed that entry should focus on whether the $380 to $390 range holds through September. The stock has delivered a 24% return over the trailing twelve months; momentum is intact but the near-term risk-reward is tighter after that run.
Scenario Modeling
Bull Case
Marine Systems accelerates submarine delivery cadence in the second half of 2026 as supply chain sequence-critical material deliveries, up 65% year-over-year in Q2, sustain their trajectory. Gulfstream hits 160 deliveries for the year. Full-year EPS reaches the top of guidance at $16.90. GD re-rates toward BofA’s $450 target on backlog conversion visibility into 2027 and 2028.
Base Case
Revenue lands near $55.7B with EPS in the $16.80 to $16.90 range. Marine margin stays near 7.4%, capping multiple expansion. The stock consolidates in the $385 to $410 range through year-end, with Q3 earnings the next meaningful catalyst. Analyst consensus holds near $401.
Bear Case
Single-source supply chain disruptions slow Electric Boat throughput, pushing Marine margin below 7%. Gulfstream completions slip on supplier bottlenecks, a risk flagged explicitly in Q2 commentary. Full-year EPS lands closer to $16.40, the stock revisits the $355 to $360 range, and the premium multiple compresses toward the defense sector average near 19 times forward earnings.
Active Trader Framework
The core positioning question is whether GD’s backlog growth is being accurately priced as revenue, not just as optionality. At current levels, the market is paying for the orders but discounting execution risk. That spread is the opportunity. Traders with a multi-quarter horizon should define risk around the $375 support level, roughly 2% below the post-earnings consolidation range. Volatility expectations are moderate: defense names rarely see single-session moves above 5% outside earnings or major policy shocks. GD’s beta near 0.5 makes it a lower-volatility way to hold exposure to the submarine build cycle and premium aviation demand simultaneously. Position sizing should account for Q3 earnings as the next binary event, where Marine throughput data will either validate or challenge the bull thesis.
Conclusion
General Dynamics enters Q4 2026 with the largest backlog in its history, a raised full-year outlook, and a contract pipeline that extends visibility well into the next decade. The Hammerhead award in September, the SLCM-N modification, and the historic Electric Boat submarine contracts all reinforce the same signal: demand is not the risk. Throughput is. Disciplined traders focus on that distinction. Preparation around Q3 earnings and Marine segment margin trends will matter more than reacting to headline contract announcements that the market has already partially priced.