September 26, 2026
Bonus Content: What Separates a Real Recovery From a Dead-Cat Bounce
Dear Reader,
I’m Matt McCall.
I recommended Nvidia when it traded around $6 a share. And after decades of tracking breakthrough technologies, I’ve learned one lesson the hard way:
The biggest danger often appears when investors stop separating a real technology from every company selling its story.
That is where I believe AI stands as Q4 begins.
Most investors are still asking whether the AI bubble will burst… or whether the boom is just getting started.
My answer is more urgent:
Both can happen at once.
See why I believe the AI market is splitting in two
We watched this same split happen after the dot-com mania.
Pets.com disappeared. Amazon survived. Webvan collapsed. Nvidia went on to become one of the most valuable companies on Earth.
The internet was real. But the prices attached to many internet stocks were not.
When the Nasdaq finally broke, it fell 77%. I am not predicting that every AI stock will suffer the same fate. I am saying the market can punish the wrong side brutally while a small group of productive businesses keeps building value.
And the gap is already becoming visible.
One robotics business at the center of my research recently introduced a new platform built to move AI from the lab into industrial operations. Its parent company also reported $100 million in quarterly Robotics revenue, a fifth straight quarter of sequential growth, and 33.4% year-over-year segment growth.
That is measurable work – not another chatbot demo or distant promise.
Meanwhile, three hyped companies on my avoid list depend on the market continuing to value the story more highly than the underlying economics.
That is the part I would not ignore as Q4 begins.
Watch the warning signs I believe investors are missing
I have laid out the full case in my Great AI Shock presentation.
You will see the historical pattern I believe is repeating, the warning signs I am watching, and why I believe physical AI sits on the stronger side of the split.
One badly mispriced holding can erase years of gains before investors realize the market has changed its rules.
To your wealth,
Matt McCall, Head Innovations Strategist
Monument Traders Alliance
P.S. If you own a broad technology or AI fund, you may hold one of these vulnerable names without ever choosing it yourself. I believe this is the moment to look under the hood – before the market does it for you. Watch my briefing before it is too late.
What Separates a Real Recovery From a Dead-Cat Bounce
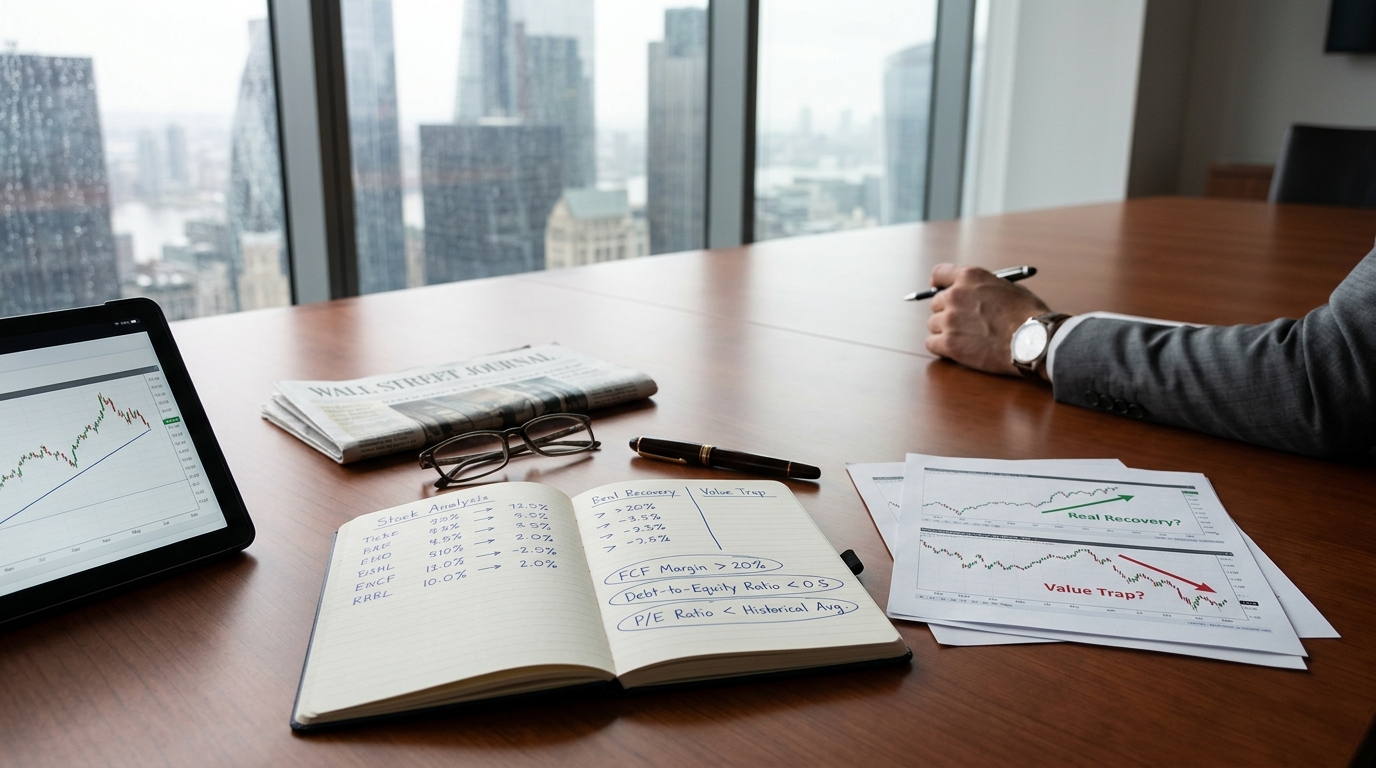
After June’s correction snapped months of uninterrupted gains, investors were left with two distinct populations of stocks: those that were marked down and those that were structurally impaired. The price chart cannot tell you which is which. Three metrics can.
Free Cash Flow Margin: The 20% Line
Free cash flow is what remains after a business pays for operations and capital expenditures. That residual cash funds buybacks, debt reduction, dividends, or reinvestment. It also determines which companies can weather a downturn without tapping capital markets at the worst possible moment.
Research from Alpha Architect spanning four decades found that EBITDA-to-enterprise value ranked as the strongest valuation signal among common metrics, with free cash flow to enterprise value close behind. The practical implication is that both metrics filter toward the same cluster of durable businesses.
AppLovin is a clear current illustration. AppLovin reported $5.48 billion in revenue in 2025, with about $4.0 billion in free cash flow, a margin a bit above 70%. In Q2 2026, the company’s adjusted EBITDA margin was about 83%, while its operating margin was in the high-70s.
Companies clearing a 20% free cash flow margin threshold entering June’s pullback have recovered materially faster than those below it. The threshold is not arbitrary. At 20%, a business generates enough internal cash to self-fund growth and absorb a revenue slowdown without immediately diluting shareholders or adding debt at elevated rates.
Revenue Growth: The Canary in the Mine
A depressed stock price is not the same as a broken business. The easiest way to tell the difference is the revenue line.
As of mid-September, dozens of stocks in broad U.S. and Canada coverage universes were trading at 52-week lows, including multiple S&P 500 members. Two of the most prominent names were PepsiCo and McDonald’s. Neither is structurally destroyed, but the distinction matters.
PepsiCo’s revenue was still growing year over year on a trailing basis even as the stock fell more than 8% over the prior month. That is a company being re-rated by the market, not one losing its business. McDonald’s, by contrast, posted U.S. comparable sales growth of 0.8% in Q2 2026.
The revenue line draws that distinction cleanly. A company growing revenue during a correction is borrowing time from the market. One that enters a correction already contracting is in structural decline, and any subsequent bounce is unlikely to hold.
Leverage: Who the Rate Environment Is Punishing
The third filter is debt coverage relative to earnings power. It has become the most consequential screen of 2026.
The 10-year Treasury yield eased to 5.17% on September 25, 2026 after briefly trading higher, with borrowing costs at levels not seen since 2007. Markets have been assigning elevated odds of another 25-basis-point hike at the Fed’s next meeting. For heavily leveraged companies, that is not a tail risk. It is a current and rising interest burden compressing free cash flow at exactly the moment the stock price has already dropped.
The pattern is consistent: debt-funded dividend payers with thin coverage ratios, companies that refinanced at low rates and now face a wall of maturities, businesses where margins were already compressing before the rate cycle turned. Each fails the screen for the same reason. The math closes off the recovery before it begins.
Framing the Opportunity Correctly
S&P 500 earnings saw a 53% year-over-year increase in Q2 2026, with 78% of companies beating EPS estimates, according to S&P Global Market Intelligence. That aggregate strength is not a reason to buy the 52-week low list indiscriminately. It is a reason to be precise.
When the broad market posts one of its strongest earnings quarters on record, a company that missed badly or guided lower has a company-specific problem. The correction did not create that problem. It revealed it.
Run free cash flow margin, year-over-year revenue growth, and debt coverage against every name on the 52-week low list. The ones that pass all three are recoveries. The ones that fail even one are something else entirely, and should be evaluated accordingly.