October 8, 2026
Bonus Content: PepsiCo’s North America Volume Problem Is the Only Number
Ian Cooper here,
For the longest time…
I thought successful options trading required:
- ❌ Staring at charts all day
- ❌ Learning 100 different strategies
- ❌ Taking huge risks
- ❌ “Predicting” the market perfectly
And honestly?
That belief nearly cost me everything.
I was overwhelmed, confused, and constantly second-guessing every trade.
Then I discovered something that completely changed the game…
A surprisingly SIMPLE options setup that helped me stop overthinking and start trading with clarity.
No complicated indicators.
No endless market analysis.
No “Wall Street genius” required.
Just a straightforward approach almost anyone can learn.
That’s why I just released this FREE report:
“The Simple Path To Success With Options”
Inside, you’ll discover:
- ✔ The #1 mistake rookie options traders make
- ✔ A simple & repeatable trade setup
- ✔ Step-by-step trade blueprints you can copy tonight
- ✔ How to ignore the noise and focus on bigger opportunities
👉 Get your free copy here now.
In your corner,
Ian Cooper
2026 TradeWins.com. All Rights Reserved. Privacy Policy | Disclaimer | Terms and Conditions | Contact Us
NOTICE: Auto-trading, or any broker or advisor-directed type of trading, is not supported or endorsed by Ian Cooper. The information provided by Ian Cooper in its various materials, including trading recommendations, newsletters and educational publications is not customized or personalized for any particular person or risk profile. Past results are not necessarily indicative of future results. Results presented can vary and may not be typical for all subscribers. There are substantial risks involved with investing in the stock and options market, including the risk of total loss. You should only trade or invest “risk capital” – funds you can afford to lose.
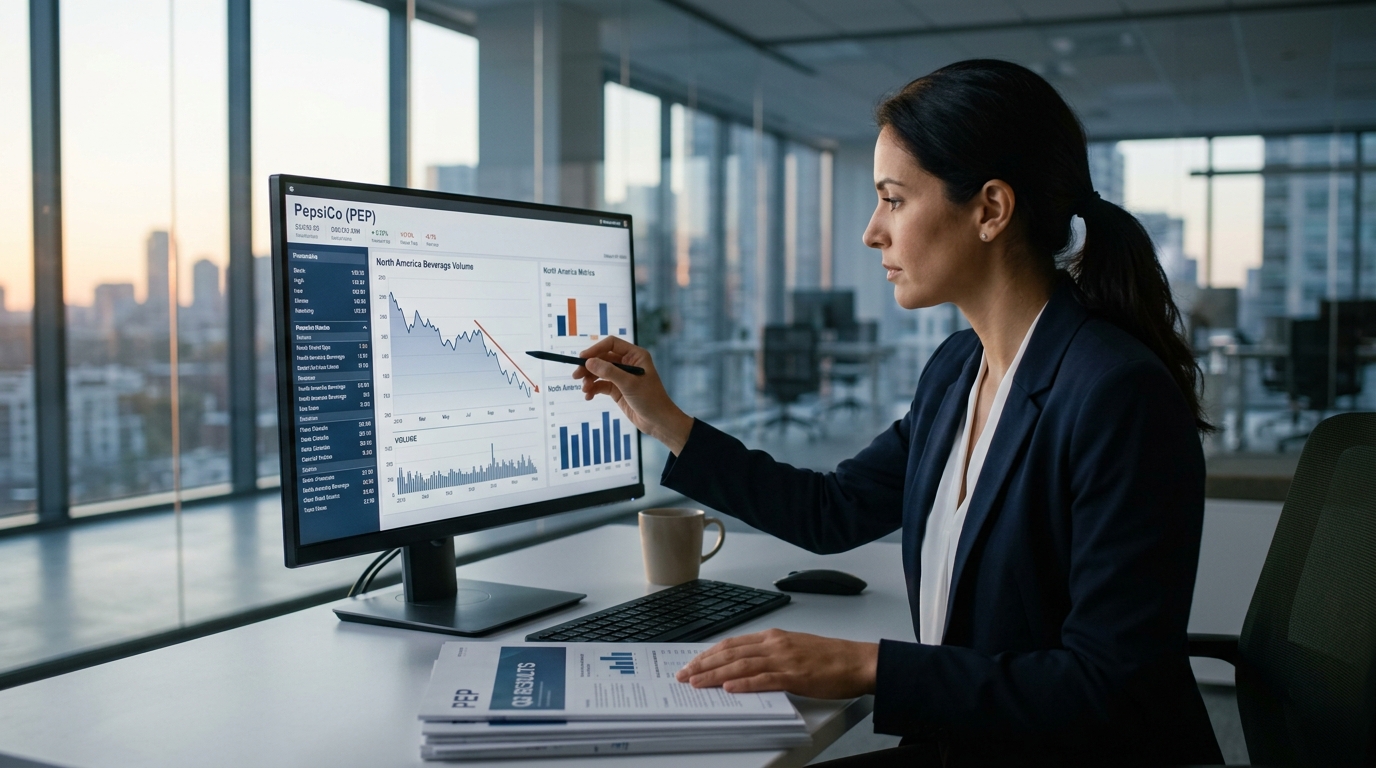
PepsiCo’s North America Volume Problem Is the Only Number
PepsiCo dropped its third-quarter 2026 results at 6:00 a.m. ET this morning, with the analyst call underway at 8:15 a.m. The stock enters the day at roughly $123.73, its weakest close since 2020, after falling about 12% year-to-date. Whatever the headline numbers say, the market’s attention is already one level deeper: North American volume.
Analyst Targets
- UBS: Buy, $145 (cut from $159, Oct. 2)
- J.P. Morgan: Neutral, $138 (downgraded from Overweight, $170, Sept. 29)
- Deutsche Bank: Hold, $138 (downgraded from Buy, $155, Sept. 28)
- Barclays: Equal-Weight, $133 (cut from $142, Oct. 1)
- Evercore ISI: In-Line, $135 (cut from $150, Sept. 30)
- RBC Capital: Sector Perform, $150 (cut from $161, Oct. 6)
- Consensus (24 analysts): Hold, average target about $148.64
The Setup Heading Into Q3
Consensus stood at $2.30 of core EPS on approximately $24.98 billion of revenue. Year-over-year, that EPS figure represents a gain of one cent. The bar could not be lower. Which makes the volume line inside the report the real verdict.
In Q2, PepsiCo posted core EPS of $2.20, a penny light of the $2.21 estimate. The stock fell more than 3% that day. The specific wound: North America organic revenues edged down 0.5%, PepsiCo Foods North America net revenue fell 2% due largely to lower effective net pricing, and Beverages North America posted 1% organic revenue growth while organic volume declined 4%. Meanwhile, international operations powered ahead, on pace to top $40 billion in annual revenue with operating margin expanding roughly one percentage point in the quarter.
The divergence between a world-class international business and a structurally challenged domestic one is what pushed the multiple down and the stock toward a six-year low.
What the Market Is Actually Pricing
J.P. Morgan’s downgrade last month cited a stalled Frito-Lay recovery: ingredient and packaging changes have not materially moved the sales needle, and the firm expects North America Foods trends to stay subdued while higher costs offset productivity savings. Deutsche Bank’s Steve Powers echoed that view, flagging lower confidence in any near-term domestic recovery. The options market was pricing an implied move of roughly 3.54%, or about $4.45 in either direction, ahead of the report.
A headline EPS beat changes nothing if Frito-Lay North America volumes are flat or negative again. Conversely, even modest positive volume without a material margin step-down would likely force a reassessment across the Street.
Macro and Industry Context
The consumer backdrop is genuinely difficult. Tight household budgets and sustained inflationary pressure have pushed shoppers toward private-label snacks and value formats, weakening category demand for branded convenient foods. PepsiCo has responded with affordability initiatives and innovation, but the results in North America have been inconsistent: Q1 showed tentative volume improvement, Q2 gave most of it back.
PepsiCo also expected tariff refund claims to add roughly one percentage point to full-year EPS growth, with much of that benefit landing in Q3. If that flows through cleanly, it provides a meaningful earnings cushion even if North American volume disappoints again.
Forward Scenarios
Bull: North America Foods volume turns positive, Beverages volume decline narrows, and management reaffirms 2% to 4% full-year organic revenue growth. Tariff refunds register in the EPS line. PEP reclaims the $135 to $140 zone quickly. The Hold consensus begins to see upgrades.
Base: A marginal EPS beat alongside flat-to-slightly-negative North America volumes. Management holds guidance but signals results will trend toward the low end of the EPS range. Stock stabilizes near current levels; the debate continues into Q4.
Bear: North America volumes disappoint again, pricing power remains absent, and guidance is trimmed. The stock tests below $120, the lowest level since early 2020, and additional downgrades follow.
Technical Overlay
PEP closed at $123.73 on Tuesday, touching a new 52-week low of $123.47. The 52-week high is $171.48. The RSI registered around 22, deeply in oversold territory. There is no meaningful technical support between here and the 2020 lows near $116 to $118. Any decisive volume-driven recovery from today’s report would need to clear the $130 to $133 zone before analysts at Barclays and TD Cowen would begin to revisit their targets.
Bottom Line
The $2.30 EPS consensus is almost irrelevant in isolation. PepsiCo’s international operations are performing well, the dividend remains rock-solid at about a 4.7% yield with 54 consecutive years of growth, and the stock trades at less than 15x forward earnings. None of that has mattered to the market for months. What will matter today is one number: Frito-Lay North America volume. Positive is the catalyst. Flat is a holding pattern. Negative is another leg down from a six-year low.