Analyst Targets
- DZ Bank – Sell, $100 (analyst Markus Leistner; initiated August 21)
- Evercore ISI – Outperform, $275 (raised from $230 on October 16)
- Morgan Stanley – Overweight, $300 (reiterated October 14; bull case $600)
- Raymond James – Strong Buy, $800 (maintained October 14)
- UBS – Buy, $210 (reiterated; projects Q3 beat)
- Street consensus – Buy, average target about $221
The Backdrop
SpaceX will post financial and operational results for the third quarter of 2026 after market close on Tuesday, October 20, 2026, and host a webcast at 3:30 PM CT. Heading into that release, three stories have converged in the past two weeks to define what investors are actually pricing.
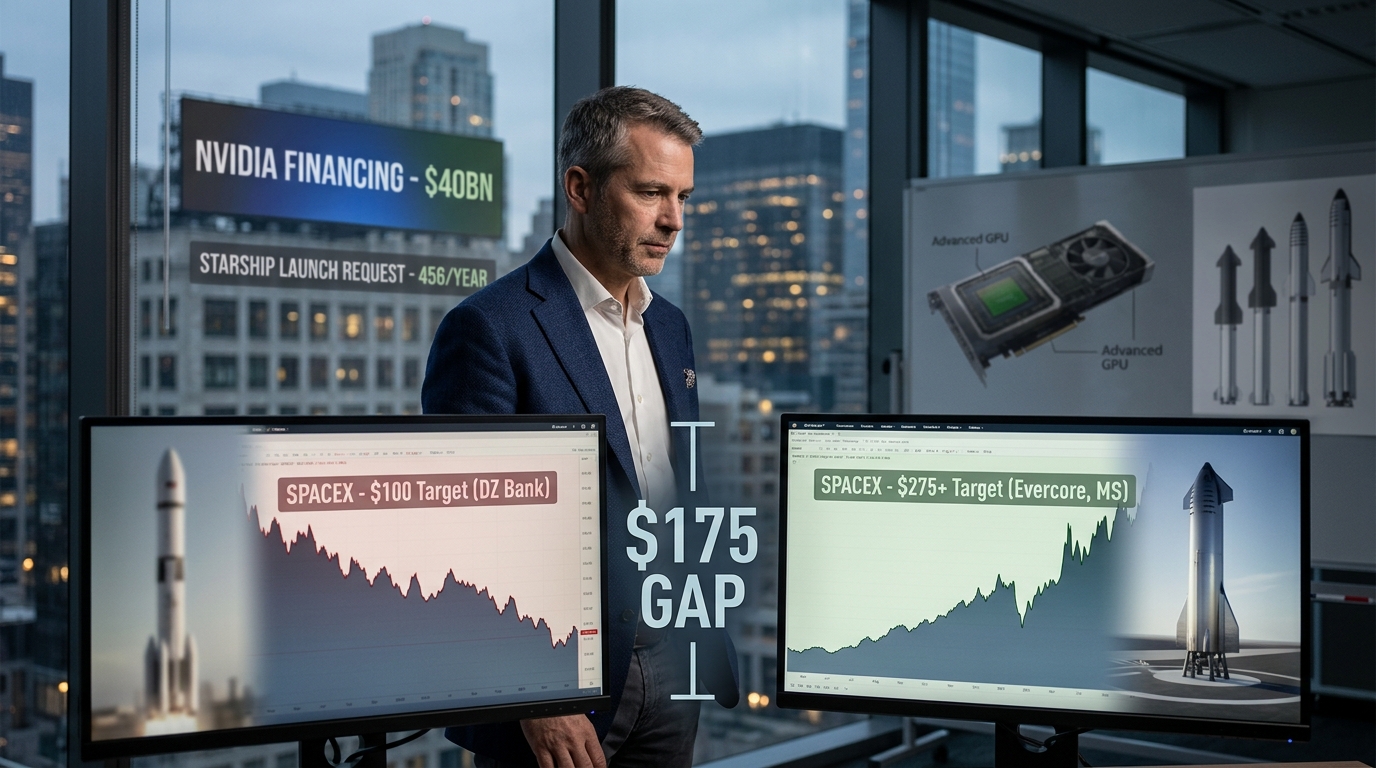
First: Financial Times reported that Apollo Global Management and several banks are in discussions with SpaceX about financing tied to a roughly $40 billion Nvidia GPU purchase. The report described a structure that could include about $10 billion in bank loans and $30 billion in investment-grade debt.
Second: SpaceX is seeking FAA approval for up to 456 Starship launches and 912 landings per year from its Starbase facility at Boca Chica, Texas. The FAA’s current review framework describes Phase 1 as up to 100 annual launches and 200 annual landings, and Phase 2 as up to 456 launches and 912 annual landings.
Third: Evercore ISI analyst Kutgun Maral reiterated an Outperform rating and raised his price target to $275 from $230 on Thursday, October 16, 2026. Simultaneously, DZ Bank’s $100 Sell sits unmoved. That $175 spread is not noise. It maps a genuine disagreement about whether SpaceX’s capital intensity is an investment or a trap.
Company Profile
This will be SpaceX’s second earnings report as a public company. The rocket and satellite business went public on June 12, 2026, listing on Nasdaq under the ticker SPCX at $135 per share. Three segments now define the business: Space (launch services), Connectivity (Starlink), and AI (compute infrastructure, Grok, and X). In Q2 2026, Connectivity was 54.9% of $7,814 million of revenue, AI 32.8%, and Space 12.3%. The mix is moving fast.
The Q2 Baseline and Q3 Expectations
In Q2, revenue was $7.8 billion, up 92% from $4.1 billion, with a net loss of $541 million and adjusted EBITDA of $3.5 billion, up 191%. All three segments beat consensus. The problem investors focused on: capital expenditures were about $18.4 billion in the quarter, with about $15.8 billion tied to AI compute infrastructure. Revenue of $7.8 billion against capex of about $18.4 billion is not a sustainable ratio. The Q3 report is the first real evidence of whether management intends to close it.
UBS has estimated Q3 revenue at $13.8 billion and adjusted EBITDA at $7.5 billion, both ahead of Wall Street estimates. UBS also expects the AI business to lead the quarter with $7.6 billion in revenue, helped by an expansion of its agreement with Anthropic.
The Structural Debate
DZ Bank analyst Markus Leistner’s Sell rating and $100 fair value centers on a growing tension: SpaceX has enormous long-term opportunities, but turning those ambitions into businesses could require extraordinary amounts of capital. Some sell-side estimates frame the external financing need through the 2030s as extremely large, but the exact figure varies widely by model assumptions.
Morgan Stanley’s Adam Jonas argues SpaceX trades at a discount to other large-cap AI-related companies when its expected growth is taken into account, describing it as “cheap and getting cheaper” on a growth-adjusted basis. Evercore ISI has argued SpaceX could exit 2026 near a $104 billion annualized revenue pace. TD Cowen expects SpaceX’s AI compute leasing revenue to jump to $66 billion in 2027 and $133 billion in 2028. If that trajectory holds, today’s capital burn looks rational. If it does not, $100 is defensible.
Bull / Base / Bear
Bull: Q3 revenue clears $14 billion, the AI segment reaches profitability, and SpaceX announces new compute agreements that validate the $104 billion annualized run-rate thesis. The FAA’s Phase 1 approval accelerates, the $40 billion GPU financing effort closes on investment-grade terms, and SPCX re-rates toward Morgan Stanley’s $300.
Base: Revenue comes in near the low-$13 billion area, capex stays elevated, and management reiterates the $100 billion annualized revenue target for year-end. The stock grinds sideways into the October 24 lockup expiry, when a large block of employee and early-investor shares is expected to become tradable.
Bear: AI revenue disappoints, capex expands without proportional contract announcements, and the financing scale of the GPU effort spooks credit markets. The stock revisits its 52-week low. The 52-week range is $104.83 to $225.64.
Technical Overlay
SPCX closed at $148.62 on Thursday, October 15, and has been trading around a roughly $2.0 trillion market cap. The stock has retreated from its early-October high above $163 and sits between the IPO price of $135 and a cluster of analyst support near $150. The near-term level to watch is $150. A sustained move below that could increase selling pressure, while a recovery above $160 to $175 would indicate improving momentum.
Bottom Line
Tuesday’s number matters less than the Q4 compute contract pipeline and capex guidance for 2027. Evercore ISI has flagged the possibility of materially higher capex in 2027, arguing projected EBITDA growth could outweigh the increase. That is the bet. DZ Bank’s Leistner thinks that EBITDA growth will not come fast enough to justify balance sheet expansion. Morgan Stanley’s Jonas thinks the market is mispricing the company’s position in physical AI infrastructure.
Both arguments are internally consistent. What breaks the stalemate is whether AI compute revenue, Starlink subscriber growth, and the Starship cadence scale together rather than sequentially. Tuesday afternoon is the first data point that touches all three at once.