Editor’s Note: On September 24, Elon Musk dropped a bombshell announcement, and nobody noticed. Famed Wall Street investor Louis Navellier saw it – and he says he hasn’t been this excited since he recommended Google in 2004. The full story below…
Few people know this story…
In January 2019, Elon Musk broke ground on a Tesla plant in Shanghai. By the end of the year, it was delivering cars.
That’s how fast he moves. And along the way, he’s minted countless “Teslanaires”… and more than 4,400 SpaceX millionaires.
But what he quietly announced just before noon on September 24 could become his boldest and most lucrative move yet.
It hinges on the fastest-growing part of his SpaceX empire…
And the little-known supplier powering its explosive growth.
Elon has $912 billion riding on it.
That’s how big he thinks this could be.
But here’s why buying SpaceX or even Tesla is NOT the best way to play it
Regards,
Louis Navellier
Senior Investment Analyst, InvestorPlace
P.S. I found this stock using my Stock Grader. This proprietary system cost $9 million to build and maintain. And since 1998, it’s returned 13,126% in back tests. That’s 13X the market. It’s now flashing bullish on this critical SpaceX supplier. Click here to get its name and ticker now.
Defense Giants Report This Week. The War Hasn’t Paid Yet.
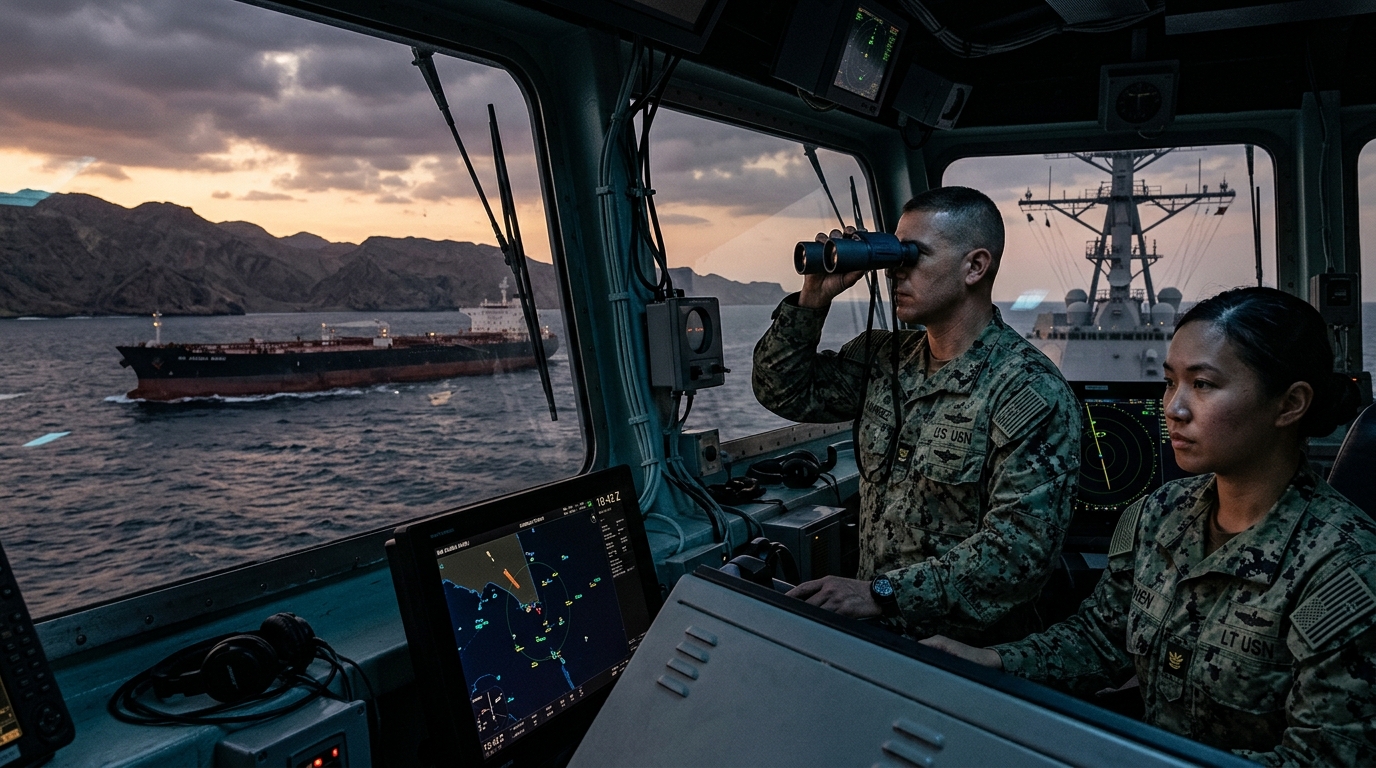
Eight months into the US-Iran war, the Strait of Hormuz is under sustained attack and American defense primes are reporting the most consequential quarter of the conflict. At least 10 attacks were reported in the week ending October 16, according to UK Maritime Trade Operations reporting cited by the Associated Press. Oil flows through Hormuz remain disrupted. Brent has hovered around the $105-$110 range in mid-October. The stocks that manufacture the interceptors and missiles making those numbers possible are up, but not uniformly: RTX is up in the mid-single digits year to date, while Northrop Grumman is down year to date, even as the S&P 500 is up roughly 14% so far this year.
The earnings sequence: RTX and Northrop Grumman report Tuesday, October 20, before the open. Lockheed Martin reports Thursday, October 22. Together they set the terms of the debate for the rest of the year.
The Numbers to Beat
- RTX (Oct 20): Consensus is roughly $1.78 in EPS on about $24.0 billion of revenue for the quarter, per widely published analyst consensus. Segment-level estimates can vary by source and change into the print.
- Northrop Grumman (Oct 20): Consensus is about $7.18 EPS on about $11.1 billion in revenue, based on widely published analyst aggregates.
- Lockheed Martin (Oct 22): Street consensus is roughly $7.5 EPS on about $20.4-$20.5 billion in revenue, based on widely published analyst aggregates. Full-year guidance should be read from the company’s most recent filings and earnings materials, as it can be updated quarter to quarter.
Where the War Money Is Showing Up
Lockheed’s Missiles and Fire Control segment is the clearest financial expression of the conflict. MFC sales rose 19% to about $4.1 billion in Q2, driven by production ramps for PAC-3 and THAAD. Segment profitability is strong, but the precise operating margin varies by quarter and presentation; the core point is that MFC has been a relative margin standout versus legacy problem programs. In June the US government awarded Lockheed a seven-year contract worth up to $35 billion to quadruple THAAD interceptor production. The roughly $230 billion backlog figure the company reported at mid-year does not necessarily capture every major award announced after the quarter close, including the company’s July announcement of an additional multiyear PAC-3 MSE award of up to $53.86 billion.
At RTX, the equivalent signal arrived September 28. RTX’s Raytheon unit was awarded a multiyear fixed-price incentive contract worth up to $20.7 billion for AMRAAM production, covering missiles and related components and Foreign Military Sales provisions. RTX said it nearly doubled AMRAAM production in 2025 compared with 2024. Raytheon’s Patriot, Standard Missile, and AMRAAM lines are all accelerating simultaneously, which is exactly what Q3 should confirm.
The acceleration in AMRAAM and Patriot output is happening against a documented baseline of depletion. The US has used virtually all of its long-range precision missiles during the Iran War, which is precisely why these production ramps carry strategic urgency beyond any single earnings quarter.
The Other Side of the Ledger
Revenue momentum is real. The margin question is harder.
For Northrop, the B-21 Raider’s low-rate initial production options are largely fixed-price, and the company has disclosed sizable losses tied to that phase. In its first-quarter 2026 filing, Northrop described a $157 million net unfavorable EAC adjustment on the first four LRIP lots. The company has also previously discussed remaining loss contingency accruals related to the program. Analysts expect revenues to grow faster than earnings this quarter precisely because margin recovery on B-21 is gradual, not sudden. Guidance commentary on the B-21 margin trajectory, the Sentinel ICBM schedule, and the space portfolio will be closely scrutinized.
For RTX, industry commentary has repeatedly pointed to the reality that ceiling values do not equal near-term revenue. The AMRAAM deal has been described in reporting as a provisional award, and the pace of appropriation and supply chain throughput, not headline contract value, determines when revenue hits the income statement.
Bull / Base / Bear
Bull: All three primes beat on Raytheon segment revenue and Lockheed MFC margins, guidance raises follow, and the market re-rates the group toward its conflict-adjusted peak. The PAC-3 and THAAD order flow into Q3 backlog confirms the multi-year ramp is accelerating.
Base: Revenue beats land broadly in line with the pattern of recent quarters. Northrop’s B-21 margin trajectory stays subdued, capping that stock’s reaction. RTX and Lockheed move modestly higher on clean executions. The sector stays range-bound relative to the S&P 500.
Bear: A negative EAC adjustment at Northrop’s Space or Aeronautics segment triggers a miss; RTX supply chain commentary disappoints on delivery timing; Lockheed’s fixed-price F-16 exposure surfaces another charge. The group sells off on the gap between backlog optics and near-term cash conversion.
Technical Overlay
All three stocks are trading below their March 2026 conflict highs. Earnings this week represent the most direct fundamental reset opportunity since the war began. A clean beat on Lockheed’s MFC margin should be the clearest trigger.
RTX has been through this earnings reset before. RTX’s Q2 report showed how a record $271 billion backlog can still leave the market cold if margin commentary on Raytheon’s missile lines disappoints.
Bottom Line
The core argument is this: demand for PAC-3, THAAD, and AMRAAM interceptors is running at a pace the industrial base has never attempted. The war in and around Hormuz is not abating. The contracts confirm the orders. What Q3 must demonstrate is that the supply chain is actually delivering into that demand, and that fixed-price legacy programs at Northrop are not consuming the upside before it reaches the bottom line. Backlog is the promise. This week, investors find out how much of it is becoming cash.