November 6, 2026
Bonus Content: DraftKings Is Betting $700 Million on Predictions. The Quarter Shows Why That Bet Is Expensive.
Hey Trader,
Before the market opens again, read this…
My top trader, Thomas Wood, just released a new strategy he calls Opening Bell Trades.
This simple system is designed specifically to help regular investors generate income from his #1 trade setup.
I’m talking about finding monster winners like these…
- 113% on GOOGL
- 240% on META
- 70% on CAG
- 37% on MCD
- 139% on GLD
Best of all, he looks for these trades every morning starting at 9:30 AM and by 10 he’s done.
Everything you need to know about how this works is in a free report called “The Opening Bell Trade Guide”…
Take a few seconds and download FREE right now before this link stops working.
This report won’t be free forever, so grab it now while you can.
Once it’s on your computer, you’ll have it for good-no matter what we charge other traders for it later.
No credit card required. No strings attached.
>> Get Your FREE “Opening Bell Breakouts” Trade Guide Here
This guide shows you the exact 15-minute window trade he uses, and how to spot the setups the big funds are watching.
FREE: Discover One Simple Options Trade You Can Make Each Morning – and Be Done by 10 AM.
To better trading,
Drew Day
Founder & CEO
Base Camp Trading
P.S. Inside, you’ll see why Thomas uses weekly options and how to use them to trade stocks like GOOGL, META, and TSLA with as little as $75. Go here to save a copy of the “Opening Bell Trade Guide” before its taken down.
DraftKings Is Betting $700 Million on Predictions. The Quarter Shows Why That Bet Is Expensive.
Analyst Targets
- JPMorgan: Overweight, $30 target
- Bernstein: Outperform, $27 target (cut from $29 on Nov. 3)
- Citigroup: Buy, $28 target
- Stifel: Buy, $32 target
- Truist: Buy, $26 target
- MoffettNathanson: Neutral, $22 target
The Quarter in One Sentence
DraftKings grew revenue 16% and still managed to badly miss on every number that matters.
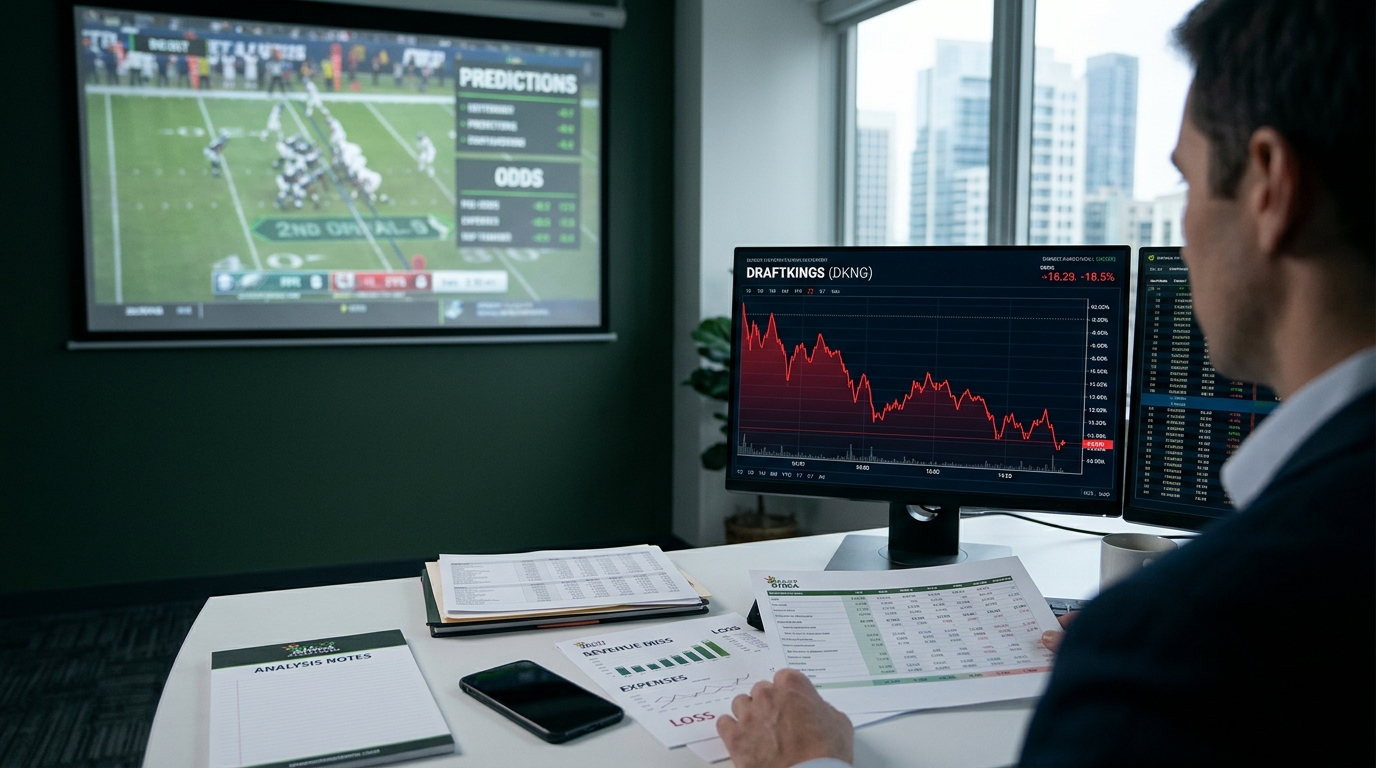
DraftKings reported third-quarter revenue of $1.329 billion, up 16% year-over-year. The problem is that revenue fell short of consensus by about $60 million. On the bottom line, the company reported EPS of -$0.70 versus the -$0.41 consensus estimate. The stock fell roughly 18% in after-hours trading. That is the number investors are sitting with this morning.
Company Profile
DraftKings is the largest U.S.-based online sportsbook operator by customer count, running mobile sports betting across 29 states, Washington, D.C., and Puerto Rico. The core business spans daily fantasy sports, iGaming, and sportsbook wagering. This year, it launched DraftKings Predictions, a federally regulated prediction markets product, which has become the defining strategic question for the company.
The Numbers
In the third quarter, Monthly Unique Payers increased 13% year-over-year and Sports Consumer Volume increased 12% year-over-year. Average revenue per MUP rose 3% to $109 in Q3, driven by the sports margin increase, but that figure came in well below the estimate cited by some analysts. DraftKings reported that its prediction markets product reached $56.8 billion in annualized total volume traded in October 2026. Predictions revenue will be immaterial in fiscal year 2026, as new customer promotions will offset the lion’s share of gross revenue generated.
On guidance: DraftKings updated its fiscal 2026 revenue guidance to a range of $6.35 billion to $6.55 billion, down from prior guidance of $6.5 billion to $6.9 billion. For the fiscal year, adjusted EBITDA is now expected in a range of $175 million to $275 million, down from a prior range of $700 million to $900 million, as the guidance includes an increased adjusted EBITDA investment in Predictions of $650 million to $700 million.
Why the Stock Is Moving
Three things hit simultaneously. The revenue miss and the EPS gap were bad enough. But the guidance cut to adjusted EBITDA is what stings most: DraftKings trimmed its fiscal year 2026 revenue guidance to a midpoint of $6.45 billion that sits below the analyst consensus, and its 2027 adjusted EBITDA outlook of $800 million to $1 billion came in well beneath what the market had been expecting.
What management is asking investors to accept is a simultaneous near-term earnings collapse and a longer-term revenue leap. Core revenue is expected to be $6.7 billion to $7.0 billion for fiscal 2027, while the company expects Predictions revenue of $650 million to $750 million. That Predictions figure is real money on paper. The question is whether the product can generate it.
Macro Context: Kalshi Just Proved the Market Is Real
The timing of this report matters. According to Kalshi’s post-election report, total trading volume on its 2026 midterms markets surpassed $2.5 billion, compared with $1.3 billion for the 2024 election cycle. Prediction markets went fully mainstream this week, which is precisely the environment DraftKings is spending to capture.
The strategic irony is that Kalshi’s midterm success validates the category DraftKings is burning cash to enter. CEO Jason Robins noted that prediction market operators are having no discernible impact on DraftKings’ Sportsbook business, which is a defensive point. The offensive point is a $750 million revenue target that now has a credible market behind it.
Forward Scenarios
Bull
Predictions customers acquired today should begin contributing meaningful gross profit going into next year, and the adjusted EBITDA investment in Predictions is expected to step down to $300 million at the midpoint. If 2027 Predictions revenue comes in at or near $750 million and the core sportsbook holds, the stock looks deeply undervalued at current levels relative to earnings power.
Base
Predictions ramps but slowly. The $650 million to $750 million revenue range proves optimistic by 20-30%, but the core business at $6.7 billion to $7.0 billion, an increase of 4% to 9% year-over-year, provides enough cash flow to absorb the miss. DKNG trades sideways as analysts reset models for a third consecutive quarter.
Bear
The downside model assumes a Predictions customer generates 20% of today’s gross profit once sports contracts disappear, which stretches payback from 18 months to 41 months. Legal risk on sports event contracts forces another investment cycle. The core business grows but cannot absorb the losses. The stock tests its 52-week low near $18.
Technical Overlay
DKNG opened 2026 at its 52-week high of $36.98 and has since shed roughly 50% of that peak value. DraftKings stock was down about 18.4% to roughly $19.20 in after-hours trading versus a 52-week trading range of $18.35 to $36.98. The $18-19 zone is now critical. A close below $18.35 would mark a new 52-week low with no technical floor in sight. Near-term resistance sits at the pre-earnings close around $23.
Bottom Line
This report asks investors to absorb a poor quarter, cut guidance, and a promise denominated in a market that generated immaterial revenue in 2026. The investment logic is not irrational. More than 1.6 million customers have used DraftKings Predictions in 2026, and Kalshi’s midterm volume suggests the demand is real. But the price being paid is steep: a $650 million to $700 million adjusted EBITDA investment this year, a $300 million investment next year, and a 2027 payoff that requires prediction markets to scale on a timeline no one can confirm. The stock will recover when management can show Predictions revenue, not just volume. That clock starts now.