When Celsius Holdings reported Q3 results this morning, the headline looked clean: record third-quarter revenue of $847.2 million, up 16.8% from a year earlier, while net income reached $127.0 million versus a $61.0 million loss. Shares rose in premarket trading. The beat story writes itself.
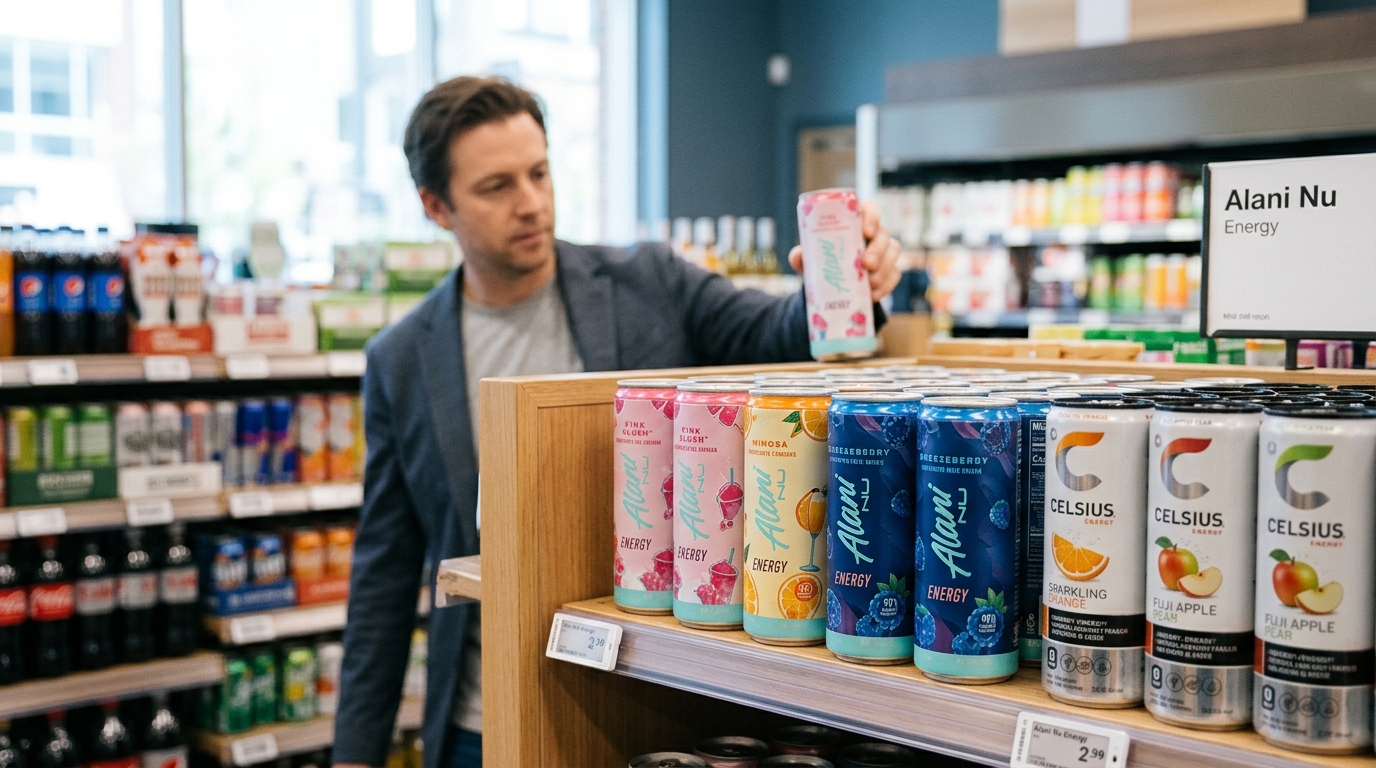
But the internal composition of that result is where the real investment question lives. Alani Nu revenue increased approximately 24% to $410.1 million, helping offset an approximately 6% decline in CELSIUS brand revenue to $356.8 million, with Rockstar Energy contributing $80.3 million. Read that again: the brand on the company’s ticker declined. The brand it acquired 19 months ago is now the largest in the portfolio and the reason the quarter worked.
Alani Nu delivered its strongest quarter to date, led by Witch’s Brew, the brand’s most successful limited-time offering (LTO). Alani Nu’s share of the U.S. RTD energy drink category in tracked channels reached approximately 9.8% in the quarter. That is not cushioning a stumble, that is a growth engine running at full throttle.
The margin picture complicates any simple bullish read. Gross profit margin decreased to 46.8% in the quarter from 51.3% in the prior-year period due to continued inflation in commodity costs, primarily aluminum and fuel, as well as a higher mix of DSD sales. On the earnings call, management said that at current diesel and aluminum levels, margin expansion has been largely offset, and it reiterated that, depending on commodity fluctuations, it would expect gross margin in the high 40s. That means the low-50s target investors held a year ago has drifted into 2027 at minimum.
On valuation, the gap between price and estimated intrinsic value is hard to ignore. CELH is trading at $30.75 per share versus a GF Value of $78.42, implying a roughly 60.8% margin of safety by GuruFocus’s methodology. That discount reflects years of multiple compression from peak, not a business in structural decline.
The forward question is whether the CELSIUS brand recovers enough to justify owning the whole platform, or whether Alani Nu ends up doing the work while the flagship idles. On the Q3 call, management said the brand has been running in the $50 million to $55 million range in weekly scanner data, and framed 2027 as a reset year where results should build through 2027 and into 2028. That is a base, not momentum. Meanwhile, management has separately stated an ambition for international to represent more than 15% of total company sales over the next five years, and it has discussed building out its international team from Dublin, with Alani Nu international launches part of the longer runway.
The unresolved tension: Celsius Holdings is trading as if its core brand is impaired, yet Alani Nu is growing fast enough that the platform as a whole keeps posting records. Aluminum and diesel are the swing variables for margins. If those costs moderate in early 2027, the gap between current prices and fair value estimates becomes hard to rationalize. If they do not, the high-40s margin floor becomes the new ceiling.