While technology stocks spent last week losing trillions, one sector went quietly about its business. Energy leads in 2026: the Energy Select Sector SPDR Fund is up about 40% year to date (as of early November), well ahead of most other sectors. Inside that move, Valero Energy has become the clearest expression of why the trade still has runway.
The Numbers Are Not Subtle
Valero reported third-quarter 2026 adjusted earnings of $23.90 per share, up 553% from $3.66 a year ago. Net income was $6.8 billion, or $23.89 per share, compared to $1.1 billion in Q3 2025. Total revenues for the quarter were $32.17 billion, essentially flat versus $32.17 billion in Q3 2025.
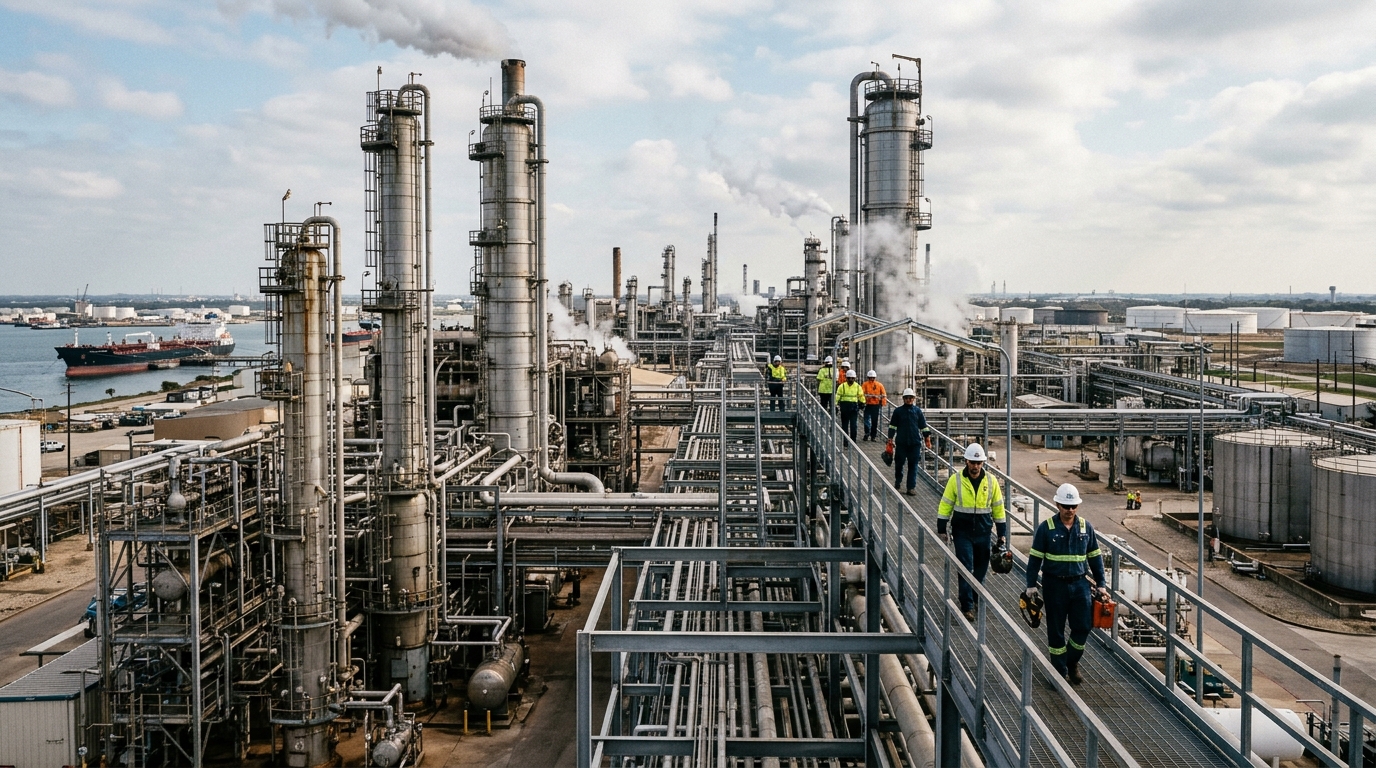
The refining segment did not just perform well. It was exceptional. Refining segment operating income rose to $8.8 billion from $1.6 billion a year ago, with throughput averaging 3.0 million barrels per day. Renewable diesel swung from an operating loss of $28 million to $353 million in operating income. Ethanol set a record quarterly production volume, averaging 4.8 million gallons per day.
Why the Margin Spike Is Not Fully Priced In
Valero closed November 3 at $387.65, up 125.9% over the past 12 months. That looks like a fully rewarded trade. At roughly 8 times trailing earnings on the Q3 run rate, it does not. Refiners historically trade at single-digit multiples when margins are peaking, but Valero’s situation carries structural support that pure cyclicals lack.
Adjusted net cash provided by operating activities reached $7.3 billion in the quarter. Capital investments totaled $432 million in the quarter, and Valero stockholder cash returns resulted in a payout ratio of 52% of adjusted net cash provided by operating activities. That means Valero enters Q4 with its refineries running hard, low planned downtime, and a cash machine generating far more than it needs to reinvest.
What Drives the Trade From Here
The sector rotation out of tech is channeling capital into exactly the names the market ignored during the AI bull run. Recent market commentary has pointed to leadership from energy and other more defensive groups as tech and communication services lose relative strength. Valero sits at the center of that shift: a capital-light, cash-heavy refining business that benefits from tight fuel supply and benefits further when institutional money rotates out of growth.
The Risk
Refining margins are not guaranteed. The same freight dislocations and supply constraints that pushed Gulf Coast margins to generational highs can reverse if crude supply normalizes or global demand softens. VLO’s valuation appears low at current earnings levels, but cyclicality and potential normalization of refining margins warrant caution against extrapolating peak earnings indefinitely. A demand shock or a sudden unwinding of the crude-to-product spread would hit the stock before it hits the income statement.
The Bottom Line
Valero posted the most profitable quarter in its history and generated $7.3 billion of adjusted operating cash flow. The energy sector is the market’s leading sector by a wide margin in 2026, and institutional capital keeps arriving. For investors looking for a profitable, cash-generating business at a valuation the market has not yet corrected, Valero is the clearest argument in the energy trade today.