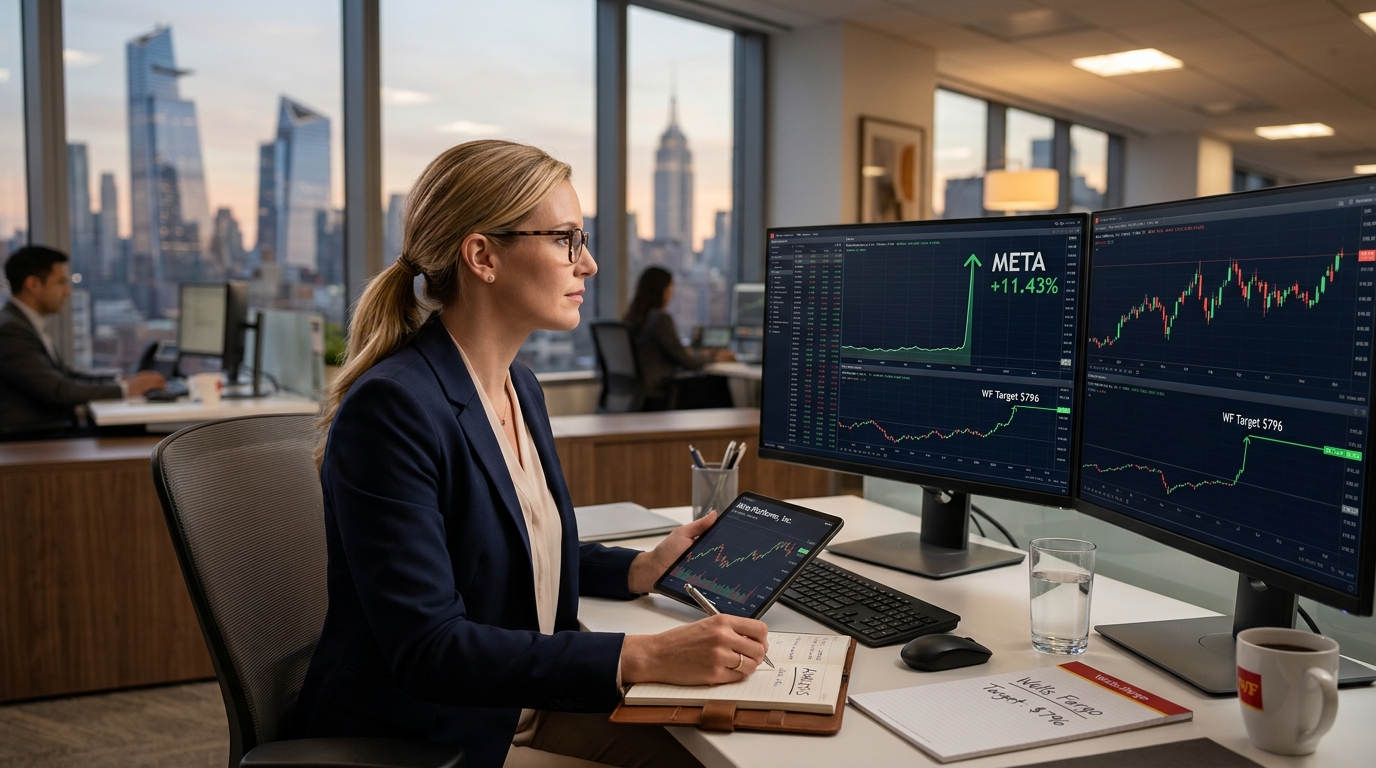
Wells Fargo analyst Ken Gawrelski raised his price target on Meta Platforms to $796 from $640 Monday morning, keeping an Overweight rating and telling clients the company “now has a story to tell” on AI. By the close, the market had already moved past the target. Meta closed at $741.25 on September 21, up 11.43% from the previous session. Shares jumped to about $741, adding roughly $150 billion to the company’s market value and marking one of its biggest one-day gains in years.
The catalyst was concrete: Muse reached No. 1 on Apple’s U.S. App Store on September 18, about 10 days after its launch, according to Sensor Tower data cited by multiple outlets. In less than two weeks, Muse became one of the most popular interactive AI agents available, surpassing OpenAI’s ChatGPT, Anthropic’s Claude, and others for downloads in its category on Apple’s iOS App Store. Apptopia estimates Muse generated 1.8 million iOS downloads in the United States and Canada during its first 12 days, compared with 1.3 million for ChatGPT over the comparable period.
What Muse Is
Muse launched earlier this month as a personal AI agent capable of sending emails, booking travel, filling out forms, and making purchases on a user’s behalf. It runs on a dedicated virtual machine in Meta’s cloud and is powered by Muse Spark, Meta’s AI model family. Meta introduced paid plans at $20 per month and $100 per month above a free tier, the first direct consumer revenue line attached to its AI buildout.
Amazon has already moved to contain it. Amazon blocked Muse from its retail site after Meta declined a request to remove the bot. That friction underscores what Muse actually threatens: a checkout layer that bypasses other retailers entirely.
The Revenue Math
This is where the re-rating gets harder to defend at current prices. Even if 10 million users subscribe to Muse, it accounts for only about 0.28% of Meta’s 3.6 billion daily active people across its family of apps. A $20 power-plan subscription would generate $200 million in revenue per month, or $2.4 billion annually. Against Meta’s Q2 2026 revenue of $60.8 billion, with advertising still the overwhelming majority of that total, subscription revenue alone cannot carry the valuation at this stage.
Wells Fargo’s Ken Gawrelski raised his target to $796, hoping that many users will need to opt for a paid subscription due to heavy usage. But Oppenheimer has gone further: it estimates Meta would need 115 million Muse subscribers at $20 per month to generate roughly $27.5 billion in AI subscription revenue, a figure that is a long way from the early download base so far.
Muse is a brand-new product that requires consumers to learn what an agent can do for them, and any meaningful paid adoption could take time. The near-term cost pressure is real too: in Q2 2026, Meta said costs and expenses increased 55% year over year, operating income fell about 8%, and operating margin declined to 31% from 43%.
Technical Overlay
Meta stock closed at $741.25, well above all major daily moving averages. Daily RSI14 hit 77.8 and hourly RSI14 reached 78.73, both firmly in overbought territory. The daily pivot sits at $724.57, with R1 resistance at $769.56 and S1 support at $696.15. Monday’s session spanned more than $70 from open to intraday high; a consolidation toward the $700 area before Meta Connect would be the healthiest outcome for bulls.
Bull / Base / Bear
- Bull: Meta Connect (September 23-24) delivers hard Muse engagement data. If paid conversion rates follow, Wells Fargo’s $796 target gets the earnings support it needs from the 2027 consensus EPS estimate of $33.94.
- Base: Muse maintains its App Store rank and Connect reassures on engagement without hard subscription numbers. Stock consolidates in the $720-$760 range through Q3 earnings, expected around October 28.
- Bear: The key unanswered question is what share of Muse users convert to paid subscriptions and whether subscription revenue outweighs the compute costs required to serve them. A light Connect with no paid-tier data, combined with an RSI above 77, creates a quick path back toward $680.
What Investors Should Watch
Meta’s Muse assistant must deliver concrete usage metrics at Connect to justify Wells Fargo’s raised target, with Q3 earnings expected around October 28. The specific numbers that matter: paid subscriber counts, average revenue per user on the $20 and $100 tiers, and any signal on free-to-paid conversion rates. Analyst revisions in the week after Connect could move the stock as much as the event itself.
Bottom Line
Monday’s 11% move was a credibility trade, not a revenue trade. The market paid for proof that consumer AI agents can actually attract users at scale, and Muse delivered that proof. What it has not delivered is a subscription revenue line large enough to justify a roughly $150 billion single-session gain against Meta’s 2026 capital expenditure guidance of $130 billion to $145 billion. The gap between download momentum and subscription economics is exactly what Meta Connect must begin to close. Until it does, the stock is priced for execution, not exploration.