September 25, 2026
Bonus Content: Eaton’s $24.1 Billion Backlog Is a Factory Problem Now
Dear Reader,
Most AI stocks can tell a great story.
One hidden company can point to $100 million in quarterly Robotics revenue.
The same business has posted five consecutive quarters of sequential growth. Robotics revenue also rose 33.4% from the year-earlier period.
And on September 14, its robotics operation introduced a new platform built to move physical AI from the lab into industrial operations.
The launch has happened. The revenue trend is already in motion. Yet most investors still do not know the stock.
See why I believe physical AI could survive the coming split by clicking here.
I’m Matt McCall, a former Fox Business host who called the 2009 market bottom and later recommended Nvidia at around $6 a share. My research has also identified 51 investments that went on to rise at least 1,000%.
I mention that because the pattern in front of us feels familiar: a real technological revolution surrounded by companies whose prices may be running far ahead of their economics.
On one side: expensive promises, crowded trades and three hyped names I believe investors should avoid.
On the other: physical-AI businesses already building machines, winning customers and producing measurable revenue.
Learn about why I believe AI is splitting between hype and real-world utility for free.
The concealed company owns the business described in my research as the world leader in collaborative robots, with a cited 31% share of the cobot market.
Amazon provides the customer-side proof. Its Vulcan robot can use touch to pick and stow goods, and the company in my research supplies an important component.
The source analysis estimates a roughly $400 million revenue opportunity if Amazon’s plan unfolds as expected – enough to more than double the company’s prior-year robotics revenue.
Nvidia provides the technology-side proof through its Isaac robotics platform.
The market will not announce when it separates productive AI from hype. By then, vulnerable names may already be falling.
That is why I put together my Great AI Shock presentation now.
To your wealth,
Matt McCall, Head Innovations Strategist
Monument Traders Alliance
P.S. The most important part may be recognizing the split before it becomes obvious.
Eaton’s $24.1 Billion Backlog Is a Factory Problem Now
The Bottleneck Has Shifted
Eaton’s demand story is no longer in doubt. The question sitting in front of ETN shareholders is whether the company can physically manufacture its way through one of the largest infrastructure backlogs in its history before competitors or construction delays chip away at the opportunity.
Total backlog stood at approximately $24.1 billion as of June 30, 2026, with roughly 71% of that targeted for delivery within the next twelve months. That delivery wall is precisely where execution risk concentrates.
What Is Actually Driving the Queue
Eaton said Electrical Americas data-center orders were up approximately 240% in Q1, while data-center revenue rose about 50% year over year. Order velocity at that scale creates a specific industrial problem: the equipment Eaton builds, medium-voltage switchgear, transformers, power distribution gear, cannot be assembled overnight. Lead times on some components stretch years.
Its position benefits from high material constraints on grain-oriented electrical steel and years-long delivery times. Those constraints are a moat, but they are also a ceiling on how quickly Eaton can convert backlog into revenue.
The Factory Response
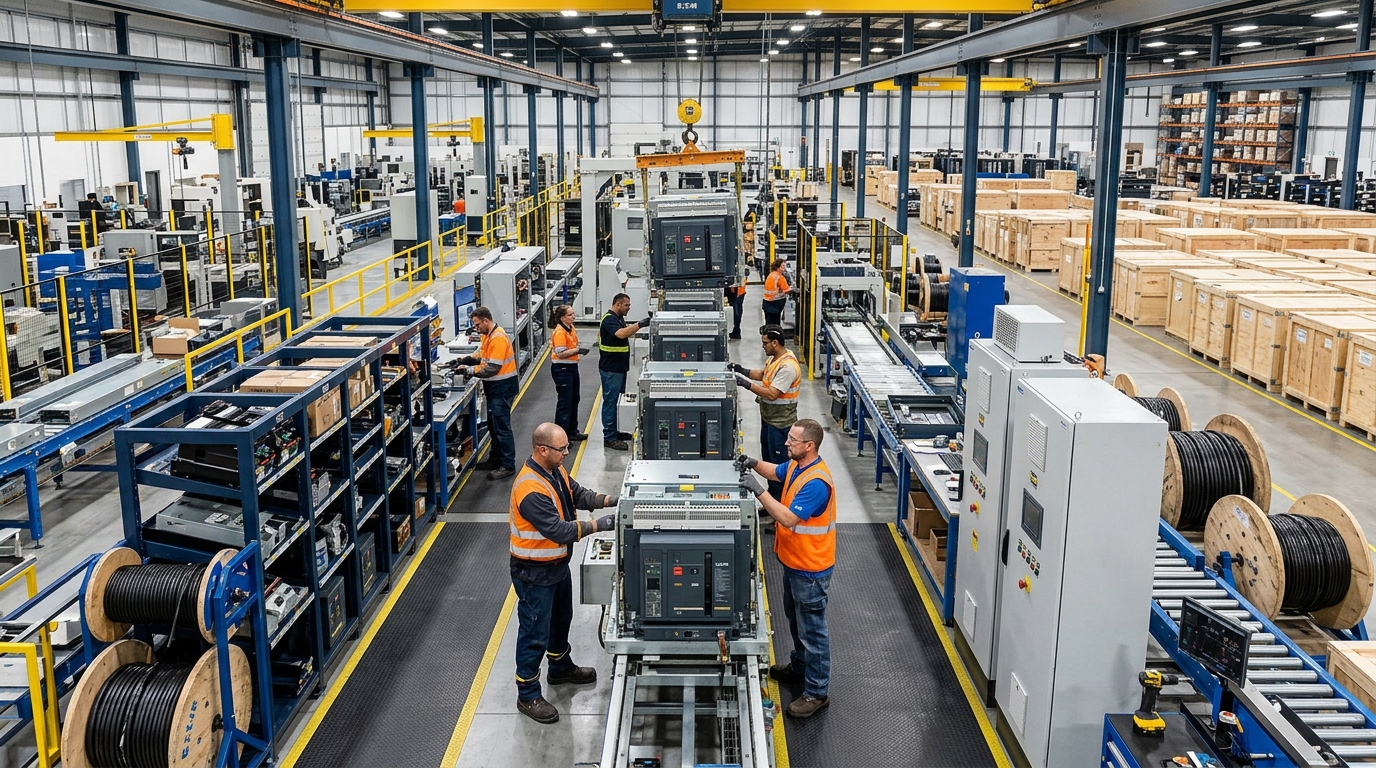
Management is spending aggressively to close the gap. On April 8, Eaton announced an investment of over $30 million in a new 370,000-square-foot manufacturing facility near Omaha, Nebraska to expand U.S. production of medium-voltage switchgear. That facility is expected to begin production in the first half of 2027.
Eaton has also committed more than $242 million to a new one-million-square-foot facility in North Little Rock, Arkansas, aiming to expand Fibrebond custom electrical enclosure capacity and create over 1,200 manufacturing and operations jobs. Fibrebond, acquired for approximately $1.4 billion, supplies pre-integrated modular power infrastructure for hyperscale and AI data center buildouts, exactly the prefabricated, rapid-deployment format hyperscalers now demand.
Margin Under Pressure While the Plants Ramp
Eaton achieved record Q2 2026 sales of $8.53 billion, up 21% year over year, with 14% organic growth, and adjusted EPS of $3.15, a Q2 record. The revenue line is clean. Margins are more complicated.
Gross profit margin fell to 33.5% in Q2 2026, down from 37.0% in Q2 2025, driven mainly by inflation and increased amortization from acquisitions. New factories cost money before they produce. That drag is visible now, and it is the precise trade-off management has chosen: accept near-term compression to lock in multi-year backlog at scale.
Full-year 2026 organic growth is now expected at 11–13%, with segment margins of 24.1–24.5% and adjusted EPS guidance raised to $13.40–$13.60.
The Real Risk the Market Is Pricing
The central question for ETN is not whether data center demand is real, but whether Eaton can capture that demand at the margins management has promised by 2030. A 228-gigawatt data center backlog sounds enormous until you map it against newly ramped factories, acquisition integration timelines, and grain-oriented electrical steel supply constraints that no one company controls.
Bulls point to a book-to-bill of 1.2 across Electrical segments and a 43% year-over-year backlog increase as proof the funnel stays full regardless of short-term delivery friction. Bears note that Vertiv is not standing still, and any capacity slip on Fibrebond’s prefab lines hands hyperscalers a reason to diversify their supplier base. Eaton’s edge is real. Keeping it requires factories to run on schedule, not just orders to keep arriving.