Editor’s Note: What is the final phase of Elon Musk’s master plan – and why could it mean a massive payday for anyone taking advantage of this ONE ticker? Our friend Larry Benedict, a hedge fund legend who made over $274 million for his clients, says he has the answer. Click here to see the details.
Dear Reader,
After PayPal. After Tesla. After SpaceX.
Elon Musk is now preparing to execute the final phase of one of the most ambitious plans in history.
Click here to discover exactly what he’s planning – and the ONE ticker that could benefit the most.
According to Larry Benedict – the man who delivered a 279% return on cash in 2025 while the S&P returned just 15% – when the “Final Phase of Elon’s Master Plan” is triggered, it could move more money than anything Elon has ever done before.
We’re talking billions – potentially trillions – of dollars flowing into a single ticker.
It’s not Tesla. It’s not SpaceX. It’s not crypto, or AI, or anything Wall Street is currently talking about.
But when the “Final Phase” kicks in, Larry believes it’s positioned to capture the surge.
He’s revealing the name and ticker today – completely free.
Regards,
Lauren Wingfield
Managing Editor, The Opportunistic Trader
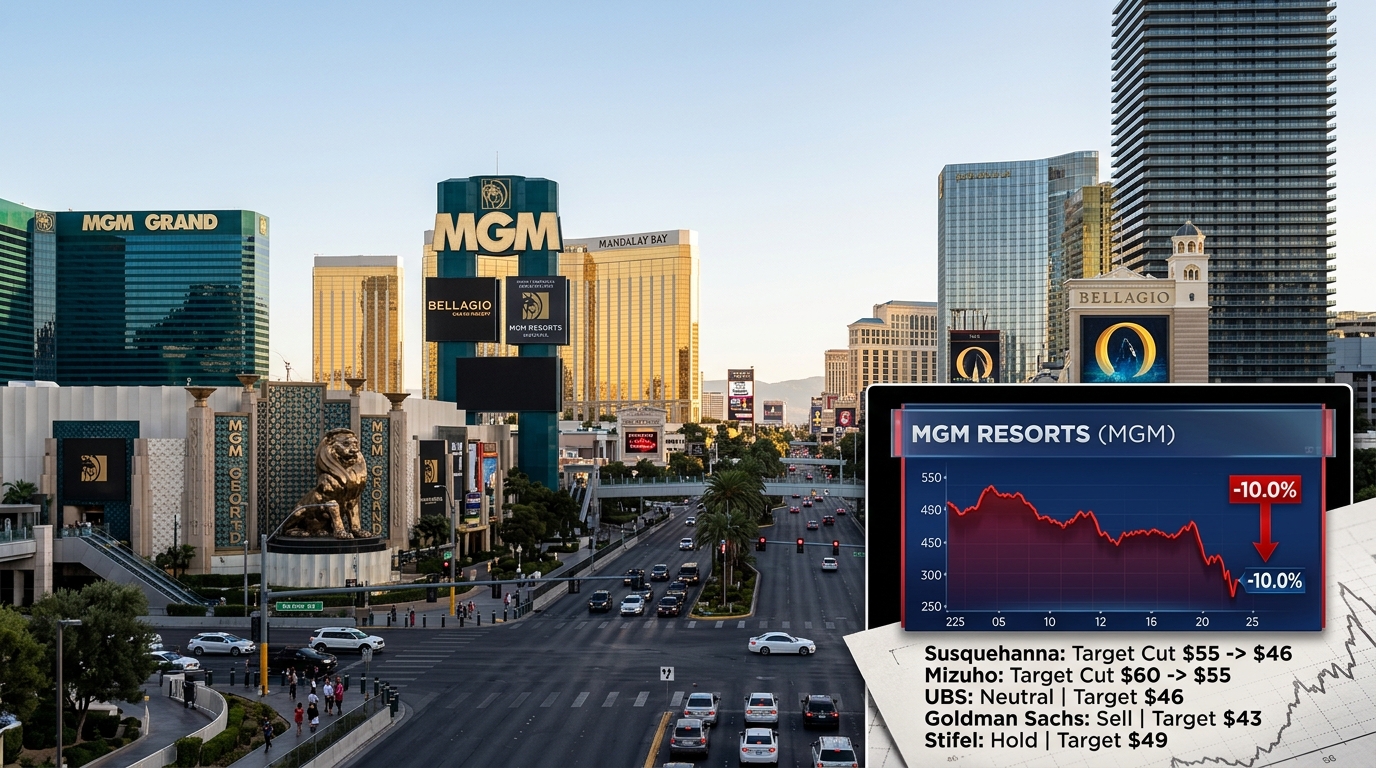
MGM Resorts Falls 10% After Barry Diller Drops $48.30 Bid
Analyst Targets
- Susquehanna: Positive | Target cut from $55 to $46 (September 24)
- Mizuho: Outperform | Target cut from $60 to $55 (September 24)
- UBS: Neutral | Target $46 (cut from $50, September 11)
- Goldman Sachs: Sell | Target $43 (reiterated July 15)
- Stifel: Hold | Target $49
- Consensus (MarketBeat): Moderate Buy | Average target $52.24
What Happened
People Incorporated withdrew its proposal to acquire all public shares of MGM Resorts International on Tuesday night, ending a months-long effort to take the casino operator private after having offered $48.30 per share in cash on June 1. The bid valued MGM at more than $18 billion.
Shares of MGM fell about 9% to 11% on Thursday as investors removed the expected deal premium.
Diller said People continues to hold its 66.8 million MGM shares and that the company remains confident in MGM’s management and prospects. That is roughly a 27% stake held with no acquisition path attached to it, which is the part of this that matters most to what comes next.
Company Profile
MGM Resorts operates 30 hotel and casino destinations globally and owns 50% of BetMGM, a sports betting and online gaming platform, in a joint venture with U.K. gambling operator Entain. Revenue is split across Las Vegas Strip Resorts, regional operations, MGM China, and digital. The Strip portfolio is the crown asset. BetMGM is the growth asset. The debate right now is whether either is worth $48.30 without Diller as buyer of last resort.
The Numbers
In Q2 2026, MGM achieved adjusted earnings of $0.59 per share on revenue of $4.5 billion, exceeding analyst projections of $0.56 per share and $4.44 billion in sales.
The quarter still reflected a mixed operating backdrop, including about 1% consolidated revenue growth.
For the full fiscal year, analysts expect MGM’s EPS to decline to about $2.05 on a diluted basis.
Why the Stock Is Moving
The bid was the price. Once the bid disappeared, so did the premium that had been embedded in MGM since June.
Neither company disclosed specific reasons for why negotiations failed to produce an agreement. Diller’s language was careful: he said the mix was not coming together in the way he had hoped, and that People would not pursue taking the company private at this time. “At this time” is doing real work in that sentence.
The decision caused investors to remove the expected deal premium and reassess MGM based on its operating performance alone. That reassessment, on a stock with modest top-line growth and a softer EPS outlook, is not flattering.
Macro and Industry Context
MGM is not operating in isolation. The casino sector has seen significant recent activity, including Caesars Entertainment’s $17.6 billion agreement to be acquired by Fertitta Entertainment. Consolidation is clearly the sector’s preferred direction. MGM now stands as the major Strip operator without a transaction catalyst, while peers are reshaping around it.
BetMGM provides digital growth optionality alongside the physical portfolio, with the hybrid model hedging macro risk: physical resorts provide asset backing and cash flow stability while the online platform captures the ongoing shift from land-based to digital gambling. That story is real. It is also priced with considerably more skepticism today than it was 48 hours ago.
Bull / Base / Bear
Bull: People Incorporated returns with a revised structure. At 66.8 million shares, Diller has every incentive to see MGM rerated higher. A minority stake transaction, merger of equals, or asset-level deal could revive a premium. Mizuho’s $55 target reflects this possibility.
Base: MGM trades in the low-to-mid $30s as the market digests the premium removal. Standalone fundamentals support a floor near $34 to $37. The MarketBeat consensus target of $52.24 implies significant upside over 12 months, but near-term multiple compression is the more immediate reality.
Bear: Las Vegas demand softens, BetMGM loses ground against DraftKings, and People’s 27% stake hangs over the multiple as other potential acquirers hesitate. Goldman Sachs already carries a sell rating with a $43 target, set before Thursday’s drop. On a standalone basis, that target now looks less aggressive.
Technical Overlay
MGM sold off sharply into Thursday, with the stock trading down in the mid-$30s after the withdrawal. The gap through $37 is significant. That level, the pre-bid floor from early June, now becomes resistance. A recovery above $37 on volume would signal the market is beginning to price in a revised Diller transaction. A failure to hold $33 opens a path toward the low $30s.
Bottom Line
The question for MGM is no longer whether the $48.30 deal was fair. That conversation is over. The question is whether People Incorporated’s 66.8 million shares, sitting without a stated acquisition plan, act as a floor under the stock or an overhang on it. Diller left the door open to future dealmaking. That language is not nothing. But until a new structure materializes, MGM trades on modest Strip revenue growth, a declining EPS outlook, and a digital business fighting for share in a competitive market. Analysts are cutting targets, not estimates. That distinction tells you where the next move comes from.