Dan Schulman has been Verizon’s CEO for just over one year. In that time he oversaw the best postpaid quarter since 2019, two guidance raises, a $25 billion buyback authorization, and a stock that touched a 52-week high above $51. Monday morning, before U.S. markets open, investors find out whether the third quarter held it all together.
Wall Street consensus for Q3 sits at about $34.77 billion in revenue and $1.27 in EPS, based on widely published analyst estimates. The comparable from a year ago was soft: Verizon reported Q3 2025 revenue of $33.8 billion, and it reported EPS of $1.17 (or $1.21 on an adjusted basis, excluding special items). On those figures, consensus implies mid-single-digit EPS growth year over year, with revenue growth closer to the low single digits. That earnings expansion, if confirmed, matters more than the revenue line. It signals that Schulman’s cost overhaul, not just the subscriber push, is producing real operating leverage.
Are the Subscribers Earned or Bought?
Postpaid phone net additions were 616,000 in Q4 2025, and the consumer segment specifically added 551,000, a 50% improvement year over year that beat AT&T’s 421,000 for the same period. Q1 2026 then added 55,000 postpaid phone subscribers, the first positive first-quarter result since 2013. In Q2, postpaid phone net additions were 184,000, and management said consumer postpaid phone churn fell to 0.84%, down 6 basis points year over year.
The bear case focuses on what those adds cost. After Q4, MoffettNathanson analyst Craig Moffett argued that ARPU, margins, and EBITDA were weaker even as postpaid phone net adds beat. Management’s counter is efficiency: in its Q2 2026 results materials, Verizon said cost of additions was down 15% year over year and cost of revenues down 17%, with adjusted EBITDA margin reaching a record 40.1%. Management has also pointed investors to an expectation that ARPU turns positive in Q4. Q3 will show whether that trajectory is on track or slipping.
Schulman said the 2026 subscriber target is “very doable” without having to “over utilize promotions or pricing.” Q3 is where that claim gets stress-tested. T-Mobile and AT&T both ran aggressive device promotions through the summer. If Verizon held churn below 0.84% while continuing to add accounts, Schulman’s volume-over-discounting argument stands. If churn ticked up or net adds softened materially from Q2’s 184,000, investors should ask why.
The SpaceX Variable Nobody Has Priced Yet
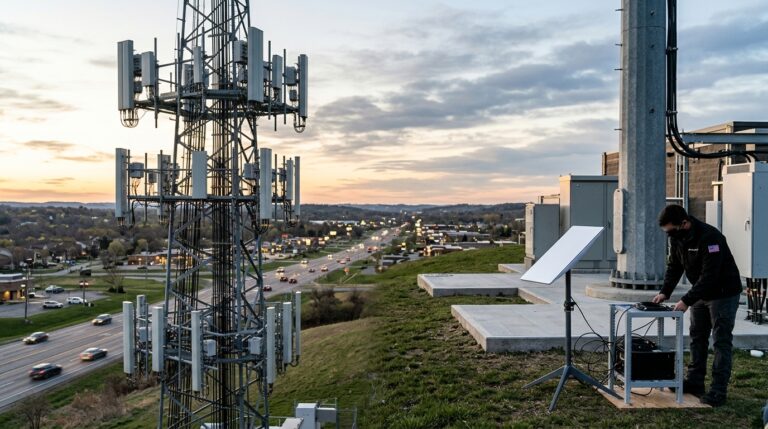
The more disruptive question arrived Wednesday evening. Bloomberg reported that SpaceX is in talks to secure at least 80,000 cell sites across the United States as it aims to become the fourth nationwide wireless carrier. The Wireless Infrastructure Association has said 158,500 purpose-built cellular towers were in operation in the U.S. in its latest annual industry statistics, meaning the number of sites SpaceX is reportedly targeting would be roughly half that total.
Bloomberg also reported that SpaceX has held discussions with major tower owners including Crown Castle and American Tower. In Friday trading, tower stocks jumped while the carriers fell, with Crown Castle up roughly 9% and American Tower about 4% at points during the session, according to widely reported market coverage. Verizon, AT&T, and T-Mobile moved the other direction. As for timing, the deal SpaceX struck for a nationwide 800 MHz spectrum portfolio is widely expected to close in the first half of 2027, subject to regulatory and other conditions. Separately, SpaceX has another spectrum purchase agreement that has been described in public filings as targeting a later closing date.
The critical nuance: nothing is signed. The reports describe talks, not leases. Tower leases are shared infrastructure, so SpaceX renting space on a tower would not displace existing Verizon tenancy. The real long-run threat is simpler: a fourth carrier with satellite backhaul, low-band spectrum, and 80,000 ground sites could compress industry pricing in a market where Verizon’s entire turnaround rests on adding subscribers without heavy discounts.
What to Watch Monday
Management has raised 2026 guidance twice year to date and now expects adjusted EPS growth of 6% to 7% and free cash flow growth of 9% to 10%, based on Verizon’s Q2 2026 guidance update. Buyback execution has accelerated, with $3.5 billion completed year to date against a full-year target now raised to up to $4.5 billion. Those are strong numbers. The question is whether Schulman’s earnings call commentary on SpaceX addresses it directly or deflects it, because the market will price whatever he says about the competitive landscape as much as the EPS itself.
Verizon heading into Q3 is not the same company it was two years ago. The balance sheet is heavier after Frontier, but EBITDA margins are higher and subscriber momentum is genuine. The SpaceX tower talks are, for now, a risk to monitor rather than a threat to price in. Monday’s call is the first opportunity to hear management quantify which of those it believes.