Bullet Summary
- H1 2026/27 capital investment hit a record £6.707 billion, up 33% year over year at actual exchange rates, driven by UK transmission and US network acceleration.
- Underlying EPS rose 22% to 36.5p; full-year guidance upgraded to 15-16% EPS growth versus the prior 13-15% range.
- Net debt climbed £4.4 billion in six months to £48.6 billion, with regulatory gearing expected to rise to about 65% by March 2027 and management still pointing to the high 60% range by 2030/31.
- National Grid agreed a $1.75 billion strategic minority investment for a 35% stake in Joulent LLC, a US contracted-power developer focused on large-load solutions for data centers and industrial customers.
- Micron’s first New York fab load has been cited at 480 MW, and a second project has been cited around the mid-500 MW range, putting early phases above 1 GW in aggregate.
- Full-year capex guidance stands at approximately £13.5 billion; net debt expected to rise roughly £4 billion more by March 2027.
The Debt-Load Trade-Off
Last week’s H1 results handed traders a genuinely uncomfortable tension. Statutory profit before tax rose 109% to £1.73 billion and underlying operating profit increased 13% to £2.591 billion. Those are headline numbers most utilities would celebrate. The complication is on the liability side of the ledger.
Net debt rose by £4.4 billion to £48.6 billion as National Grid funded its investment programme and its stake in US power developer Joulent. Net finance costs in 2026/27 are expected to be around £300 million higher than 2025/26, reflecting increased debt issuance to fund capital investment and the investment in Joulent. That is a significant drag arriving at precisely the moment the capex program is steepening.
Why the Micron Angle Matters
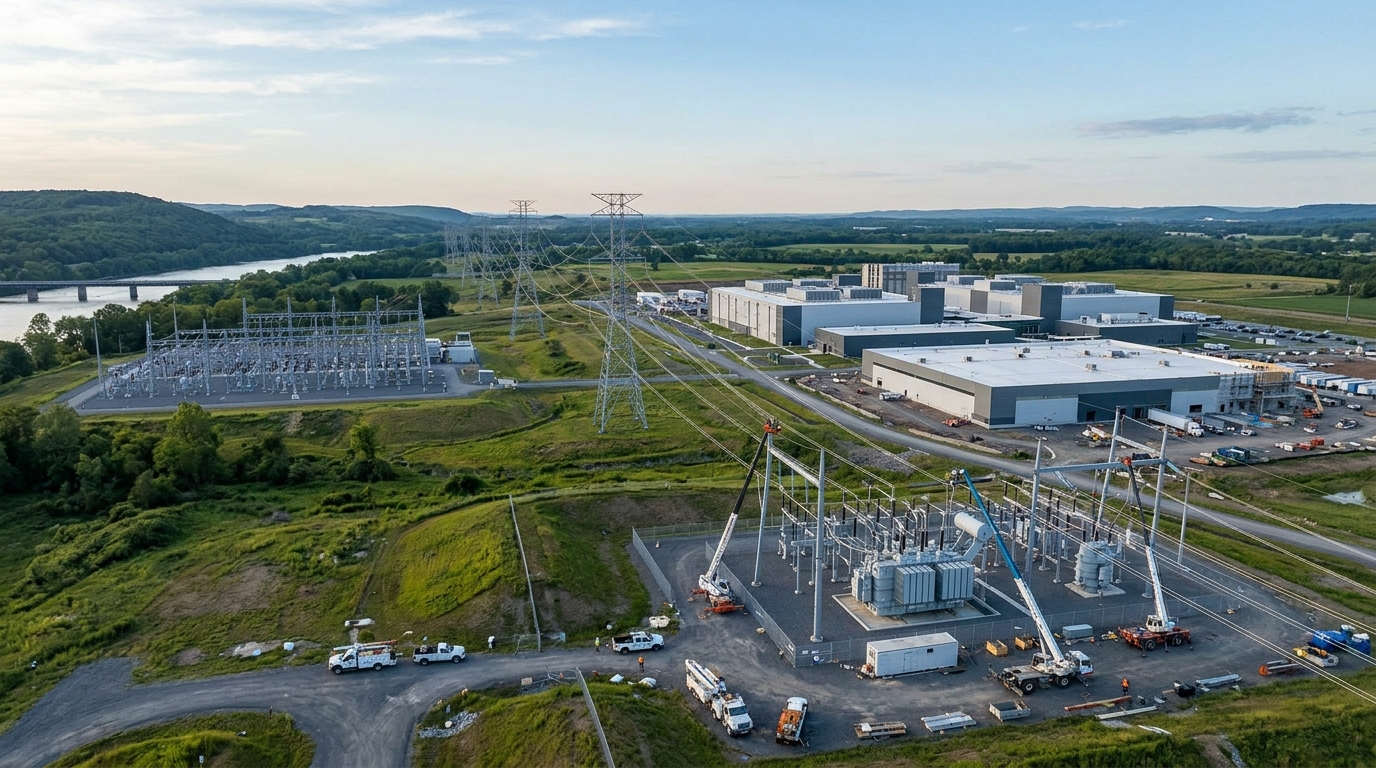
The industrial demand story is not theoretical. National Grid is progressing the electricity connection work for Micron’s first semiconductor fabrication plant in Clay, New York, supporting a 480 MW load that has been cited in New York regulatory filings. A second Micron project has also been cited in the mid-500 MW range. Combined, that puts early phases above 1 GW, which would be large in the context of National Grid’s New York electric peak demand, which has been reported around 6.6 GW.
That scale of committed industrial load is exactly what regulators and investors need to see to underwrite the debt accumulation. Without locked-in demand contracts, a £13.5 billion annual capex run rate looks speculative. With them, the regulated-asset-base growth compounds at roughly 10% annually.
Scenario Modeling
Bull Case. Management upgraded full-year 2026/27 guidance to underlying EPS growth of 15-16% relative to the 2025/26 baseline. If US large-load signings accelerate through Joulent and UK RIIO-T3 revenues grow as allowed, the asset base expansion absorbs the debt cost and the stock re-rates toward peer multiples above 20x regulated earnings.
Base Case. The company reiterates its target for underlying EPS growth of 8-10% annually through to 2030/31 and asset growth of around 10% a year. That path supports a steady total return but leaves NGG trading at a modest discount to US-listed regulated utilities until gearing stabilises.
Bear Case. Regulatory gearing reaches the high 60% range, credit agencies revisit ratings, and rising finance costs compress the earnings growth that justifies the capex premium. The stock’s reaction to H1 results, where NGG initially dropped before recovering, shows the market is already stress-testing this scenario.
Active Trader Framework
The key level to monitor is the £48.6 billion net debt figure versus operating cash inflows. The H1 debt increase primarily reflects capital investment and Joulent funding, partially offset by operating cash inflows of £4.1 billion. If H2 cash conversion stays above that run rate, gearing concerns ease. If it misses, finance cost guidance for the full year moves higher. Watch the interplay between RIIO-T3 allowed revenue adjustments and sterling/dollar moves, given how heavily US operations influence reported numbers. Position sizing should account for a stock that moves on debt headlines as much as earnings beats.