September 19, 2026
Bonus Content: Netflix Just Got Its Most Bearish Rating in Years
Editor’s Note: With markets navigating significant structural pressure, one of America’s most well-connected financial analysts — who identified the conditions preceding the 2000 and 2008 downturns — is sharing a briefing that warrants broad attention. Click here to access it, or read more below.
Dear Reader,
A veteran Wall Street analyst with a documented track record has issued a detailed new assessment — and anyone with capital allocated to U.S. equities should review it now.
After running his own $200 million hedge fund, this analyst was present for the events of 9/11, documented the 2008 banking stress firsthand, and tracked the 2020 economic contraction as it unfolded.
His current assessment:
Whitney Tilson, who identified the Tech Wreck conditions in 2000, has a documented history of anticipating major market dislocations — a pattern CNBC recognized when they gave him the nickname “The Prophet.”
His analysis contributed to a 60 Minutes segment on the 2008 financial crisis that won an Emmy.
His concern centers on a permanent realignment in the U.S. economy — one with broader reach than a single market repricing or isolated banking stress event.
Consider what’s happening at Gartner. For decades it anchored America’s white-collar knowledge economy, drawing heavily from top-tier institutions.
It should rank among the country’s more resilient firms.
And yet it has drawn down more than 60% over the past year.
That data point is what leads Tilson to argue it is now an important moment to review your current allocations — because the broader pattern he has identified points to accelerating change across a wide segment of the U.S. economy.
He has agreed to lay out exactly where he sees the case for repositioning today — drawing on a new research framework his team spent years developing in anticipation of this environment.
Access the full briefing here.
Regards,
Matt Weinschenk
Publisher and Director of Research, Stansberry Research
P.S. Gartner is not an isolated case. A range of white-collar knowledge-economy firms are showing similar pressure. Consulting. Insurance analytics. Software.
Morningstar. Duolingo. Verisk. Accenture. Each has seen significant drawdowns. Duolingo has retraced as much as 75% over the past year.
These are not unrelated data points. They reflect a connected structural theme — and Tilson’s briefing explains why the pattern matters for how capital is positioned today.
Netflix Just Got Its Most Bearish Rating in Years
Analyst Targets
- Wells Fargo (Steven Cahall): Underweight, $57 target (cut from $80)
- Evercore ISI (Kutgun Maral): Outperform, $110 target (raised this week)
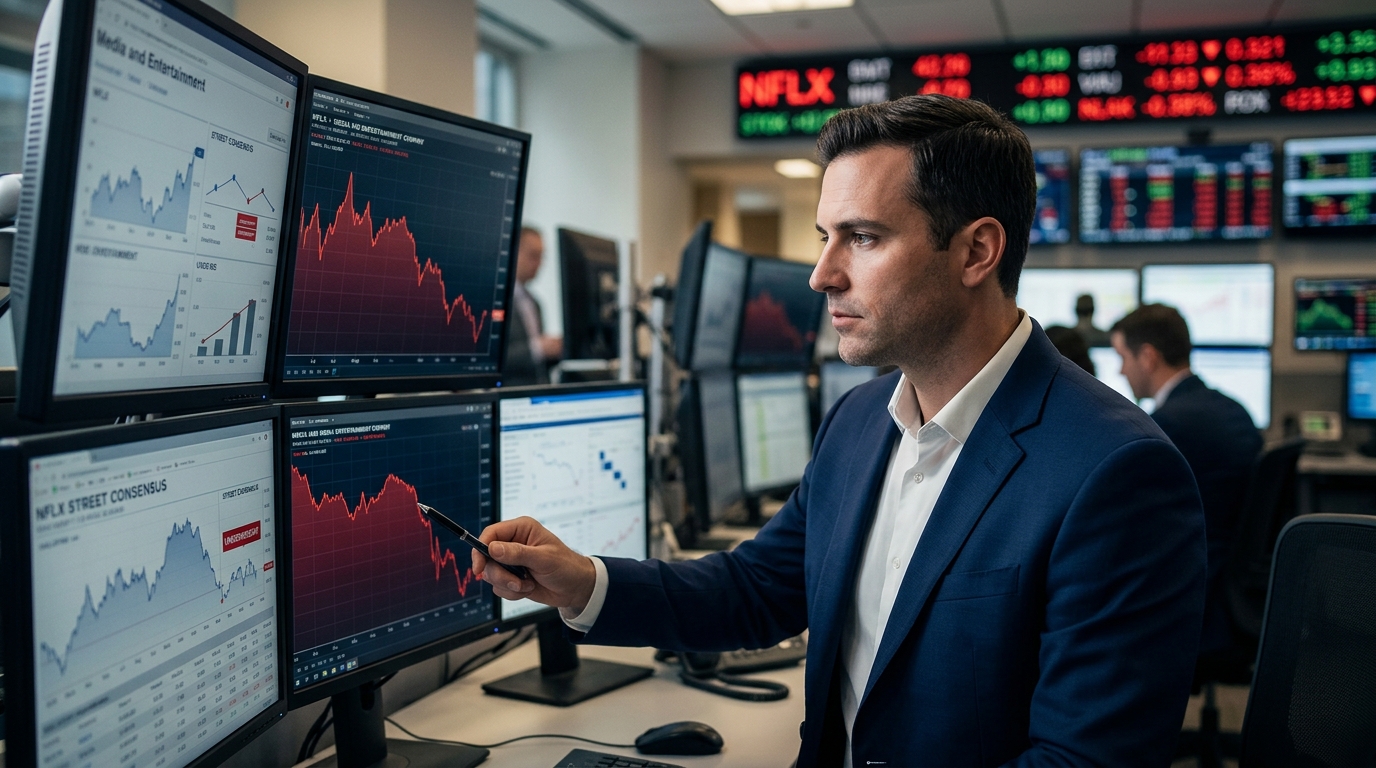
- Street consensus: Buy, ~$93.88 average target across 52 analysts
The Divide
Wells Fargo downgraded Netflix to Underweight from Equal Weight on Friday, cutting its price target to $57 from $80, implying roughly 25% additional downside from Thursday’s close. That call lands against a Wall Street consensus so bullish it borders on lopsided. The move runs against the broader consensus: among the 52 analysts who cover Netflix, 38 rate the stock a buy or strong buy.
The gap between $57 and $94 is not a rounding error. It is two entirely different reads on the same company, and one of them is wrong.
The Engagement Math
Analyst Steven Cahall cited deteriorating viewer engagement as the central concern, noting that each subscriber watched an average of 1.6 hours per day in the first half of 2026, down roughly 8% on an adjusted basis from the comparable period in 2023. His base case is harsher still: Wells Fargo projects the company’s top 100 originals hours will fall 21% year-over-year in the second half of 2026.
The counter-data sits in Netflix’s own results commentary. For the current quarter, Netflix has pointed to roughly 12% revenue growth, while global viewing hours grew 2% in H1 2026, an incremental 1.5 billion hours year-over-year. Two percent growth in total hours versus a 21% projected decline in the top-100 slate: that tension is where the bull-bear debate actually lives.
Cahall argued that Netflix has been too focused on expanding into podcasts, games, and live television at the expense of original programming. His model prioritizes engagement density over volume, suggesting that increased content spending alone will not offset declining per-subscriber viewing hours. It is a credible concern. It is also precisely what the October 20 earnings call will begin to settle.
The Valuation Reset
Cahall cut his valuation multiple to 15 times forward earnings from 21 times, producing the $57 target. He flagged the second-half and full-year viewership report due alongside fourth-quarter results in January as the negative catalyst, with churn risk building into 2027.
Wells Fargo resumed coverage in March at Equal Weight with a $105 target; the target came down to $80 in July after second-quarter results left growth questions unresolved. Friday’s cut to $57 is the third reduction in six months from the same desk, which matters for how seriously the market weights it.
Macro and Competitive Context
Netflix stock is down roughly 23% year to date, so the downgrade lands on a chart that has already absorbed considerable sentiment damage. Shares sit near the low end of a 52-week range of $65.08 to $124.86, with a market cap around $299 billion. That context is not lost on buyers. Bill Ackman, who never stopped following the company after his 2022 exit, bought a new position in Netflix worth about $934 million earlier this year. As of June 30, Pershing Square’s Netflix stake totaled about 3.15 million shares, equal to roughly 4.8% of the firm’s reported long portfolio.
Bull / Base / Bear
Bull: Q3 earnings on October 20 show the second-half content slate stabilizing hours-per-subscriber, Evercore’s $110 target attracts fresh institutional buying, and the stock recovers toward $90.
Base: Viewing data stays soft but revenue guidance holds on advertising growth. The stock trades range-bound between $70 and $85 until January’s annual viewership report.
Bear: Cahall expects hours viewed per subscriber to decline about 4% year-over-year in the second half of 2026. If that reading is confirmed in October and churn ticks up, the multiple compression to 15x becomes the market’s anchor rather than an outlier view.
Technical Overlay
Trading volume on Friday reached about 113 million shares, well above the three-month average of about 39 million. Volume that extreme on a downgrade day marks genuine conviction selling, not noise. The $65 level, the 52-week low, is the line that separates a painful correction from a structural breakdown.
Bottom Line
This is not a call against Netflix’s business model. The downgrade is best framed as a debate over the second-half slate rather than a verdict on Netflix as a platform. Netflix reports Q3 results on October 20. That is the data point that resolves the engagement argument, one direction or the other. Until then, the roughly $37 gap between Cahall and the street consensus is the risk every shareholder is holding.