Hi,
Take a look at this…
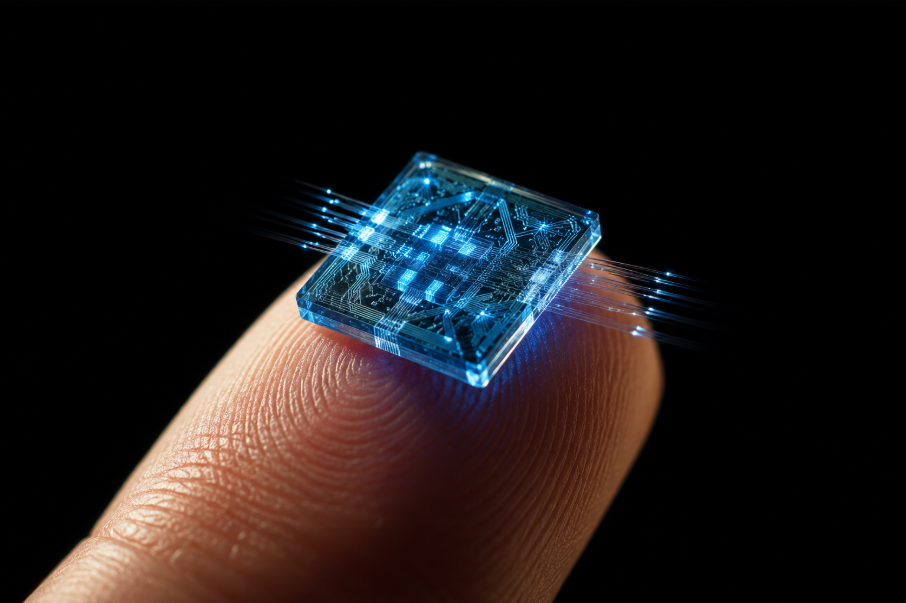
It’s smaller than a fingertip…
It’s made of glass…
And it’s about to unlock the next wave of AI growth.
Jensen Huang, Nvidia’s CEO, says this “light-speed” device is shattering the limitations of AI… and without it, AI can’t scale.
Google Ventures says it’s the future of AI compute…
And Sequoia Capital – the firm that backed Anthropic and OpenAI – calls it a “holy grail.”
Already, Elon Musk, Mark Zuckerberg, Cathie Wood, and Bill Gates are moving money to prepare for what’s coming…
Yet most Americans have never heard of it.
Wall Street insider Jason Bodner – the same man who called Nvidia at $4.50 – says this device is about to launch a whole new wave of AI winners…
And to prove it, he’s giving away his #1 stock involved with it – for free.
Click here to learn more. (No purchase necessary.)
We have so much to look forward to,
Jeff Brown
Founder & CEO, Brownstone Research
P.S. Stocks tied to this “light-speed” device already surged 133%, 217%, and even 320% – in a few short months. But it’s just getting started. Click here before the mainstream catches on.
Three Earnings Reports That Will Expose Where the Consumer Actually Stands
This week delivers something rare: a single earnings stretch that cuts across car repairs, new home demand, and bulk retail in one sweep. AutoZone reports Tuesday morning, KB Home follows Tuesday after the close, and Costco closes the week Thursday. Each tells a different piece of the consumer story. Read them together and you get a clearer picture than any macro survey.
AutoZone: The Repair Thesis Gets Its Biggest Test of the Year
AutoZone reports its fiscal fourth-quarter 2026 results before the bell Tuesday. Consensus calls for $54.22 in EPS on $6.71 billion in revenue, which would represent an 11.3% earnings increase and 7.5% revenue growth year over year. The bar is meaningful but not heroic.
The structural story behind AutoZone has been one of the more durable trades in consumer discretionary: an aging vehicle fleet pushes more drivers to fix rather than replace. That thesis does not break easily. But analysts have trimmed estimates modestly over the past 30 days, with consensus EPS drifting down roughly 0.5% from $54.48, signaling some caution heading into the release.
- Q4 FY25 EPS: $48.71 actual (year-ago comp)
- Q4 FY26 consensus EPS: $54.22, range $51.46 to $56.97
- Revenue consensus: $6.71 billion
- Last reported gross margin: 52.2%
- Stock price (Sept. 19): approximately $2,850
The commercial sales segment is the real swing factor. AutoZone’s Mega-Hub expansion has been quietly compressing delivery times for professional shops, and that business carries lower margins than the retail walk-in trade. If commercial same-store sales re-accelerate, the stock has room to move. If the numbers confirm that fuel cost pressures are landing harder than expected, the downside could be sharper than a modest EPS miss would normally produce at this valuation.
Analyst sentiment is broadly constructive: one Strong Buy, 20 Buys, and six Holds as of Friday, per MarketBeat data. The stock trades near a trailing P/E of roughly 19, modest by consumer-discretionary standards, which limits the downside on an in-line result but also caps the upside unless commercial segment commentary surprises.
KB Home: Where the Housing Recovery Goes to Get Graded
KB Home’s fiscal Q3 results arrive Tuesday after the close, and the numbers the market is expecting are genuinely sobering. Consensus sits at $0.90 EPS, down from $1.61 in the year-ago quarter, on revenue of $1.3 billion versus $1.62 billion last year. That is a 44% year-over-year earnings decline built entirely into price, which already reflects the damage.
KB Home’s business is disproportionately exposed to first-time and payment-sensitive buyers. Mortgage rates holding in the mid-to-upper 6% range have been a persistent ceiling on affordability. The company’s Q1 2026 report already showed revenues down 23% year over year, with EPS falling to $0.52. Q2 was mixed. Q3 guidance exists, and the question is not whether the quarter is bad but whether the guide for Q4 shows any rate-driven stabilization.
- Wells Fargo: Underweight, target cut to $50 (from $52) on Sept. 11
- Barclays: Overweight, target $57
- UBS: Buy, target $66
- Stock price (Sept. 15): approximately $49.57
The NAHB has flagged that a sustained sub-6% mortgage rate likely waits until 2027. That is the structural ceiling KB Home operates under right now. What matters most in Tuesday’s report is not the EPS line but order trends and cancellation rates. Those figures are the leading indicator, and they are what will determine whether KBH spends the next two quarters rebuilding or continues to compress.
Costco: The Valuation Debate Comes to a Head
Costco reports Thursday after the close. Analysts expect $6.53 to $6.55 in EPS on approximately $94.85 billion in revenue. The company has beaten consensus EPS in each of the last four quarters, but the stock has already pulled back from its 52-week high of $1,096.50 to around $895, and Bank of America trimmed its price target to $1,095 this week.
The earnings number matters less than two other items: the e-commerce trajectory and the special dividend question. Digitally-enabled sales for the fiscal year rose 20.9%. Costco has been sitting on an unusually large cash balance, and management has repeatedly acknowledged that capital return stays on the radar. The company’s prior special dividend was announced in December 2023, roughly three and a half months after the August fiscal year-end. The pattern fits the calendar if management wants to move later in 2026, but it is not a promise.
- Q4 FY26 EPS consensus: $6.53 to $6.55
- Q4 FY26 revenue consensus: $94.85 billion
- 50-day moving average: $937.35
- 200-day moving average: $972.55
- Fiscal 2026 full-year sales: approximately $297.3 billion, up 10.2%
At roughly 45 times trailing earnings, Costco is not cheap by any measure. The counterargument is that the membership model generates recurring, front-loaded cash flows that behave more like a subscription business than a retailer. Renewal rates around 92% in the U.S. and Canada underpin that case. The risk is that the stock needs a perfect quarter and a special dividend signal to re-rate higher. An in-line result without a cash deployment hint may not be enough to lift shares meaningfully from current levels, given where both the stock and the 10-year Treasury sit.
The Macro Thread Connecting All Three
These three reports are not independent events. AutoZone’s commercial volume tells you how stressed professional shops are and, by extension, how much financial slack households have. KB Home’s order book tells you whether affordability has definitively capped the entry-level housing market. Costco’s comp and membership renewal numbers tell you whether the value-seeking trade remains intact or is finally showing cracks.
The Bank of Japan’s rate hike on Friday pushed yields higher and rattled futures into the weekend. The Trump-Xi meeting expected next week adds a second variable. Against that backdrop, this week’s consumer read from three very different businesses is as close to ground truth as the market gets between now and October earnings season.