October 27, 2026
Bonus Content: Boeing Beat on Revenue. The 777 Freighter Problem Matters Now.
Blane Markham here, with an alert!
If you still haven’t saved your copy of “How To Turn $100 Options Into $1,000 Gains”…
… do it right now before the download link expires.
We’ll be moving this book behind a paywall in the near future so grab it now while you still can.
You’ll thank me.
FREE: How To Turn $100 Options Into $1,000 Gains
To your success,
Blane Markham
Markham Trading Team
Reminder:
Grab your copy of How To Turn $100 Options Into $1,000 Gains before we move it behind a paywall.
Boeing Beat on Revenue. The 777 Freighter Problem Matters Now.
Analyst Targets
- Barclays: Overweight, $300 — initiated October 8
- Bank of America: Buy, $270 — maintained October 21
- Bernstein: Outperform, $278 — reduced from $298 on October 12
- RBC Capital: Outperform, $235 — reduced from $265 on October 15
- Morgan Stanley: Equal-Weight, $225 — reduced from $250 on October 19
- Susquehanna: Buy, $285 — maintained October 19
Wall Street’s consensus sits at roughly $267 across 29 analysts, implying more than 40% upside from pre-report levels near $188. Nine consecutive downward EPS revisions over the past 90 days tell a different story about near-term confidence.
The Numbers
Street consensus heading into this morning’s call: revenue of approximately $24.37 billion, a core loss per share of around $0.20, and positive free cash flow in the low hundreds of millions, even after absorbing a $700 million Department of Justice payment. Early coverage indicates Boeing cleared both the revenue bar and the cash-flow milestone, the first back-to-back quarter of positive free cash flow in the recovery cycle.
- Revenue consensus: ~$24.37B, up 4.7% year over year from $23.27B in Q3 2025
- Core EPS consensus: loss of ~$0.20 to $0.23, compared with a loss of $7.47 a year ago
- Deliveries: 161 commercial aircraft in Q3, down from 171 in Q2 but nine-month totals up 8% year over year to 475
- Q2 2026 comparison: revenue of $24.6B, free cash flow of $631M, core loss of $0.76 per share
The year-over-year loss comparison is heavily distorted: Q3 2025 included a $4.9 billion 777X program charge. The cleaner read is the sequential delivery dip and the cash flow trajectory.
Why the Stock Is Moving
Two forces are pulling in opposite directions this morning, and the market is pricing both simultaneously.
The revenue beat and sustained positive free cash flow matter because CEO Kelly Ortberg has staked the recovery thesis on proving that delivery growth converts into cash. Management guided Q3 free cash flow to “positive low hundreds of millions” despite the DOJ payment, and confirming that guidance is a credibility moment, not just a metric.
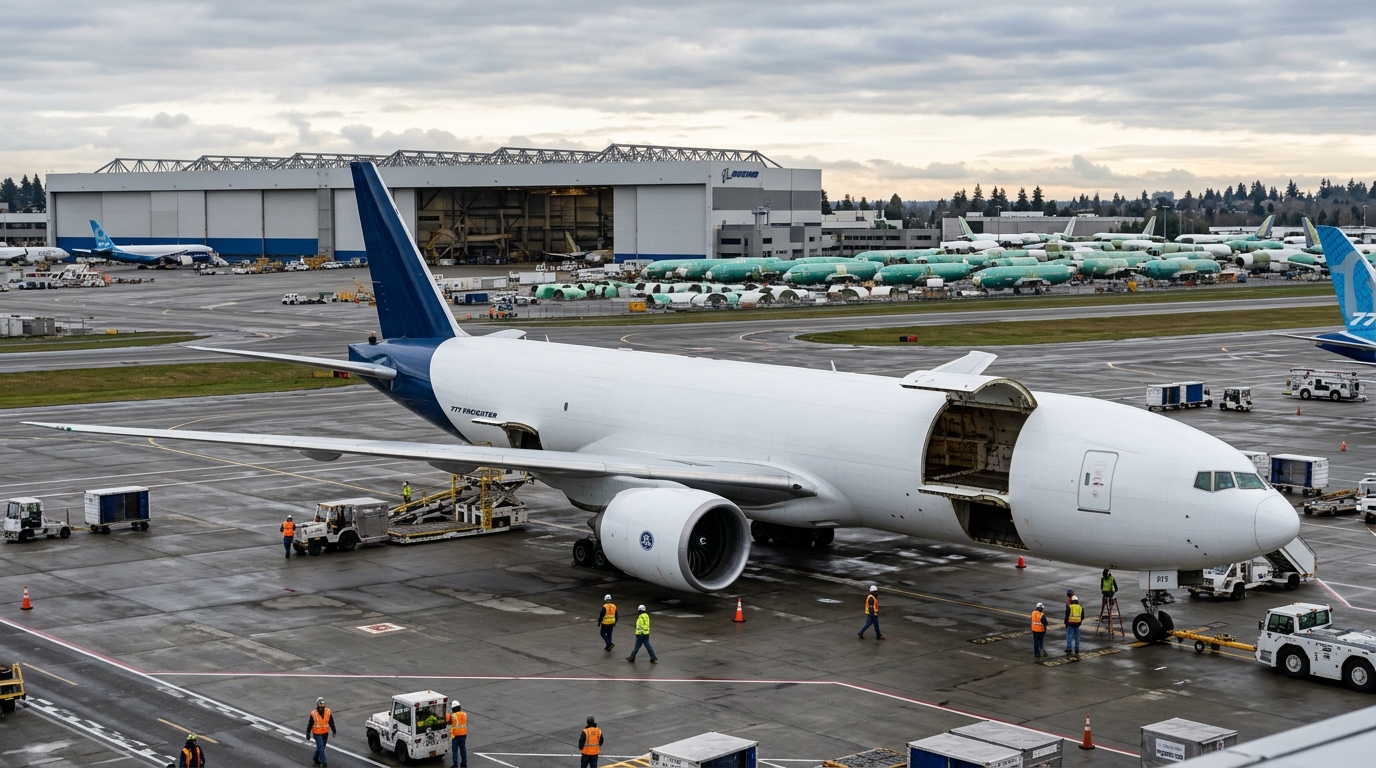
The headwind is more specific. Reuters reported October 23 that Boeing’s dispute with Florida-based supplier Vaero halted 777 freighter production for nearly two months and disrupted output of the 767, including KC-46 tankers. Boeing filed a complaint in August alleging Vaero stopped delivering a trailing-edge rib kit, an “indispensable” component for which Vaero was the sole supplier. The stoppage was costing Boeing as much as $6.5 million per day, according to Boeing’s own court filing. A settlement was reached in late September, but as of last week, 777 freighter production had not resumed, with two partially assembled aircraft pulled from the final assembly line in Everett. The 777X uses composite wings and is unaffected, but the current-generation freighter and 767 programs carry the damage.
The 737 MAX 10: Revenue That Hasn’t Landed Yet
On October 20, the FAA certified the 737 MAX 10, completing certification of all four main MAX variants. The approval followed nearly 1,000 test flights and more than 2,000 flight hours, plus roughly 1,000 hours of ground testing. Boeing has 1,555 orders for the type from more than 30 customers, representing over 30% of the unfilled 737 MAX order book.
Certification removes the regulatory barrier. But first deliveries are expected in the coming months, meaning the cash attached to those orders does not reach this quarter’s free cash flow statement. The MAX 10 is a Q4 and 2027 catalyst, not a Q3 one.
Macro and Industry Context
Airbus reports tomorrow, giving the market an immediate cross-reference. Boeing’s nine-month delivery count of 475 aircraft reflects an 8% year-over-year gain, driven in part by 57 deliveries in September alone. That momentum supports the full-year delivery targets. The 737 is running at approximately 47 per month, with Boeing working toward 52 per month, and the new North Line in Everett is now active. Defense margins at Boeing Defense and Space improved to 3.5% excluding the VC-25B in Q2, against a full-year target of roughly 2.5%.
Forward Scenarios
Bull
Free cash flow beats guidance, management raises the full-year $1B–$3B range, 777 freighter production resumes within weeks, and MAX 10 first deliveries begin before year-end. The MAX 10 order backlog triggers a visible Q4 cash acceleration. BA approaches the $210–$212 resistance zone.
Base
Revenue beat holds, free cash flow lands in the low hundreds of millions as guided, and management reaffirms the annual range without raising it. The 777 stoppage is acknowledged but contained to a narrow delivery impact. The stock settles between current levels and $200, with the MAX 10 remaining a 2027 earnings driver.
Bear
The Vaero disruption runs longer than disclosed, 787 deliveries turn uneven due to seat certification delays, and free cash flow guidance for Q4 disappoints. BA revisits support near $184–$186, and another round of downward analyst target revisions follows.
Supply-chain fragility is not the only execution risk the market is pricing into Boeing’s recovery. Labor contract votes have previously threatened to freeze Boeing production at exactly the moment commercial wins were accelerating, a pattern that shapes how analysts discount the order backlog.
Technical Overlay
BA entered today near $188, well below the 52-week high of $254.35. Near-term support sits at $184–$186, secondary support at $176–$180. Initial resistance is $197–$200. A revenue beat and confirmed cash flow positive should test the $197 level; failure to hold that zone on any guidance disappointment brings $184 back into view quickly.
Bottom Line
Boeing’s Q3 results confirm the recovery is intact at the top line and cash flow is turning. That is real progress. The Vaero situation is the sharper issue: a single Florida parts supplier halted a major freighter program for nearly two months, costing Boeing up to $6.5 million per day, and production still had not resumed as of last week. The recovery story depends on eliminating exactly this kind of single-point fragility. What investors should watch on the 10:30 a.m. call is not the revenue beat. It is whether Ortberg gives a specific timeline for restarting 777 freighter output and whether the full-year cash flow guidance moves. Those two answers will determine how much of today’s beat actually holds.