November 4, 2026
Bonus Content: Robinhood’s Record Options Volume Hid a Profit Problem
Dear reader,
For the last few months, my team and I have been tracking some incredible activity across Elon Musk’s most secure facilities.
And we have obtained shocking new drone footage that has finally shed some light on what is going on:
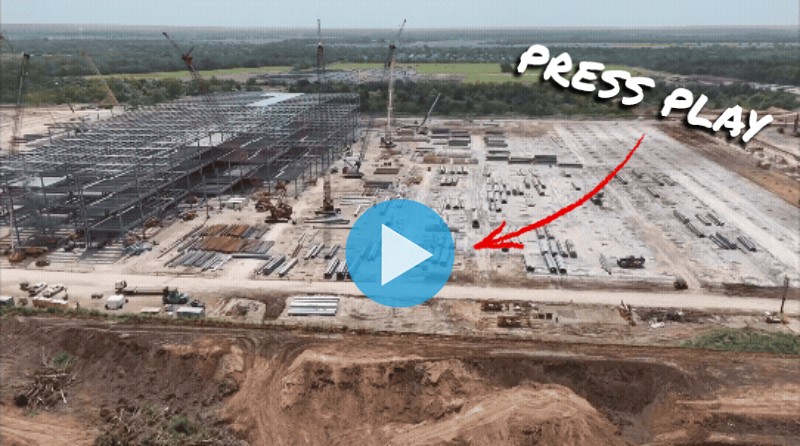
Only a short time ago, this site was covered in thousands of trees. In a matter of weeks, at a pace almost no other company on Earth could match, all of it was cleared to make room for a single, groundbreaking new factory. It is already under construction.
What happens inside is something Elon is quietly calling his “infinite money glitch.”
It sounds crazy to say out loud.
And once that snowball begins to roll, it will be almost impossible to stop.
Based on my research, it could go live as soon as January 27.
I believe what is happening inside this factory is the most important story I have ever covered.
I put everything into a short presentation: what the “infinite money glitch” is, how much newly created wealth could be up for grabs, and how to take advantage of this opportunity before the deadline.
Watch it now. Because after January 27, the whole world could catch on to what’s inside.
Regards,
James Altucher
P.S. I’m giving away a free report to anyone who watches this presentation today. It details Elon’s Musk’s unprecedented trillion-dollar compensation package and identifies the companies he NEEDS to hit his incentives. Just click here to watch the free video, and I’ll show you how to claim it. No credit card needed.
Robinhood’s Record Options Volume Hid a Profit Problem
Analyst Targets
- Citizens JMP: Market Outperform, $165
- Morgan Stanley: Overweight, $160
- Goldman Sachs: Buy, $128 (cut from $145)
- KeyCorp: Overweight, $135 (cut from $140)
- Cantor Fitzgerald: Overweight, $120 (cut from $150)
- JPMorgan: Neutral, $114 (cut from $115)
The Core Contradiction
Robinhood’s options desk has never been busier. 905 million contracts traded in Q3 2026, up 48% year over year, an all-time record. By activity measures, this was one of Robinhood’s strongest quarters.
Then net income fell 14% to $476 million, diluted EPS dropped 16% to $0.51, and the stock fell about 7% in after-hours trading on October 27, 2026.
Volume was not the story. Monetization was.
What the Numbers Actually Said
Total revenue reached a record $1.424 billion, up 12% year over year, but missed the Bloomberg consensus of about $1.44 billion. The gap looks small. The composition is what matters.
- Options revenue: $399M, up 31% YoY
- Equities revenue: $121M, up 41% YoY
- Event contracts revenue: $173M, up more than sixfold
- Cryptocurrency revenue: $120M, down 55% YoY
- Net interest revenue (NIR): $415M, down 9% YoY
- Operating expenses: up 16%, outpacing revenue growth
Analysts on the Q3 call flagged take rates as lighter than expected, driven by product mix shift and tighter spreads entering October. That compression, not the volume figures, is what set the tone for analyst target cuts.
Why the Stock Is Down
Robinhood’s revenue model has two engines: trading activity and the spread it earns on assets sitting on the platform. Both were stressed simultaneously. Net interest revenues fell as lower securities-lending rates and a softer short-term interest rate environment ate into the cash sweep spread. Crypto revenue, still a meaningful contributor a year ago, collapsed 55% to $120 million as market activity normalized from 2025’s elevated volatility. Operating expenses rose 16%, driven in part by higher credit loss provisions tied to the growing credit card book and costs tied to new products including Trump Accounts.
Crypto’s collapse inside Robinhood’s revenue mix raises a direct comparison with its closest digital-asset rival. Coinbase and Robinhood share the same Goldman Buy rating but carry very different exposures to a crypto revenue recovery.
Expenses growing faster than revenue at a fintech whose core argument is operating leverage is a problem. Adjusted EBITDA margin held at 57%, but net margin compressed visibly.
Macro and Industry Context
The Federal Reserve’s rate trajectory is working against Robinhood in a specific way. As short-term rates decline, cash sweep income shrinks, and no amount of options volume fully offsets $41 million less in net interest revenue quarter over quarter. For a platform with $396 billion in Total Platform Assets, the NIR line is structurally important. That dynamic is unlikely to reverse quickly.
The rate debate shapes how much pressure Robinhood’s NIR line faces going forward. Wall Street’s sharpest disagreement over the Fed’s next moves has direct consequences for platforms whose cash sweep income depends on where short-term rates settle.
Bull / Base / Bear
Bull: Event contracts scale to a $500M annualized revenue run rate, credit card provisions normalize as the book seasons, and crypto rebounds alongside broader digital asset activity in Q4. Options take rates stabilize above October’s compressed levels. HOOD trades back toward $110.
Base: Options volume holds at or near record levels, but take rate compression continues through year-end. Crypto revenue stays weak. NIR declines modestly as rates drift lower. The stock consolidates in the $80 to $95 range.
Bear: Market volatility fades into year-end, pulling options volumes below Q3 records. Stablecoin monetization disappoints. Credit card provisions escalate. Cantor’s $120 target proves generous. HOOD tests the $75 zone.
Technical Overlay
HOOD traded near $85 heading into this week, well below the 50-day and 200-day moving averages after the post-earnings flush. The $92 to $95 band is the first meaningful demand zone; a failure there opens the gap toward $75. Upside resistance sits at $110, where the pre-earnings consolidation broke down.
Bottom Line
Robinhood moved more options contracts than it ever has. That is real. But the market is being asked to pay a growth multiple for a business where the two revenue lines outside trading, NIR and crypto, are both shrinking. Until take rates stop compressing and expenses decelerate, volume records will keep losing the argument to margin math.