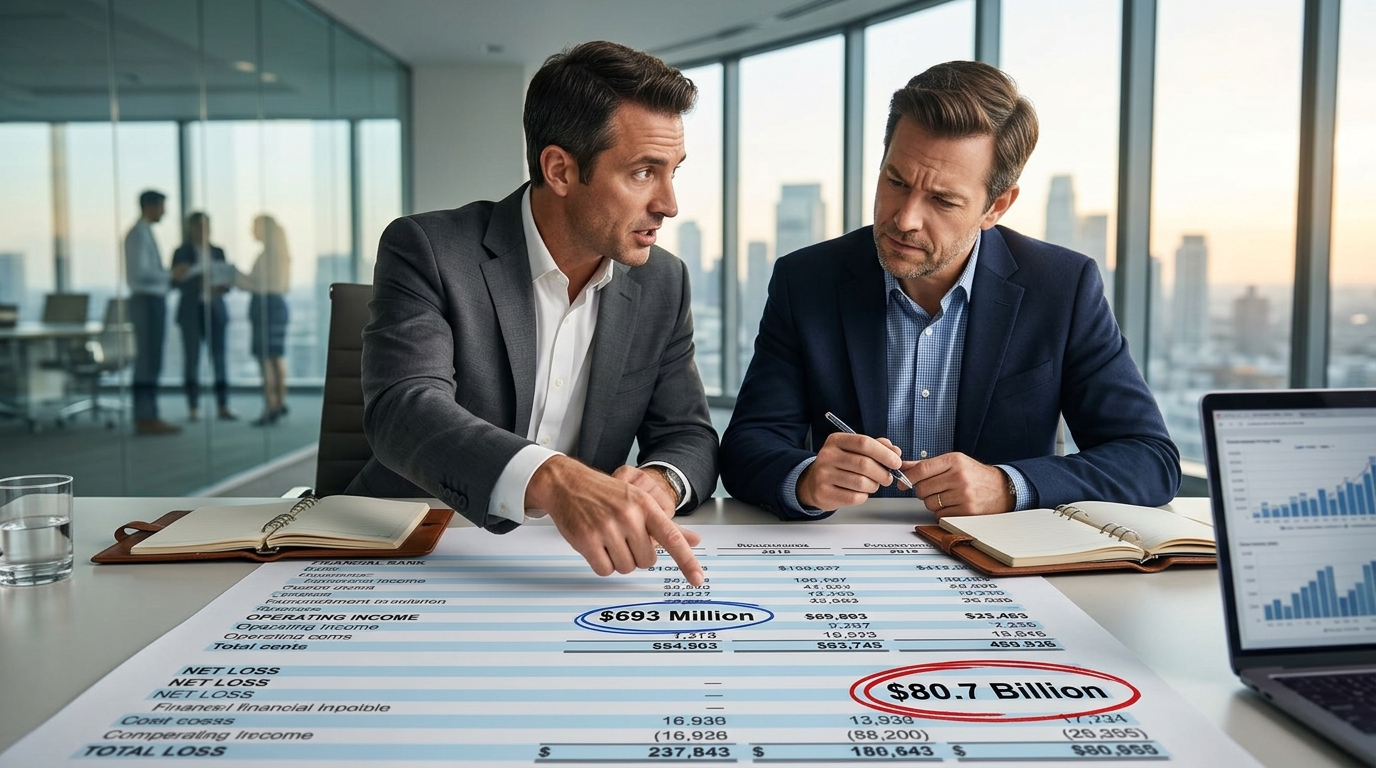
The number that stopped the AI selloff cold on Monday was $16.29 billion: Anthropic’s revenue for the six months ended June 30, 2026, compared with about $1.2 billion a year earlier. The number that lit up every headline was $80.75 billion, the net loss sitting directly below it. Institutional investors are now splitting into two camps along exactly that fault line.
Why the Loss Is the Wrong Starting Point
Read the S-1 rather than the summary and the $80.75 billion figure nearly dissolves. Anthropic’s net loss includes $72.388 billion of non-cash fair-value changes on convertible notes, derivative liabilities and SAFEs. Those charges exist because Anthropic’s private valuation kept rising; when the underlying shares become more valuable, accounting rules force that move through the income statement as a loss on the instruments tied to them. When the value of the underlying shares climbs, the liability grows, and accounting rules push that growth through the income statement as a loss. Such charges are typically non-cash. The company pays no bill on the day they hit.
Strip that out and the first-half loss is roughly $8.36 billion; the operating loss was $693 million, and operating cash flow was positive $3.93 billion. More telling still: on an operating basis, the loss narrowed to $693 million from $2.1 billion, and the company booked $974 million in operating income in the second quarter. That is Anthropic’s first quarterly operating profit, and portfolio managers who focus on it arrive at a very different valuation conversation than those anchored to the net loss headline.
The Bull Case: A Revenue Machine With No Comparable
The growth case for ANT rests on customer economics that are genuinely unusual. As of September 30, Anthropic recorded more than 11,900 customers spending at least $100,000; more than 1,900 customers spending upward of $1 million; and about 250 customers spending $10 million or more annually. The retention figure is what separates Anthropic from almost every enterprise software company ever taken public: the company’s net revenue retention stood at around 900% as of September 30, according to the prospectus. That means existing customers are increasing their spending by ninefold from one year to the next.
Anthropic also disclosed that 79% of its revenue came from customers outside its five largest accounts in the third quarter, a concentration profile that growth-oriented funds can underwrite. At $16.29 billion in six months, annualized revenue is already running well above what most enterprise software companies generate in a decade of operation.
The Bear Case: The Compute Bill Cannot Be Ignored
The skeptics are not arguing about the non-cash loss. They are arguing about cash obligations that are very real. Anthropic’s filing shows the company has future minimum payment obligations of approximately $417 billion for compute and infrastructure, with agreements that begin between 2026 and 2027 and last from under one year to up to 20 years. Additionally, Anthropic said that it expanded certain existing agreements to secure additional compute capacity to be delivered between 2028 and 2031, and it estimates those future payments at approximately $125 billion to $150 billion.
The structural problem is asymmetry. Much of the spending remains payable regardless of demand for Anthropic’s AI services. Anthropic’s S-1 also states that many customer contracts permit customers to cut usage or end agreements with little or no notice. Revenue can slow; the compute bill cannot. That mismatch is the actual bear case, and it is more durable than any argument about accounting.
What the Mavens Are Missing
The loudest debate in most investment committees is about whether $2 trillion is defensible against $16.29 billion of half-year revenue. Some investors have discussed a $1.5 trillion price. That is a reasonable valuation debate. The less-examined question is what Anthropic’s infrastructure commitments mean for the suppliers locked into the other side of those contracts.
The sellers include Amazon, Alphabet and Microsoft. Each one supplies compute to Anthropic and each also builds AI products that compete with Claude. A successful ANT listing cements their largest infrastructure customer; a stumble at pricing creates exposure they have not disclosed publicly. Either way, the hyperscalers’ positions in this deal are more complicated than their stock reactions on Monday suggested.
Stocks to Watch
Nvidia (NVDA) is the clearest read-through. Anthropic’s largest commitments are to Google Cloud, AWS and Microsoft, but the marginal beneficiary of the compute bill is the chip layer: Nvidia for accelerators, Broadcom for custom silicon, Micron for memory.
CoreWeave (CRWV) moved in the same direction for different reasons. CoreWeave shares swung sharply on Monday, falling early before briefly turning positive and then finishing up modestly, as investors treated the S-1 as a reminder that compute demand remains deep enough to sustain independent capacity.
Amazon (AMZN) and Alphabet (GOOGL) warrant close attention into earnings Wednesday. Both hold equity stakes in Anthropic and anchor the compute agreements. Alphabet and Microsoft report earnings on Wednesday as investors weigh growing AI spending and backlogs. If either signals that Anthropic-linked compute revenue is accelerating faster than their own AI product lines, the dual role of customer and competitor becomes a disclosure question, not just a strategic one.