November 8, 2026
Next AI Shock Starts Here
Bonus Content: Siemens Energy’s Fiscal 2027 Guidance Is Three Days Away. Here Is What Actually Matters.
Dear Reader,
I’m convinced that AI’s next phase will blindside millions of American investors.
And it has NOTHING to do with the recent “tech wreck.”
But I believe if you have any money in the stock market or a 401(k), it’s imperative you make one straightforward move immediately…
A move that I’ll explain, for free, right here.
This isn’t my first bold AI prediction.
- I recommended Nvidia all the way back in 2015, before it went on to surge over 21,000%.
And years before AI became a household term, I developed a 20-factor computerized stock-rating system to identify tomorrow’s winners on Wall Street… TODAY. - That system recently identified AI winners such as Sandisk, before it rose 300% in just a few months.
- It flashed bullish on data-storage company Seagate, before it rocketed 393% in months.
- And Micron Technology, before an 827% gain in just a year.
But there’s a reason most folks didn’t catch these ahead of time.
Each of these stocks took off thanks to a powerful ripple effect spreading through the AI economy.
And my research suggests that ripple is now moving somewhere new.
I’m sharing all the evidence to prove why AI’s next phase could generate the biggest and fastest financial windfalls I’ve seen in my 60-year career…
And the straightforward move I believe you should make now, before the next wave hits.
Get the full story and see the name of my No. 1 recommendation here.
Be well,
Marc Chaikin
Founder, Chaikin Analytics
Siemens Energy’s Fiscal 2027 Guidance Is Three Days Away. Here Is What Actually Matters.
Analyst Targets
- JPMorgan: Overweight, €245 target. Phil Buller cites low investor expectations as the basis for the call ahead of November 11 results
- UBS: Buy, €210 target. Analyst Christopher Leonard argues the recent selloff was unjustified and lists ENR among preferred European energy technology names
- Bank of America: Positive ahead of the results; expects fiscal 2030 margins of 21% to 23% and fiscal 2027 free cash flow of €9 billion to €10 billion
- Consensus (28 analysts, per MarketScreener): Average target €192.55, Outperform
Wednesday in Focus
Siemens Energy publishes Q4 and full fiscal year 2026 results on Wednesday, November 11, at 07:00 CET. The company’s event listing points to a press conference from 08:00 CET and an analyst conference from 11:00 CET. Management will walk through major Q4 developments and present its fiscal 2027 outlook, with any longer-term target updates and capital allocation priorities closely scrutinized.
The stock finished the week higher after a two-day bounce. It is still down roughly 7% over the past week. That gap between broker conviction and market price tells you everything about the tension entering Wednesday’s release.
Company Profile
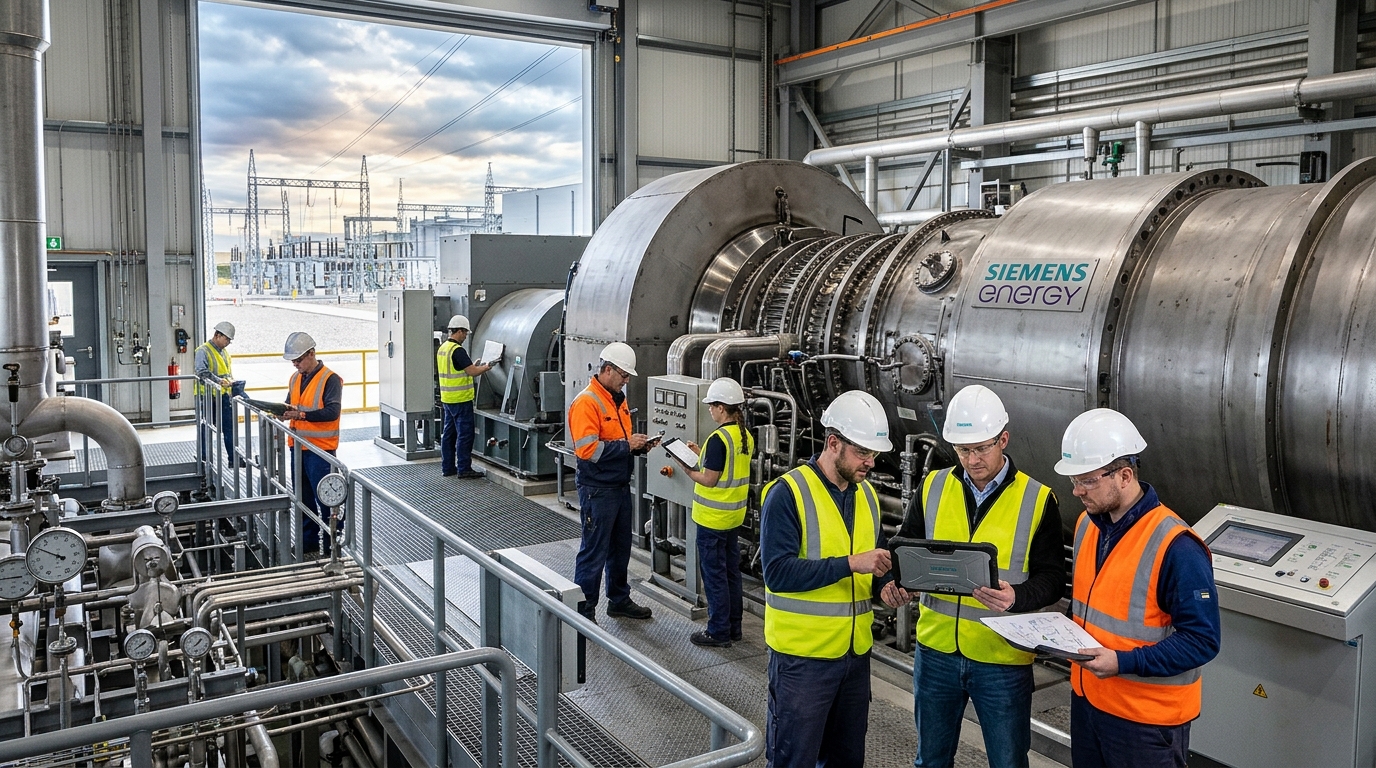
Siemens Energy makes gas turbines, grid equipment and industrial energy equipment, and owns the wind turbine maker Siemens Gamesa. Its four revenue segments are Gas Services, Grid Technologies, Transformation of Industry, and Siemens Gamesa. Former parent Siemens AG has reduced its holding over time, putting standalone execution squarely in the spotlight.
The Numbers Going In
Q3 delivered record orders of €17.9 billion and record revenue of €11.4 billion, with a book-to-bill ratio of 1.57 and total backlog reaching an all-time high of €162 billion. The Gas Services division shipped 6 GW of turbines during the third quarter, bringing gas turbine backlog to 69 GW, with orders at roughly €10 billion, up 62% year-over-year.
Consensus expects full-year revenue of €44.2 billion, EBIT of €5.29 billion, and EPS of €4.40. For fiscal 2027, the street models revenue of €50.7 billion, EBIT of €7.40 billion, and EPS of €6.31.
Why the Stock Is Moving and What Wednesday Must Deliver
Management pre-warned on the August call that Q4 would see a moderation in profitability and cash flow due to seasonality, including a weaker service environment in Gas Services and back-end-loaded capital expenditure. CFO Maria Ferraro acknowledged that the record order quarter is not expected to repeat every quarter, and that Q4 would bring a moderate soft landing.
The market already knew that. The debate now is whether the fiscal 2027 outlook delivers enough to satisfy a bar that Bank of America has lifted. Bank of America expects the company to outline fiscal 2030 margins of 21% to 23%, fiscal 2027 free cash flow of €9 billion to €10 billion, and annual share buybacks of €4 billion. These are analyst expectations, not guidance issued by Siemens Energy.
Macro Context: The AI Trade Without a Chip in It
Siemens Energy, alongside GE Vernova and Mitsubishi Heavy Industries, sits in a concentrated market for large gas turbines. They supply many of the largest turbines each year, but that is not remotely close to satisfying demand. The rapid growth in demand for gas turbines has created a bottleneck.
That bottleneck just acquired a political dimension. On November 3, 2026, U.S. voters weighed in on dozens of local ballot measures related to data center development. Results tracked by Ballotpedia showed voters favoring limits in the overwhelming majority of contests, including a dozen measures that functioned as partial bans above specified size thresholds.
The irony is that permitting friction for data centers does not necessarily slow turbine orders. Existing utilities and international markets remain the company’s largest customers. CEO Christian Bruch has said market momentum for gas turbines remains intact, adding that the conventional power market remains the biggest customer and makes up the largest share of the order backlog.
The same question of backlog quality versus headline order volume is already playing out at Siemens Energy’s closest rival. GE Vernova’s Q3 results showed why the split between firm equipment backlog and slot reservation agreements matters more than the combined GW figure.
Forward Scenarios
Bull
Fiscal 2027 guidance meets or beats the €50.7 billion revenue consensus. Gas Services demand remains diversified with a robust project pipeline for fiscal 2027, while Grid Technologies posts strong growth, especially in the United States. The 2030 margin target lands at the high end of Bank of America’s 21% to 23% range. ENR re-rates toward JPMorgan’s €245 target.
Base
The company delivers in-line fiscal 2027 guidance and confirms margin progression without surprising. Gas Services Q4 softness is absorbed as flagged. Execution focus remains on converting the record backlog into revenue, profit, and cash through disciplined project delivery. Stock stabilizes in the €130 to €150 range as the market recalibrates on fundamentals.
Bear
Fiscal 2027 guidance disappoints on orders or free cash flow. The Gas Services soft landing proves harder than CFO Ferraro signaled. Data center permitting headwinds, combined with broader AI capex caution, trigger analyst target cuts. ENR tests the €100 support seen in its 52-week range.
Technical Overlay
ENR’s 52-week range runs from €100.30 (set November 13, 2025) to €191.66 (set April 24, 2026). The shares remain well below the April record and trade below their 50-day, 100-day, and 200-day moving averages. The gap between current price and the two-year closing high represents the contested ground. A strong November 11 release with upside guidance would need to clear the €130 area convincingly before the €150 and €160 zones become relevant targets again.
What Investors Should Watch
- Fiscal 2027 revenue guidance relative to the €50.7 billion consensus
- Fiscal 2027 free cash flow framework versus the €9 billion to €10 billion Bank of America expects
- Formal 2030 margin target: does it hit 21% to 23%, or fall short?
- Gas Services Q4 order level and whether backlog conversion guidance for fiscal 2027 holds
- Any language on data center permitting and U.S. customer behavior following the November 3 votes
Bottom Line
The fundamental case for Siemens Energy rests on a constraint that no election can vote away: the gas turbine backlog stands at 69 GW after booking 15 GW in new orders during Q3, with lead times now stretching to three years or more as demand continues to outpace supply. Investors worried about local data center restrictions are asking the wrong question. The right question is whether Wednesday’s fiscal 2027 guidance matches the ambition Bank of America has already embedded in the stock’s recovery story. If the numbers fall short of that bar, the gap between JPMorgan’s €245 target and a roughly €118 share price will not close any time soon.