Dear Reader,
Starting as soon as a few months from now, the United States government will make a sweeping change to bank accounts nationwide.
It will give them unprecedented powers to control your bank account.
They could closely track every transaction.
They could even freeze it.
Unless you protect yourself today. Fortunately, there are 4 simple steps you can take to safeguard your savings.
Discover these 4 simple steps here.
Good luck and God bless!
Martin Weiss
Dr. Martin D. Weiss, Founder
Novo Needs Numbers. Today It Delivered Ambitions.
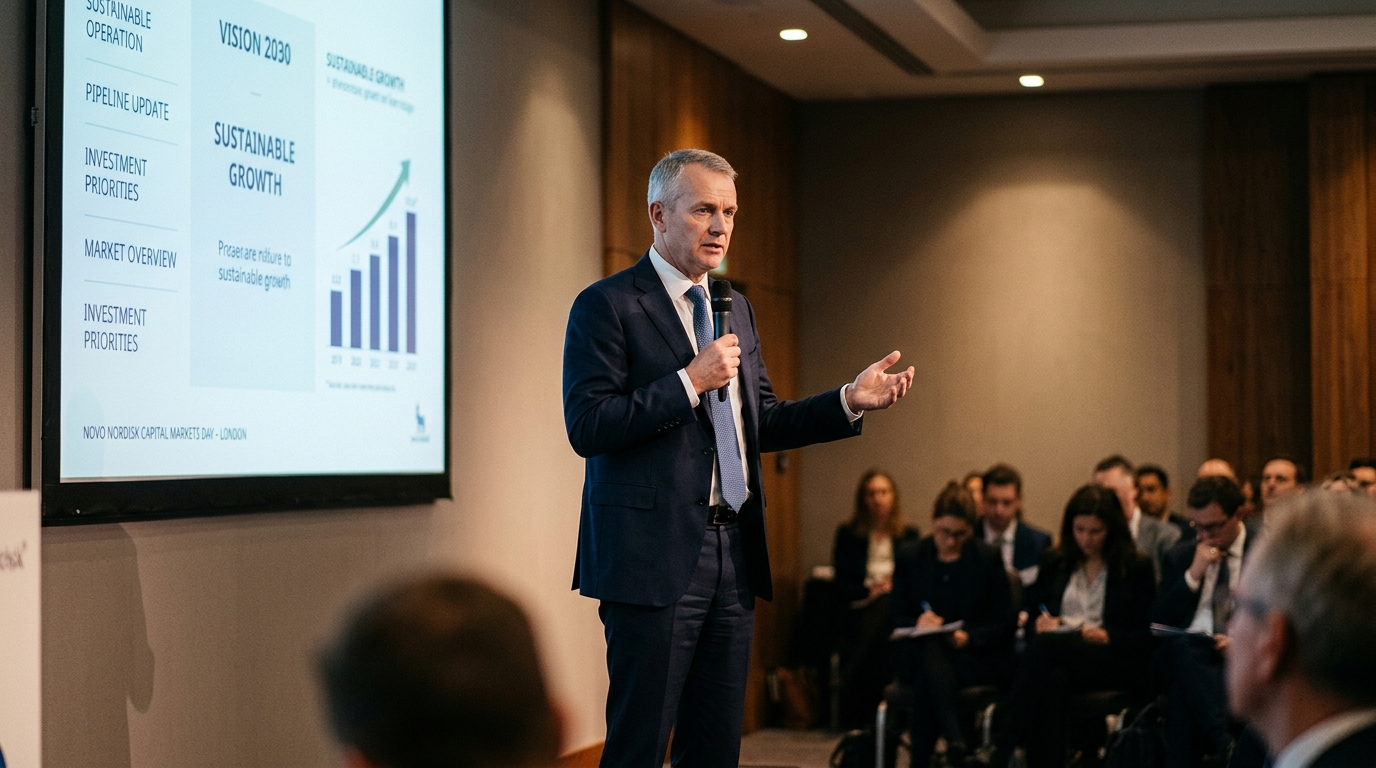
The question going into today was simple: would Mike Doustdar give investors a growth rate or a vision statement? The answer, delivered this morning at Novo Nordisk’s Capital Markets Day in London, landed closer to the latter. NVO fell roughly 5% as the session unfolded.
Analyst Targets
- Morgan Stanley: Underweight, $40 price target (downgrade issued September 11, 2026)
- HSBC: Price target raised to DKK 320 on September 9, 2026
- Street consensus: Hold, mean target approximately $47
Company Profile
Novo Nordisk is the dominant force in GLP-1 obesity and diabetes care, with semaglutide, the molecule inside Ozempic and Wegovy, expected to represent roughly 75% of group sales in 2026. The Rare Disease segment, covering blood disorders and endocrine conditions, provides the rest. The company’s core competitive advantage is its insulin and GLP-1 manufacturing scale, though that advantage is now being tested by Eli Lilly’s Zepbound gaining U.S. share and a semaglutide patent cliff beginning in 2031.
What Doustdar Put on the Table
The strategic ambitions Novo published this morning target 2030 from a 2026 baseline. The company aims to grow revenue at a compound annual rate in line with a defined peer group that includes Eli Lilly, AstraZeneca, and AbbVie, to maintain broadly stable adjusted operating margins, and to generate more than 150 billion DKK in risk-adjusted pipeline sales by 2035. It also set an ambition to launch more than five multi-blockbuster products by 2030 and serve over 60 million patients globally.
Critically, Novo itself flagged that these figures are not financial guidance. That distinction matters to a market that came in demanding hard numbers, not aspirations.
The immediate read-through is that management declined to specify what revenue growth rate in line with peers actually means in DKK terms, leaving the Morgan Stanley bear case largely unanswered.
The Numbers Behind the Slide
- Q2 revenue: DKK 78.49 billion; adjusted operating profit DKK 33.39 billion
- Gross margin compressed to 78.2% from 82.7% a year earlier
- Wegovy injectable sales declined year over year in Q2
- 2026 guidance: adjusted sales and adjusted operating profit growth at constant exchange rates was raised in Q2, not guided as “flat to down 6%”
- Oral Wegovy: over 5 million cumulative U.S. prescriptions after about 30 weeks, one of the strongest U.S. pharmaceutical launches by volume on record
- CagriSema: Novo has disclosed an FDA filing in December 2025; a late-2026 U.S. decision is an expected timeline, not a confirmed action date
Why the Stock Is Sliding
Investors came to London asking a specific question: what does mid-term revenue growth look like in a world where injectable Wegovy is losing share to Lilly’s Zepbound and semaglutide loses exclusivity starting in 2031? The peer-relative CAGR ambition does not answer that question with enough precision to move the Morgan Stanley Underweight off the table.
The ziltivekimab story adds weight. In early September, Novo halted two further cardiovascular studies of the drug, HERMES and ATHENA, after a data monitoring committee found them unlikely to succeed. That removed one of the cleaner paths toward non-obesity revenue diversification. The pipeline now leans heavily on CagriSema and the oral Wegovy international rollout.
Macro and Competitive Context
The GLP-1 market is expanding, with management estimating 40% annual growth and about 46 million patients currently served. That is the structural tailwind. But Lilly’s Foundayo oral GLP-1 approval on April 1 and its Zepbound share gains have shifted the U.S. competitive dynamic enough that injectable Wegovy volumes shrank year over year even as the category grew. Medicaid coverage cuts and price realizations below list are the near-term drag on Novo’s unit economics.
Forward Scenarios
Bull: CagriSema clears the FDA in late 2026 and demonstrates differentiated efficacy over tirzepatide in real-world use, arresting U.S. share loss. International oral Wegovy scaling in the U.K. and Germany drives the revenue CAGR above the peer median. The multiple re-rates from roughly 11x forward earnings toward the mid-teens.
Base: CagriSema launches but competes in a crowded market, contributing incremental rather than transformative revenue. Oral Wegovy holds 90% of the U.S. oral obesity market and grows internationally on schedule. Revenue CAGR through 2030 lands at 5 to 6%, roughly in line with the stated peer ambition, but margins stay compressed. Stock drifts between $42 and $50.
Bear: CagriSema FDA review drags into 2027, pricing pressure widens margin erosion, and semaglutide’s exclusivity timeline pulls forward investor concern about the 2031 cliff. Morgan Stanley’s $40 target comes into play.
Technical Overlay
NVO entered today at $43.24, sitting near the midpoint of its 52-week range of $35.12 to $64.16. The all-time closing high was $135.66 in June 2024. Today’s 5% decline on CMD day pushes the stock back toward the lower half of the range. Key support sits near $40, coinciding with the Morgan Stanley target. The 52-week low at $35.12 is the line that marks structural distress.
Bottom Line
Doustdar arrived in London with a rebrand, a restructuring, and a peer-relative growth ambition. Investors wanted a revenue floor and a margin commitment tied to specific years. The gap between those two things is exactly what Morgan Stanley’s Underweight priced in ten days ago, and today’s market reaction suggests it was not closed. The next real data point is Q3 results on November 4. Until then, CagriSema’s FDA timeline is the single variable most likely to move the stock in either direction.