October 26, 2026
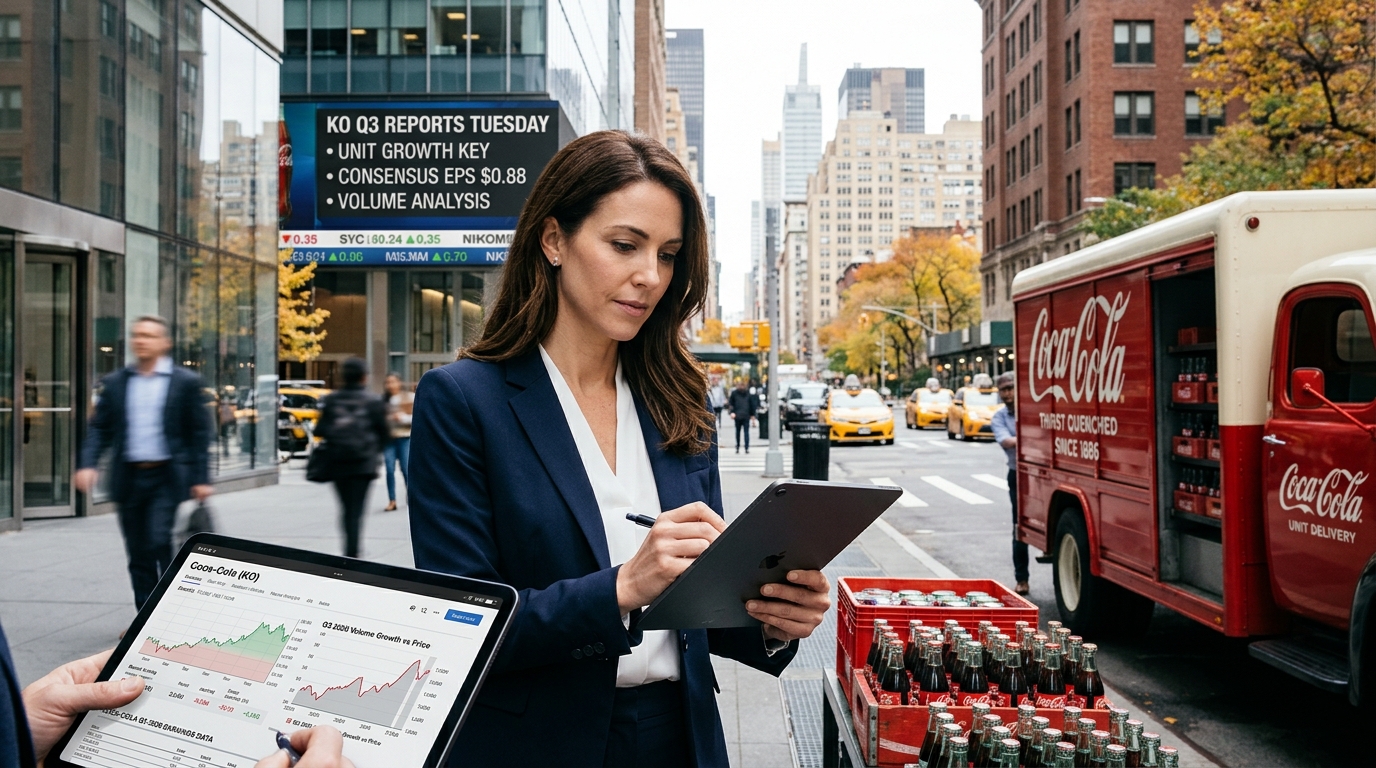
With consensus at $0.88, what KO’s Q3 result means hinges on volume versus price.
Analyst Targets
- Jefferies: Buy, $104
- TD Cowen: Buy, $100
- UBS: Buy, $104
- JP Morgan: Overweight, $95
- RBC Capital: Outperform, $96
- Citigroup: Buy, $97
- Barclays: Overweight, $93
- Wells Fargo: Overweight, $95
Analysts currently give the stock a “Moderate Buy” consensus rating and an average price target of about $96.
For Traders Protecting a Nest Egg
If you’re trading with money you spent decades saving, one bad options trade hurts more than it should.
The first few checks on this list are all about protecting your account before you think about anything else.
The Smart Trade Options Checklist.
Normally $29.97. Free today.
The Run-Up Into Tuesday
Coca-Cola reports Q3 2026 results Tuesday, October 27, before the New York Stock Exchange opens, with the conference call scheduled for 8:30 AM ET. The Street expects earnings of $0.88 per share on revenue of $12.92 billion, compared to $0.82 per share on $12.46 billion in the same quarter a year ago.
Last quarter, Coca-Cola reported $0.97 EPS against about $0.93 expected by the market. Coca-Cola has beaten EPS estimates for six straight quarters, and shares are up about 38% this year. At roughly 30 times earnings, the stock already assumes management keeps delivering.
The Question the Number Will Not Answer By Itself
A headline beat at $0.88 or above tells you one thing. It does not tell you the most important thing: how much of that growth was cases actually shipped versus prices per case pushed higher.
KO’s Q3 earnings may benefit from strong pricing power, organic revenue growth and margin gains, though weak volumes in key markets remain a concern. Persistent volume softness across key markets, particularly North America and Europe, remains concerning, as inflationary pressures and cautious spending among lower-income consumers continue to weigh on demand.
A swing from -1% unit case volume in Q2 2025 to +5% in Q2 2026 was what gave the bull case real structural support heading into this year. The Q3 result will show whether that recovery held through the summer or faded once major event-related demand normalized.
WARNING: AI Is About to Escape Earth (Watch Now)
Sam Altman calls Elonâs plan “ridiculous.”
AI is set to add an estimated $15.7 trillion to the world economy.
But according to Elon Musk, launching AI into the stars could ignite a brand-new $26 trillion market.
Macro Context: A Complex Cost Picture
The consumer staples complex received two data points last week that frame what KO walks into Tuesday.
Nestlé reported organic growth of 4.0% in Q3, with real internal growth reaching 2.8%, demonstrating that volume rather than pricing drove the quarter’s performance. Pricing growth slowed to just 1.1%. That is the gold standard the market now wants to see: volume doing the heavy lifting, price as a secondary contributor.
The volume-versus-pricing split Nestlé demonstrated is exactly the fault line dividing consumer staples winners from laggards. Two staples companies reporting the same week showed how wide that gap can get when volume declines and management cannot offset it with price.
Procter & Gamble delivered the warning. In its fiscal 2027 first-quarter update, P&G said it now expects a commodity cost headwind of about $1.4 billion after tax, up from its previous estimate of $1.0 billion, driven by higher raw materials, energy and transportation costs. Coca-Cola is not immune. Trade policy and commodity volatility still matter, even with a largely franchised bottling system.
Forward Scenarios
Bull
Unit case volume grows above 2% globally, organic revenue lands near the high end of guidance, and management reaffirms full-year EPS of $3.27 to $3.30. Adjusted operating margin expands 20 basis points year over year to 32.1%, led by gross margin improvement. The stock, already near all-time highs, holds its premium multiple.
5 Little-Known Stocks Behind Today’s Defense Tech Shift
Behind the headlines, a major transformation is underway.
Modern warfare is being driven by AI, autonomous systems, and next generation technology. A handful of lesser known companies are helping power this shift.
This report uncovers five stocks quietly playing a critical role in the future of defense.
Base
EPS meets consensus at $0.88. Revenue comes in around $12.9 billion. Volume growth is positive but modest, with price/mix doing the majority of the work. Full-year EPS guidance of $3.27 to $3.30 is maintained. The stock moves less than 2% either direction.
Bear
Volume growth stalls or goes negative in North America or Europe. Revenue misses $12.92 billion on weak case shipments. Management flags commodity cost pressure from packaging and freight in the back half. The stock’s impressive year-to-date rally and premium valuation leave limited room for earnings disappointments, and sustained volume weakness could increase dependence on pricing actions to maintain momentum.
Technical Overlay
Coca-Cola has a 12-month low of $67.27 and a 12-month high of $94.10. KO shares have rallied 38.07% year to date. That run compresses the cushion on any downside reaction. A miss on volume or guidance would have further to correct than at almost any point this year.
What Investors Should Watch
- Unit case volume by geography: North America and Europe specifically, where softness has persisted.
- Price/mix composition: How much of organic revenue growth is real volume versus higher list prices.
- Guidance language on commodities: Whether management quantifies any packaging or freight headwind for Q4.
- Full-year EPS range: Any narrowing or reduction from $3.27 to $3.30 would be a catalyst for selling.
- Analyst revisions post-call: The Q2 result was a beat; a sequential miss would likely produce more target cuts.
Bottom Line
The number that matters Tuesday is not the EPS figure. It is the unit case volume line. Staples stocks often trade on the promise of steady margins and predictable cash flows, so rising costs with limited pricing power can move expectations quickly. Coca-Cola has engineered a strong year on the back of pricing discipline and improved volume trends. What it has not fully proven, heading into a higher-cost second half, is that cases sold can grow on their own. That is the debate Tuesday’s report will either settle or extend.