October 31, 2026
Bonus Content: Dell’s 11% Drop Exposes a Company Running Two Opposite Businesses
Most people trade same-day options one way.
They buy a cheap call or put in the morning and hope the market moves far enough, fast enough, before 4:00 PM.
Usually it doesn’t. The clock runs out and the option expires worthless.
But the trader on the other side of that ticket is playing a completely different game.
They sell the option. They collect cash when the trade opens. And instead of needing a big move, they just need the market to stay away from a price they picked.
I lay out a simple 3-step way to trade that side – with your max loss set before you click – in my new report, The 0DTE Game Plan.
It sells for $29.97 on our website. Today, you can get it free.
Good Trading,
Bill Poulos
p.s. Selling same-day options carries real risk, and the report shows you exactly how to cap it. Grab your free copy here.
Dell’s 11% Drop Exposes a Company Running Two Opposite Businesses
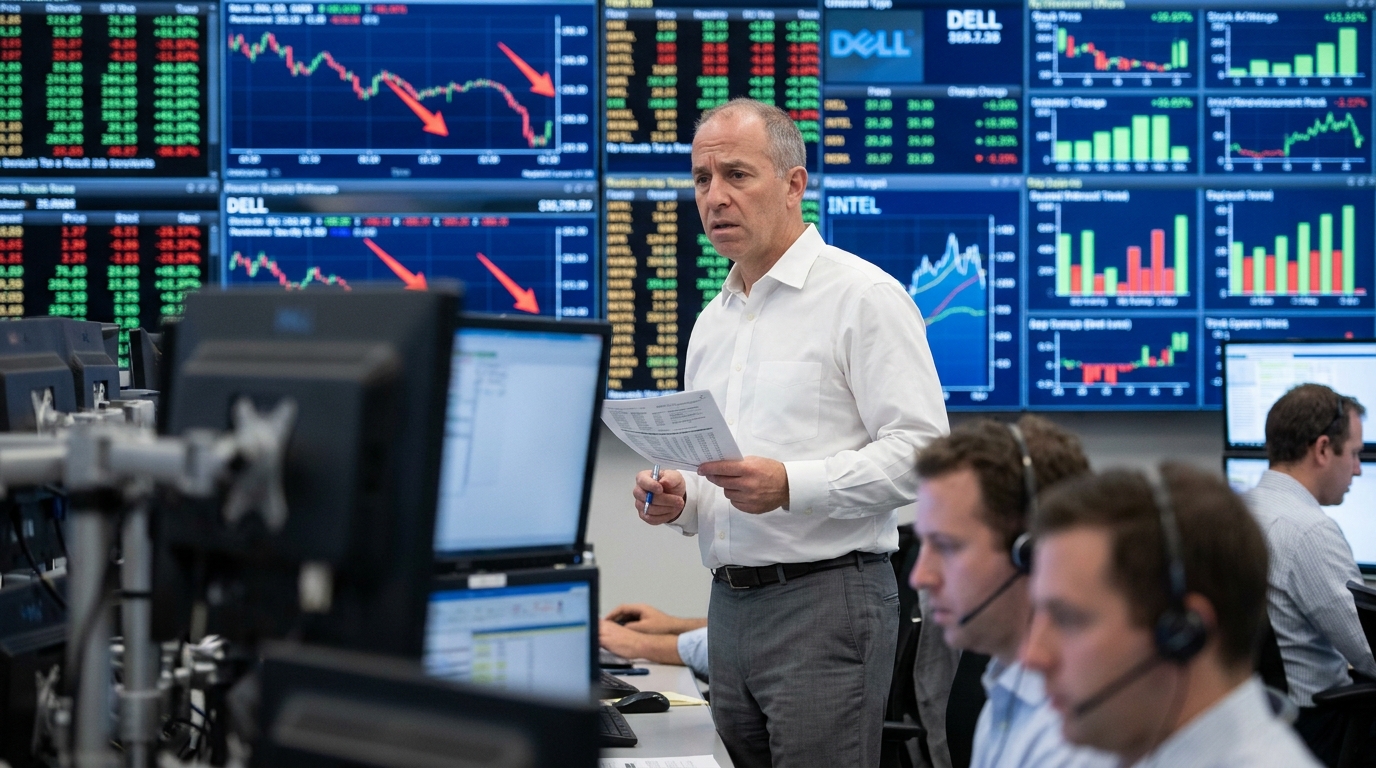
Dell Technologies closed Friday down 10.77%, ending the session at $424.30. The trigger was Intel’s Q3 earnings call Thursday night, where management said the 2026 PC unit total addressable market is expected to decline about 12%, with second-half units down more than 20%. The message reinforced what Gartner’s shipment data had already confirmed: the PC market is contracting at a pace that makes the word “cyclical” feel generous.
Analyst Targets
- TD Cowen: Hold, $550 price target (raised from $500)
- Truist Securities: raised to $505, citing AI backlog visibility into fiscal 2028
- Consensus: Moderate Buy, average target approximately $597
What Intel Said
Intel said it expects the 2026 PC unit total addressable market to decline approximately 12%, with second-half units down more than 20%. Management also outlined a planning assumption for 2027 of roughly another 10% decline in PC unit demand. Critically, CEO Lip-Bu Tan said the pace of the correction has accelerated over the last two months as OEM partners manage inventory to match softer sell-through, and Intel expects the weakness to last through at least the first half of 2027.
The forecast lands differently when Gartner’s Q3 shipment data sits next to it. Global PC shipments totaled 55.4 million in Q3 2026, down 22.4% from the 71.3 million shipped in the same quarter a year earlier. That decline is roughly double the 10.4% full-year 2026 decline Gartner had projected earlier this year.
The memory shortage is the mechanism driving both sides of Dell’s story simultaneously. DRAM suppliers have deliberately converted conventional memory capacity to high-margin HBM, tightening supply for PC assemblers while feeding AI server demand.
Dell’s Client Business: The Operational Evidence
Gartner’s preliminary Q3 2026 estimates show Dell shipments fell 25.4% year over year to 7.583 million units, while HP declined 30.9% to 10.366 million. The cause is not a mystery. Gartner attributed the contraction largely to component cost inflation, including higher memory and storage costs pushing up average selling prices and eroding affordability.
This is the second straight quarterly decline, and a much deeper one than Q2. Shipments slipped 9.1% compared to Q2, even though Q3 is normally the bigger quarter. IDC attributes this to the first half of the year, when vendors stocked up ahead of memory-driven price hikes, pulling volume out of the second half. With supply still constrained and prices high, Q3 had little demand left to absorb. The decline could deepen to 27% across the market in Q4.
The AI Server Business: A Separate Story
Here is where Friday’s sell-off gets complicated for investors making a longer hold decision. Dell’s Infrastructure Solutions Group is running at a different speed entirely. Dell booked $60.9 billion in AI server orders during the most recent quarter and ended the period with an AI server order backlog of $95 billion. CEO Jeff Clarke has said Dell booked more than $130 billion in AI server orders over the last 12 months, with management guiding full-year AI server revenue to $74 billion.
Intel, meanwhile, said it expects industry server CPU units to grow more than 30% in both 2026 and 2027, noting growth would be higher if additional supply were available. The same memory shortage crushing PC affordability is generating margin for DRAM suppliers and keeping AI infrastructure demand insatiable. The problem for Dell is that one segment is subsidizing the other’s poor optics.
Dell is not the only AI server assembler caught between a collapsing PC market and surging infrastructure demand. Super Micro raised its fiscal Q1 revenue forecast by four billion dollars, citing accelerating demand for AI platforms.
Bull / Base / Bear
Bull: The $95 billion AI server backlog is largely noncancelable. TD Cowen noted that Dell’s AI server backlog is mostly noncancelable, with leverage to major neoclouds. If memory normalizes by mid-2027, the PC drag lifts just as ISG backlog converts. The stock at current levels prices in a client collapse without crediting the server cycle.
Base: Client Computing remains under pressure through at least H1 2027, compressing blended margins and offsetting ISG momentum. The stock trades sideways or recovers partially as analysts adjust models. Consensus targets near $597 imply roughly 41% upside from Friday’s close, which is achievable only if ISG execution holds.
Bear: Memory prices stay elevated longer than forecast. Until memory supply and pricing stabilize, Intel’s outlook suggests pressure on traditional hardware could extend well beyond the current earnings cycle. If CSG revenue declines sharpen and ISG margins compress under component costs, the stock re-rates lower without a fundamental floor from the client business.
Technical Overlay
Dell’s Friday close at $424.30 represents a clean break from the $460-480 consolidation range that had held since late September. The stock has now given back roughly half of its post-Q2 earnings surge. The next meaningful support sits near $390, which corresponds to the August gap-fill level. A close above $445 would be needed to signal that Friday was an overreaction rather than a trend change.
Bottom Line
Dell did not report earnings Friday. It took a 10.77% haircut because someone else did. That is the market’s way of forcing investors to separately price two businesses that Dell has been quietly bundling together. The AI server backlog is real, contracted, and growing. The PC business is in a structural contraction driven by a cost shock in memory that no PC assembler controls. Friday’s move is less a verdict on Dell’s execution and more a demand that investors stop treating them as the same story. The next earnings call, expected in late November, will be where both cases get stress-tested with actual revenue and margin data.