Hi,
Quick question: when did you last pay for pest control?
A termite inspection. A mosquito treatment for the yard. A can of bug spray under the sink.
Whatever it was, you’ll pay for it again. And that’s the part most people miss.
When the public turns on a product, people usually stop buying it. But some things can’t be quit.
Termites still eat houses.
Rodents still get into food plants.
Crops still need protecting.
And the mosquito still bites.
So as conventional pesticides face more scrutiny, from health research and lawsuits to regulators and corporate buyers rewriting their standards, the need doesn’t go away. The spending may simply move.
Our new investor letter follows where it could go, and introduces a small company that has spent years building botanical products for exactly that shift.
Where does that money go next? →
P.S. The letter also covers what most stories skip: the counterarguments. You may not agree with the conclusion. Read it and decide →
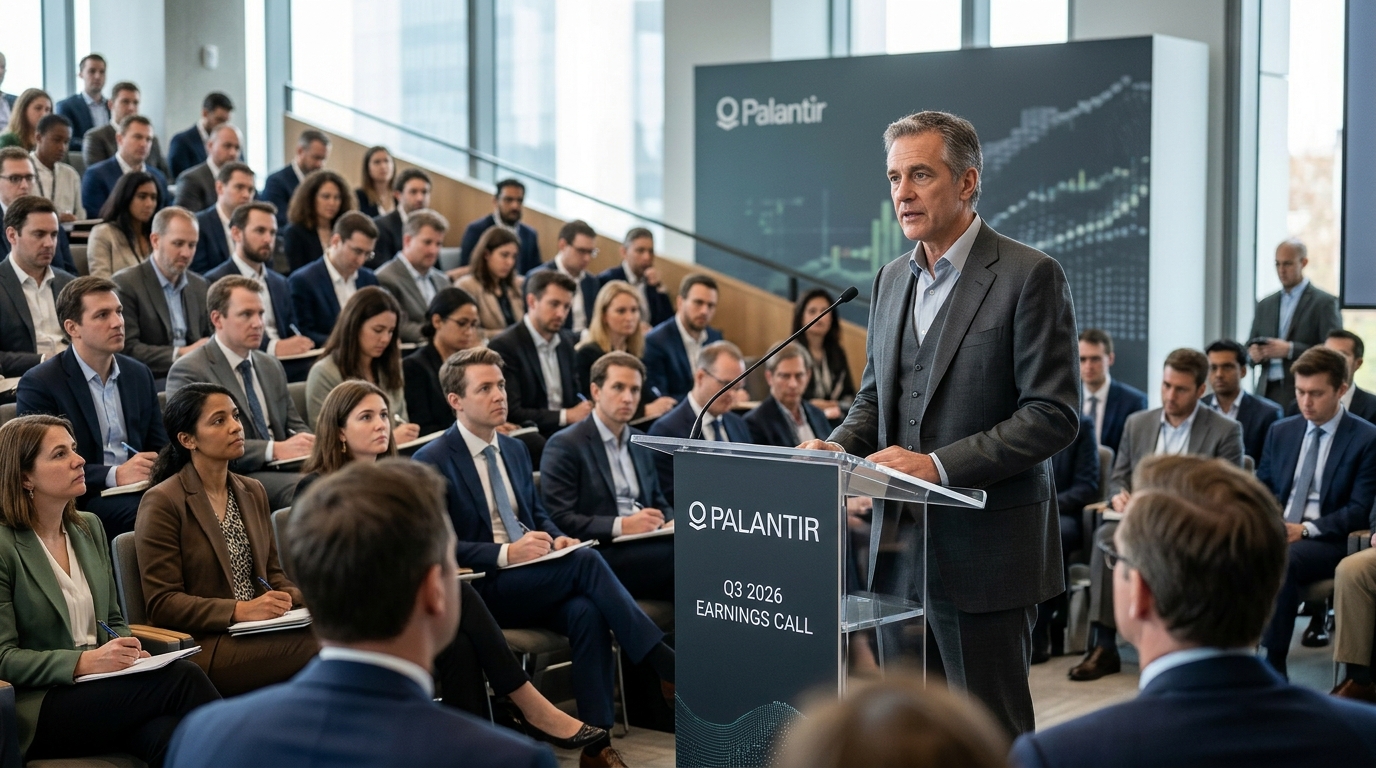
Palantir Faces Its Toughest Crowd Yet on Monday
Analyst Targets
- JPMorgan: Overweight (initiated) | $262 (December 2027), added to Analyst Focus List and Positive Catalyst Watch
- Citi: Buy | $250 (raised from $245 ahead of earnings)
- Rosenblatt: Buy | $260 (raised this week)
- RBC Capital: Underperform | $90, cites Palantir as the most expensively valued name in software coverage
- Consensus: Buy, average target ~$212.50
The Moment
Palantir reports Q3 2026 after Monday’s close into the worst possible backdrop for software bulls. Fortinet and ServiceNow both beat revenue estimates last week and both stocks cratered anyway, dragging dozens of other software names down with them. ServiceNow alone fell 26.9% on Thursday, October 29. The sector did not punish failure. It punished ambiguity in the outlook, and now Palantir walks into that same room carrying the richest valuation in large-cap software.
As of late October 2026, Palantir carries a market cap of roughly $440–$480 billion. That is not a valuation that forgives a cautious Q4 guide.
Company Profile
Palantir builds AI and data integration platforms for governments and large enterprises. Its two flagship products, Gotham for defense and intelligence clients and AIP for commercial customers, give it a footprint few software companies can replicate. The U.S. commercial business is the growth engine right now. In Q2 2026, U.S. commercial revenue grew 149% year-over-year and total revenue grew 93%, pushing the Rule of 40 score to 155%. That kind of growth rate, sustained at this scale, is what justified the stock’s re-rating through the summer.
The Numbers Going In
For Q3, Palantir’s own guide calls for revenue of $2.160 to $2.164 billion. Wall Street expects earnings of about $0.41 per share, on revenue of about $2.18 billion, consensus already sits above the company’s own midpoint.
- Q3 adjusted income from operations guidance: approximately $1.29 billion, versus $601 million in the year-ago quarter
- Full-year 2026 revenue guidance raised to $8.150–$8.158 billion, with U.S. commercial revenue guided above $3.424 billion, at least 134% growth
- Palantir has beaten both earnings and revenue estimates in each of the past eight reported quarters
Why the JPMorgan Initiation Matters
JPMorgan analyst Brian Essex initiated coverage with an Overweight rating and a $262 price target for December 2027. The bank also placed Palantir on Positive Catalyst Watch ahead of the November 2 earnings report. The $262 target is not built on a simple growth assumption. Essex’s core argument: businesses are increasingly adopting Palantir’s technology to get better returns on AI investments, and growth is accelerating.
The bear case has an equally credible institutional voice. RBC Capital has reiterated its Underperform rating and $90 price target, emphasizing that it continues to see Palantir as the most expensively valued name in its software coverage universe. The spread between those two targets, $172 wide, tells you everything about the disagreement that Monday’s report will arbitrate.
Macro Context
The same three things keep setting off software selloffs: slowing forward metrics, high valuations, and market worry that AI will pull spending away from traditional software. Palantir argues it is the AI beneficiary, not the AI casualty. That case holds as long as AIP deal volume keeps accelerating. If Q4 guidance shows any deceleration in U.S. commercial growth, the sector’s mood this week will make the reaction asymmetrically harsh.
Forward Scenarios
Bull
Q3 revenue clears $2.18 billion, U.S. commercial growth holds above 130% year over year, and management raises full-year guidance above $8.16 billion. JPMorgan’s $262 target becomes the new consensus anchor. Options markets price a double-digit move; a clean beat-and-raise sends the stock back toward the 52-week high at $212.94.
Base
Revenue lands near $2.16–$2.18 billion. Palantir beats its own guide narrowly, raises full-year guidance modestly, and the stock finishes within 5% of Monday’s open. The valuation overhang keeps a lid on the upside even on a solid quarter.
Bear
Any softness in Q4 guidance or a deceleration in U.S. commercial growth repeats what happened to ServiceNow. With valuation this stretched, there is no floor built into the multiple. A technical breakdown below $184 opens a broader support zone near $160–$166, and the sector’s current mood provides no cushion.
Technical Overlay
The stock has fallen below its 50-day moving average near $187, which is a notable change from the momentum structure it held through October. The bigger-picture trend remains constructive, with price sitting about 24% above the 100-day SMA at $160.12 and about 30% above the 200-day SMA at $153.26. Key resistance sits at $213, right at the 52-week high zone, while $184.50 near the 50-day SMA is the critical support level to watch on any post-earnings drop.
Bottom Line
The question Monday answers is not whether Palantir is a good business. It clearly is. The question is whether the business is good enough to hold a lofty revenue multiple in a market that just demonstrated it will not pay for even a slight miss on forward metrics. JPMorgan’s initiation gives institutional cover to the bull case. The software sector’s week gives the bears their best entry argument in months. What actually moves the stock is simple: the Q4 guide and the U.S. commercial growth rate. Everything else is noise.