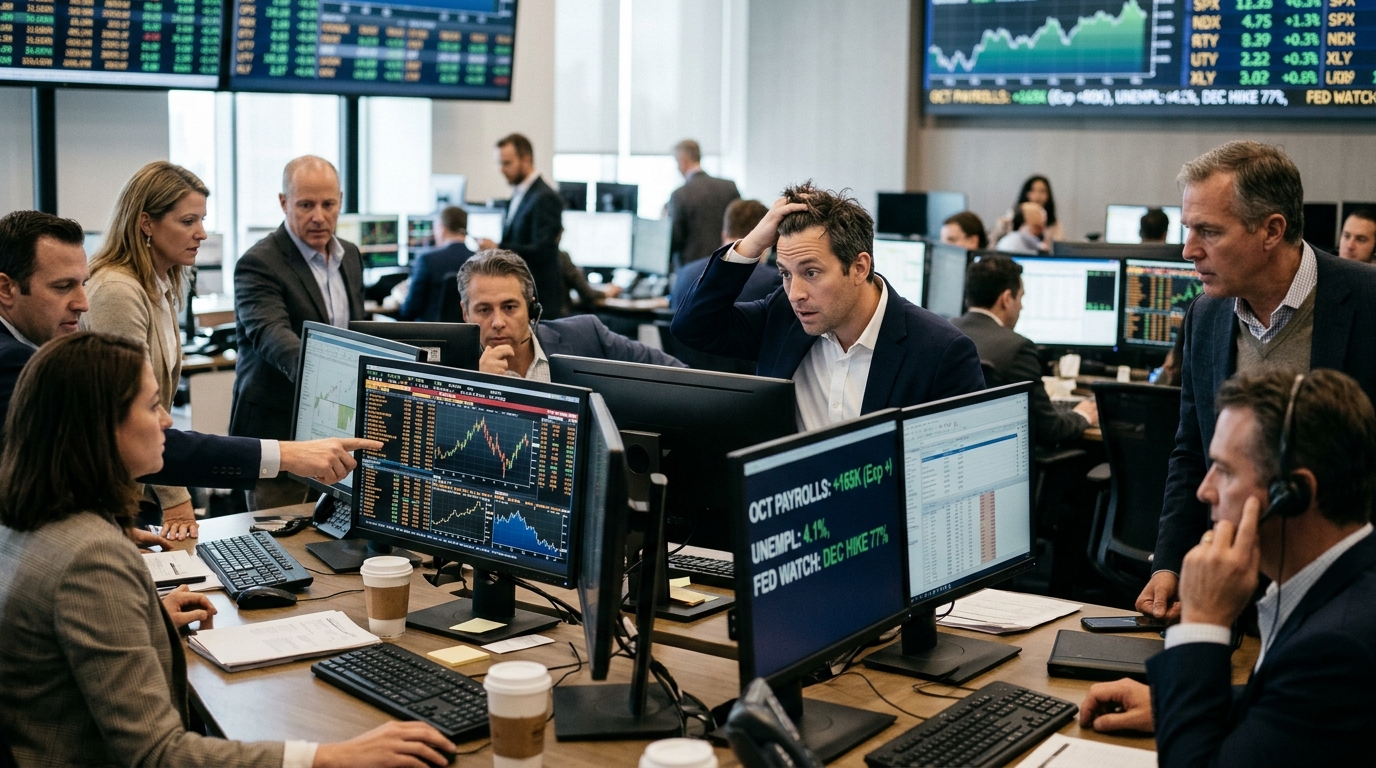
Friday’s payrolls number was not close. U.S. employers added 165,000 positions in October, more than double what economists expected, while the unemployment rate slipped to 4.1%. The jobs reports for August and September were revised upward, with an additional 53,000 jobs in August and 31,000 more in September. That is a labor market that refuses to slow on cue.
Traders now see about a 77% chance of a 25 basis point rate hike next month, up from roughly the mid-60s on Thursday, according to CME FedWatch. Markets had already been building toward December after Fed Chair Kevin Warsh emphasized that inflation remains too high and that the Fed remains committed to price stability. Friday’s data removed the last credible counterargument.
The yield on the 10-year Treasury rose to about 4.88% on November 6, marking a roughly 0.04 percentage point increase from the prior session. The dollar index climbed to 102.30 on November 6, up 0.74% on the day. Those two moves together define the trade environment for the next several weeks.
What the Report Actually Said
Professional and business services led private sector gains, adding 70,000 jobs. Healthcare and social assistance added 55,100 jobs, the sector’s largest gain since April. Manufacturing added 19,000 jobs, led by durable goods. These are not the numbers of an economy on the edge of contraction.
The one wrinkle worth watching: the U-6 rate, which includes discouraged workers and those forced to accept part-time rather than full-time jobs, rose to 7.9%, with part-time for economic reasons contributing to the move. That tension between headline strength and underemployment breadth is the detail most traders are ignoring. It matters because it complicates Warsh’s path after December. A hike now does not automatically mean another in February if part-time absorption stalls.
Sector Rotation: Follow the Rate Beneficiaries
The cap-weighted SPY is a poor guide to what is actually happening. While the headline S&P 500 fell about 0.9% in October due to its heavy tech concentration, the equal-weight index surged 5.0%, and the Dow Jones gained about 1.8%. Breadth is broadening, not collapsing.
Leadership in the S&P 500 is shifting from technology and communication services toward energy and healthcare. Over the four weeks through October 30, the benchmark fell 1.1% while its equal-weighted counterpart gained 4.4%, pointing to sector rotation as market leadership broadens despite pressure on the headline index.
As of November 6, financials (XLF) have been showing improving short-term momentum, while healthcare (XLV) has held up as a leader. With the 10-year near 4.9% and a December hike now the base case, financials carry the clearest fundamental tailwind: wider net interest margins and no duration liability.
All 11 S&P 500 sectors finished in the red on Thursday, with information technology bringing up the rear, down 7.3%. Long-duration growth names face a straightforward arithmetic problem at these yield levels. A 10-year above 4.85% compresses the present value of earnings three to five years out, and Friday’s data makes a move back below 4.5% before year-end unlikely.
The Trading Plan
The highest-conviction rotation from here is out of rate-sensitive long-duration growth and into financials and select industrials. XLF has the clearest macro support. The dollar at 102-plus pressures multinationals with heavy overseas revenue, so domestic-facing businesses carry an additional edge.
On SPY itself: watch the $761 level as the first meaningful support. Reclaiming $768 on SPY is the confirmation level for the post-election rotation broadening further beyond consumer and financial leaders. A failure there, combined with QQQ weakness, signals the rotation is turning into something heavier.
The risk traders are underweighting is what comes after December. Markets are pricing a higher-for-longer path, with fed funds futures implying a policy rate a bit above 4.1% near the end of 2027. If that path holds, the compression on long-duration tech is not a one-week event. It is the dominant theme for Q1 as well. Position accordingly.